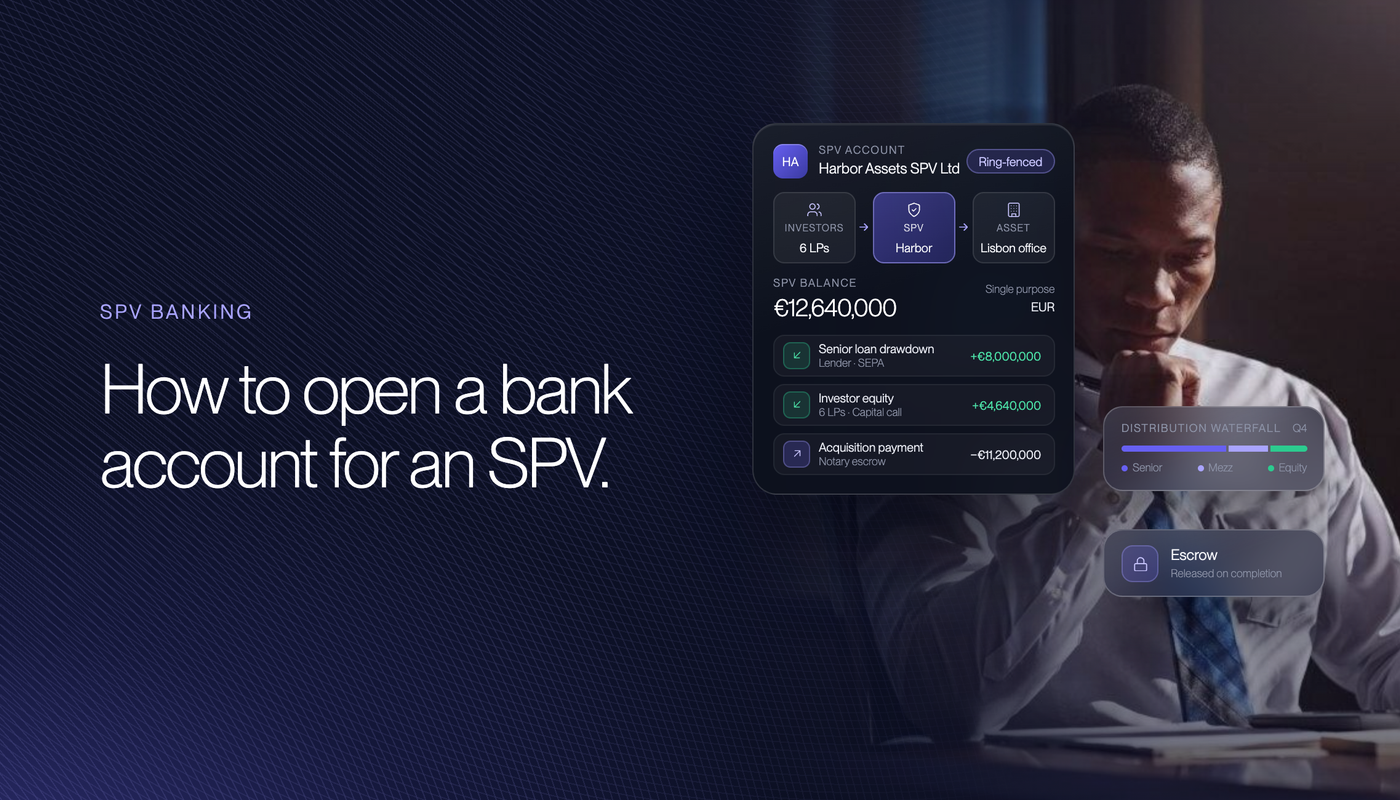
A bank account for an SPV is what makes the special purpose vehicle work. Investor money comes in, the asset or deal is paid for, rent or returns are collected and distributions go out, without touching the parent's or investors' own accounts. A separate account also helps keep the SPV legally apart from the rest of the group, which is often why it exists.
The hard part is the bank. On paper an SPV looks like a shell company: no staff, no office, no trading history and owners who sit behind other companies. Revolut Business lists special purpose vehicles as unsupported, Starling turns away holding companies and corporate shareholders, and offshore banks take SPVs mainly through a licensed administrator.
You do not need to do that alone. We prepare the SPV's file, from the structure chart to the deal behind it, and place it with our regulated banking partner, which specialises in SPVs and complex structures and opens multi-currency accounts in about a week.
Our top-rated, licensed banking provider for complex structures opens multi-currency accounts for SPVs in about a week, with no branch visit and owners in most countries.
Interpolitan Money
Business account
Time to onboard
1 Week
Currency
EUR, USD, GBP, AED, and 50+
Monthly fee
Custom
Why a Bank Account for an SPV Is Hard to Open
A bank account for an SPV is hard to open because everything that makes an SPV useful looks like a risk to a bank. It is built to hold one asset or carry one deal, it has no staff or premises, it may be days old, and its shares are often owned by another company. The bank has to see through all of that to the people behind it, the money going in and the reason the vehicle exists.
An SPV Looks Like a Shell Company on Paper
The IMF and OECD describe a special purpose entity as a registered company "with no or little employment up to maximum of five employees, no or little physical presence and no or little physical production" where it is based. ADGM says plainly that SPVs "cannot be used to conduct operational business or hire staff." That is the whole point of an SPV, and it is also close to how banks define a shell. Tide, for example, will not serve a company "based in a country in which it provides no meaningful services and has no physical presence involving meaningful decision-making and management."
The Owners Sit Behind Other Companies
Most SPVs are owned by a holding company, a fund, a trust or a group of investors, so the bank has to trace each layer back to people. Mercury will not accept an entity as a beneficial owner and traces ownership to individuals holding 25% or more. Butterfield in Cayman asks for every intermediary entity in the ownership chain, with its jurisdiction and percentage, and a tax declaration from each owner above 10%. For pooled investment vehicles, US rules let banks skip the investors but still require the person who controls the vehicle, such as the general partner.
Open a Bank Account for Your SPV
A bank account for an SPV is very achievable when the structure is explained before the bank asks. This is what we do for you.
- SPV specialists: Our partner builds its accounts for SPVs and complex structures.
- Offshore SPVs welcome: BVI, Cayman, Jersey, Isle of Man, Luxembourg and UAE vehicles.
- Banks slow to onboard: An account in about a week, not months of back and forth.
- Capital calls in 50+ currencies: EUR, USD, GBP, AED and more in one account.
- Structure chart and deal note: Written the way reviewers want to read them.
- Clear pricing, no surprises: One quote before we start.
No Trading History
A new SPV has no accounts, no turnover and no bank statements, and many banks want all three. Allica's business account is for businesses "up and running for at least 12 months" that deposit £50,000 or more, unless they already borrow from Allica. Monzo Business wants a company that makes money "mostly from selling goods and/or providing services, not mostly from interest or investment income", which a passive holding or investment SPV fails on its face.
Lenders Need Control of the Account
A property or project SPV that borrows usually has to give its lender control of the account. Law firm Macfarlanes explains that control "is usually achieved by the lender being sole signatory on the bank account mandate", and that account banks are "expecting to negotiate or rejecting the standard form acknowledgement of security". Its advice is to talk to the account bank "before account opening".
Why SPV Bank Accounts Get Refused
European banking guidelines tell banks to ask whether a customer "could be used as an asset-holding vehicle", whether it has nominee shareholders, and whether a complex structure has "an obvious commercial or lawful rationale." The UK's 2025 national risk assessment warns about "UK companies in complex structures" used to launder money. Airwallex bars any entity with bearer shares in its ownership chain, and SPVs registered in the British Virgin Islands face extra checks while the territory sits on the FATF grey list. Banks rarely explain a refusal, so the file has to be right the first time.
Read more: Why banks reject business account applications and what is an SPV company.
Banks That Open SPV Accounts
Plenty of banks will take an SPV in principle, but each one has a rule that shuts out a large share of them. The table shows what the main options publish.
Bank | Who it takes | Who it turns away | Monthly fee or minimum |
|---|---|---|---|
Channel Islands banks (Barclays, Butterfield, Lloyds) | SPVs introduced by fiduciaries and fund administrators | SPVs with no licensed administrator behind them | Relationship based, plus yearly risk charges |
Butterfield (Cayman) | Funds, holding companies and special purpose insurers | SPVs that cannot list every intermediary in the chain | $2,500 minimum balance |
Mercury (US) | US-formed funds, SPVs and management companies | Companies formed outside the US | $0 to $299 a month |
Allica Bank (UK) | UK businesses trading for 12 months with £50,000 to deposit | New SPVs without an Allica loan | £25 a month below a £10,000 average balance |
Starling (UK) | UK companies owned by UK-resident individuals | Holding companies and any corporate shareholder | No monthly fee |
Monzo and Tide (UK) | Small trading companies | Investment income businesses and shell companies | Plan based |
Revolut Business | Most trading companies | Special purpose vehicles and entities | Plan based |
Digital banks are not an answer either. Revolut Business still lists "Special purpose vehicles/entities" among unsupported industries, Wise restricts trust and corporate service providers that use nominees to obscure ownership, and Airwallex will not open for bearer share entities. Choosing a bank for an SPV comes down to where it is registered, who owns it and what it will hold.
Offshore Banks Want an Administrator
In Jersey, Guernsey and the Isle of Man, banks take SPVs mostly through licensed fiduciaries and fund administrators, and price the relationship accordingly. Barclays charges fiduciaries a £500 yearly intermediary fee and fund administrators £250. Butterfield's Cayman application asks whether an intermediary will be involved in managing the account, and lists every intermediary entity in the ownership chain. An SPV without an administrator it trusts struggles to get in the door.
Platforms Bank Syndicate SPVs, Not Every SPV
Venture platforms open accounts for the SPVs they form. Carta says it "will set up the bank account for the SPV", AngelList gives each SPV its own sub-account at a partner bank, and Sydecar says its vehicles can be set up within hours. The catch is scope: these accounts are for deal vehicles run on the platform, Sydecar supports only accredited investors, and fees start at $4,500 at Sydecar, while AngelList charges $8,000 plus a $2,000 regulatory charge. A property SPV, a holding SPV or an offshore structure needs a different route.
Security and Risk Charges
Offshore banks price complexity and lender security into the account. Butterfield in the Channel Islands charges £2,500 a year for a high-risk account and £4,500 where a politically exposed person is involved. A security interest agreement costs £2,500 to set up at Butterfield and Lloyds, and £1,000 to £5,000 at Barclays, with yearly charges of £500 to £1,000 at Butterfield and Lloyds. Lloyds may add up to £10,000 a year per entity for enhanced due diligence.
Read more: Business bank account vs EMI account and best countries for business banking.
Interpolitan Money
Business account
Time to onboard
1 Week
Currency
EUR, USD, GBP, AED, and 50+
Monthly fee
Custom
A Faster Way to Open a Bank Account for an SPV
There is a better alternative to the bank queue. Our partner, Interpolitan Money, is an electronic money institution authorised by the UK Financial Conduct Authority, with a Dubai International Financial Centre entity licensed by the DFSA. It works with SPVs incorporated in the BVI, Cayman, Jersey, the Isle of Man, Luxembourg and the UAE, providing multi-currency accounts where mainstream banks cannot or will not. It describes offshore incorporation, layered ownership and non-resident shareholders as features rather than red flags.
Each SPV gets a multi-currency account holding 50+ currencies, with a unique IBAN or account number for each currency. Payments run over SWIFT, SEPA, SEPA Instant, Faster Payments, BACS and CHAPS, and batch payments pay every investor in one go. Fund clients use it for capital calls, investor distributions and multi-jurisdiction structures, and new SPV entities can be added as sub-accounts in under 48 hours. For UK property SPVs there is a dedicated account with no set-up cost and no monthly fee. Every client gets a named relationship manager.
We prepare the file before the partner sees it: the constitutional documents, the registers, a structure chart, identity documents, a note on the deal and a written source of funds. Client money is held in segregated safeguarding accounts at major banks, separate from the partner's own funds. Be clear about what the account does: it receives, holds, converts and pays money. It does not offer loans, pay interest or hold securities, and it is not covered by the UK deposit guarantee scheme.
Feature | Banks | Our partner |
|---|---|---|
Time to open | Weeks, often longer for offshore SPVs | 48 hours to 10 days |
Who they accept | Trading companies, or SPVs through an administrator | SPVs in the BVI, Cayman, Jersey, Isle of Man, Luxembourg and UAE |
Corporate shareholders | Refused at Starling | Layered ownership accepted with a clear chart |
Minimum balance or deposit | $2,500 at Butterfield Cayman, a £50,000 deposit at Allica | No minimum balance on non-resident accounts |
Monthly cost | £0 to $299 a month, or relationship based | Custom, and no monthly fee on UK property SPV accounts |
Currencies | Separate currency accounts, often with extra fees | 50+ currencies in one account |
International payments | £13 to £92 each at offshore banks | £5 to £15 each |
Lending and custody | Available at banks | Not offered, funds safeguarded instead |
For an SPV that needs to take in capital, pay for an asset and send money to investors in several currencies, our partner is faster and simpler. A bank still suits an SPV whose lender insists on its own account bank, and the two can sit side by side.
Which SPVs Our Partner Accepts
Our partner looks at SPVs that hold something real: a property, shares in a target company, a loan book, a fund investment or the proceeds of a sale. Property SPVs, fund SPVs, segregated portfolio companies, VCCs and other private capital structures are in scope, and its escrow service covers M&A, property and high-value private sales when a deal needs a neutral account. What it will not take is a structure that hides who is behind it, money with no clear source, sanctioned links or payments to restricted countries and industries. We check the fit before you apply.
Opening an SPV Bank Account Online
Opening an SPV bank account online works in four steps. We build the file with you, the directors and owners verify their identity and sign the application, the partner's compliance team reviews the structure and asks any questions through us, and the account goes live with its IBANs and account numbers. No director has to visit a branch, and the owners can live in most countries.
Interpolitan Money
Business account
Time to onboard
1 Week
Currency
EUR, USD, GBP, AED, and 50+
Monthly fee
Custom
Documents for Opening a Bank Account for an SPV
The documents for opening a bank account for an SPV cover the vehicle, every layer above it and the deal it was formed for. We gather them with you and write the parts reviewers care about most.
Company Documents and Registers
Start with a certified certificate of incorporation, the memorandum and articles or other constitution, a certificate of good standing, the registers of directors and shareholders and evidence of the registered address. Our partner's guidance asks for a structure chart for any complex or offshore entity. An offshore SPV adds a certificate of incumbency from its registered agent.
The Structure Chart
Show every layer from the SPV up to the people at the top: holding companies, funds, trusts, foundations and investors, with countries and percentages. Mark anyone with 25% or more, and anyone who controls the vehicle without owning it, such as a general partner, a fund manager or a lender with signing rights. A clear chart answers most of the questions a reviewer would otherwise send.
Director and Owner Identity
Every director, signatory and beneficial owner provides a certified passport and a recent proof of address. Our partner asks for proof of address dated within the last three months and does not accept mobile phone bills. In the UK, directors and people with significant control must now verify their identity with Companies House, a rule phased in from 18 November 2025.
The Deal Behind the SPV
Explain in a page what the SPV is for: the asset, the price, where the money comes from, who the investors or lenders are and how returns will flow out. A term sheet, a sale agreement or a facility letter makes it concrete. For a new SPV with no bank statements, our partner accepts a valid reason for their absence, and the deal note is that reason.
Source of Funds and Tax Forms
Show where the capital comes from: the parent's accounts, the fund's commitments or each investor's contribution. Add the tax forms: a W-9 for a US SPV or a W-8BEN-E for a non-US one, and the CRS self-certification for the entity and its controlling persons.
Read more: Documents needed to open a business bank account and business bank account requirements.
Prepare Your SPV Bank Account File
An SPV account opens fastest when every layer fits on one page and the deal is explained. We prepare it with you.
- Structure chart signed: Every layer up to the people at the top.
- Deal note written: The asset, the money and how returns flow out.
- Company pack: Incorporation, constitution, registers and good standing.
- Lender terms ready: Mandate and security needs agreed early.
- Tax forms ready: W-8 or W-9 and CRS self-certification.
SPV Bank Account Costs
SPV bank account costs look small at a digital bank and grow fast once the SPV is offshore, borrows or has layered owners. The real cost is in minimum balances, risk charges, security fees and payments. The table sets typical ranges at banks against our partner's published pricing.
Charge | Typical range at a bank | With our partner |
|---|---|---|
Account opening | Free to £250 per legal entity | Free for UK property SPVs, otherwise set in your fee schedule |
Monthly or maintenance fee | £0 to $299 a month, or £40 a quarter at offshore banks | Custom, no monthly fee on UK property SPV accounts |
Minimum deposit or balance | $2,500 to £50,000 | No minimum balance on non-resident accounts |
Yearly high-risk charge | From £2,500 at some offshore banks | None published |
Yearly charge where a PEP is involved | From £4,500 | None published |
Enhanced due diligence fee | Up to £10,000 a year per entity | None published |
Payment out in EUR or GBP | £13 to £92 at offshore banks | £5 |
Payment out in USD | $15 to $70 | £10 |
Payment out in AED and other currencies | £13 or more, plus correspondent fees | £15 |
Urgent payment | Varies by bank | £10 extra |
Payment instructed by phone or email | £20 to £92 manual fee | £40 |
Additional currencies | £15 a month per currency account at some banks | 50+ currencies in one account |
For an offshore or borrowing SPV, the biggest cost is usually the security and risk charges. An SPV with a lender and a politically exposed owner can face a £2,500 security set-up fee and £4,500 a year in risk charges at a Channel Islands bank before a single payment is made. Currency adds more: a 2% margin on $2 million of capital calls and distributions costs $40,000. A UK trading bank or a venture platform can be the cheaper choice for a simple UK or US deal vehicle, and it is fair to say so. All figures are planning ranges drawn from published tariffs, and we confirm your final price in writing before you apply.
Interpolitan Money
Business account
Time to onboard
1 Week
Currency
EUR, USD, GBP, AED, and 50+
Monthly fee
Custom
How Long SPV Bank Account Opening Takes
A bank account for an SPV takes weeks at most banks and longer for offshore vehicles with layered owners. Venture platforms are faster for their own deal vehicles: Carta says its SPV accounts usually open in 48 hours, and Roundtable launches European SPVs in two to five business days. With our partner, straightforward SPVs can open in 48 hours and complex ones in 7 to 10 days.
Stage | Bank | Our partner |
|---|---|---|
Preparing the file | 1 to 3 weeks | A few days, built with us |
Review and follow-up questions | Several weeks, longer with an administrator in the middle | 48 hours to 10 days |
Account open and ready | After every document and signature is in | 48 hours for simple SPVs, 7 to 10 days for complex ones |
What Slows It Down
The usual delays are a missing layer in the structure chart, a corporate shareholder whose own owners are not shown, a source of funds with no evidence, and a lender whose security terms arrive after the application. Every missing item restarts part of the review.
SPV Bank Account Timing Around a Deal
Deals run to a completion date, and banks do not. A property SPV that needs to pay a deposit or an acquisition SPV that needs to receive investor money cannot wait for a review to finish. Open the SPV bank account as soon as the vehicle is registered, before investors are asked to send money, and agree the lender's mandate at the same time.
How to Speed It Up
Build the structure chart and deal note first, collect every director's and owner's documents in one round, and agree the signatories and any lender control before you apply. Apply once, to a provider that takes your kind of SPV, rather than to several banks at the same time.
Interpolitan Money
Business account
Time to onboard
1 Week
Currency
EUR, USD, GBP, AED, and 50+
Monthly fee
Custom
What Happens After the Account Is Open
After the account opens, fund it, add the authorised users and set up the payments the deal needs. Keep the SPV's money apart from the group's: lawyers point out that separate bank accounts, separate decisions and separate financial statements all support an SPV being treated as legally separate if something goes wrong elsewhere.
Keep the file current, because providers review SPVs regularly. Tell the provider when an owner, director or lender changes. In the US, a final FinCEN rule effective 14 August 2026 exempts US-formed companies from beneficial ownership reporting, but banks still collect ownership information for their own checks. In Ireland, Section 110 companies must register with the Central Bank within five working days of their first financial transaction.
Rules on nominees and bearer shares are also tightening. From 10 July 2027, EU rules make nominee directors and shareholders disclose who nominated them, and existing bearer shares must be converted or immobilised by 10 July 2029. Take tax and legal advice on your own structure.
Why the SPV Comes Before the Account
A provider can only review an SPV that is properly formed: registered, with directors in place, registers filed and any administrator appointed where the law requires one. Each kind of SPV also has its own banking needs, and the table shows what reviewers look for.
SPV type | Common homes | What the reviewer looks for |
|---|---|---|
Property SPV | UK, Jersey, Guernsey | A property SIC code such as 68100, 68209 or 68320, and the lender's mandate |
Deal or syndicate SPV | Delaware, Luxembourg, France | The investor list and each investor's checks |
Holding SPV | BVI, Cayman, Jersey | A full structure chart and registered agent documents |
Fund SPV | Cayman, Luxembourg, Ireland | A custodian or depositary where the fund law requires one |
Securitisation SPV | Luxembourg, Ireland, Jersey | An account bank with the rating the deal documents require |
Formation costs vary widely. An ADGM SPV costs US$1,900 to register, and a non-exempt one must appoint an ADGM-registered company service provider, a Guernsey company costs £100 to incorporate and £525 a year when a service provider administers it, and UK buy-to-let lenders such as The Mortgage Works consider SPVs from day one but will not accept layered companies. Set up the structure first, then open the account with a complete file.
Common SPV Bank Account Mistakes
Most problems with a bank account for an SPV come from how the SPV is presented, not from the SPV itself. These are the mistakes we see most.
Registering the Wrong SIC Code
A property SPV registered under a trading code will not fit a buy-to-let lender, and the account has to match the company that borrows. Check the lender's accepted codes before you incorporate.
Layering Without a Reason
Every company between the SPV and its owners needs a reason. A layer that exists only because an adviser suggested it prompts the question reviewers ask most.
Leaving the Lender Out Until Completion
A lender that needs sole signing rights or a security acknowledgement should be part of the account from the start. Adding it days before completion can push the deal back.
Mixing SPV Money With the Group
Paying the parent's costs from the SPV account, or the SPV's costs from the parent, breaks the separation the SPV was built for and worries every reviewer.
Applying to Digital Banks That Exclude SPVs
An SPV that applies to a digital bank listing special purpose vehicles or holding companies as unsupported is refused by the eligibility rules.
Get Help With an SPV Bank Account
SPV banking is very manageable when the structure is planned with the bank in mind. Talk to us before the directors apply.
- Structure checked first: We confirm our partner can bank your SPV.
- Layered and offshore owners: Holding companies, funds and trusts handled.
- Refused before: We review the file and fix the gaps.
- Honest advice: We tell you when a lender's bank should sit alongside.
- One point of contact: From the first call to the first distribution.
Bottom Line
A bank account for an SPV is harder to open than most sponsors expect. Banks treat a vehicle with no staff, no history and corporate owners as a shell until proven otherwise, digital banks often exclude SPVs outright, and offshore banks take them mostly through administrators and charge for the complexity.
For SPVs with international owners or offshore registration, the faster route is a regulated partner built for complex structures. With a complete file, including the company documents, a structure chart, a deal note and a traced source of funds, opening a bank account for an SPV takes about a week, with no branch visit.
How do I open a bank account for an SPV?
Why is it hard to open an SPV bank account?
What documents do I need for an SPV bank account?
Can a new SPV with no trading history open a bank account?
Does Revolut or Starling open accounts for SPVs?
Can an offshore SPV open a bank account?
How long does it take to open a bank account for an SPV?
Can a property SPV get a bank account quickly?
Can the lender control the SPV bank account?
How much does an SPV bank account cost?
Can one account hold several currencies for an SPV?
Does each SPV need its own bank account?
Can an SPV keep a bank account and a partner account together?
Sources
- IMF: Final Report of the Task Force on Special Purpose Entities
- EBA: Guidelines on ML/TF risk factors
- HM Treasury: National Risk Assessment of Money Laundering and Terrorist Financing 2025
- ADGM: Special Purpose Vehicles
- FATF: Jurisdictions under increased monitoring, June 2026
- FinCEN: CDD Rule consolidated FAQs
- Federal Register: Beneficial ownership information reporting requirement revision
- Regulation (EU) 2024/1624 on anti-money laundering (EUR-Lex)
- GOV.UK: Companies House identity verification rollout
- FCA Financial Services Register: Interpolitan Money P.L.C.