A multi-currency account in the UAE lets your company hold AED, USD, EUR, GBP and more, pay suppliers in their own currency and stop converting every incoming payment. The dirham is pegged at 3.6725 to the US dollar, the UAE has no exchange controls, and companies pay 0% corporate tax on the first AED 375,000 of profit.
UAE banks make it harder than it should be. Most want a valid trade licence, a UAE-resident signatory with an Emirates ID and an average balance of AED 10,000 to AED 500,000, and many offer only two to four currencies. Miss the balance and a monthly fee of AED 100 to AED 1,050 follows, and a transfer abroad from a branch costs AED 70 to AED 105.
This is where we come in. We prepare the licence documents, ownership chart and source of funds file with you, and our licensed banking partners open a multi-currency account with dedicated IBANs in days, with no minimum balance and no resident signatory. One team, one contact.
Our top-rated, licensed banking providers open multi-currency accounts for UAE companies in days, with AED, USD, EUR and GBP from the start.
Moneygate
Business Banking
Monthly fee
€30
Onboarding fee
€500
Time to onboard
2-3 days
Features
Dedicated IBAN, SEPA, FX and more
3S Money
Cross-border payments
Time to onboard
4 Days
Account opening fee
Free
Monthly fee
Starting from € 100
Why a Multi-Currency Account in the UAE Is Hard
A multi-currency account in the UAE is hard to get because banks tie it to a full business relationship: a licence, a resident signatory, a minimum balance and a review of every owner. For a new company with foreign owners, each of those is a separate hurdle before a single currency is added.
Trade Licence and Resident Signatory First
UAE banks start with the company's paperwork. ADCB's September 2026 documentation list asks for a valid trade or commercial licence, the memorandum of association, a board resolution, passports for shareholders, signatories and beneficial owners, and Emirates ID copies for shareholders and signatories. Emirates NBD asks for passports with a UAE residency visa. A company whose owners live abroad often has no one who can sign, and the type of company changes the rest of the list.
Minimum Balances Lock Up Cash
Most UAE business accounts come with a minimum average balance. FAB's Business Basic account needs AED 10,000, RAKBANK's business current account AED 25,000, Emirates NBD's Proprietor and Prime packages AED 50,000 and Commercial Bank of Dubai's Essential package AED 100,000. Premium packages at several banks ask for AED 500,000 or more, money that sits idle to keep the account free. Our guide to minimum deposit requirements compares them across countries.
Open a Multi-Currency Business Account in the UAE
A multi-currency business account in the UAE is very doable with the right partner and a complete file. This is what we handle for you.
- No minimum balance: Keep your cash working instead of parked to avoid a fee.
- No resident signatory: Our partners open for owners who live abroad.
- Dozens of currencies: AED, USD, EUR, GBP and many more under one login.
- Dedicated IBANs: Including AE IBANs at one partner.
- Banks slow to onboard: An account in days, not after weeks of questions.
- KYC pack prepared: We build the file the partner asks for, upfront.
- One point of contact: No back-and-forth emails from start to finish.
Only a Few Currencies at Most Banks
Multi-currency at a UAE bank often means a short list. Dubai Islamic Bank offers its business current account in AED and USD. ADCB and RAKBANK offer AED, USD, EUR and GBP. Commercial Bank of Dubai offers six: AED, USD, GBP, EUR, JPY and CNY. A company that trades with suppliers in Turkey, India or Poland will not find its currencies on most of these lists.
The Three-Day Rule Has Conditions
The Central Bank of the UAE's SME Customer Protection Regulation, C 2/2026, took effect on 13 September 2026. Banks must complete account opening within three business days, but only for applicants assessed as low risk, and the clock only starts once every document is in. Where a delay is not about financial crime, the bank may issue an account number with limited transactions for up to two weeks.
The rule also says a rejection must be explained in writing, unless the reason relates to financial crime or the law bars disclosure, and that no closing fee applies after six months. It helps a clean local SME. A new company with foreign owners is rarely rated low risk on day one.
New AML Law and De-Risking
Federal Decree-Law No. 10 of 2025 replaced the UAE's 2018 anti-money laundering law from 14 October 2025, with fines of AED 5 million to AED 100 million for companies, and its executive regulations followed on 14 December 2025. The Central Bank's November 2025 guidance on correspondent banking warns that cutting off whole categories of relationships can lead to financial exclusion, but banks still decline files they cannot understand quickly.
Why Applications Get Rejected
Free zone authorities list the same reasons again and again: incomplete documents, an expired licence, a licence activity that does not match the business plan, transaction flows that do not match the activity, an unclear source of funds, complex ownership and no real substance. Trading, crypto and financial services are named as higher risk. Our guide to why banks reject business account applications covers each one.
What to Do After a Rejection
Ask for the written reason, which C 2/2026 now requires in most cases. Fix the specific gap, whether it is the licence activity, the ownership chart or the source of funds. Then apply once, to a provider whose rules fit your company, rather than sending the same file to three more banks.
UAE Banks for Multi-Currency Accounts
UAE banks for multi-currency accounts vary more on currencies and balances than on anything else. The table shows what each bank offers and what it charges when the balance falls short. Figures come from each bank's current schedule of charges.
Bank | Currencies | Minimum balance | Fee if the balance falls short |
|---|---|---|---|
Emirates NBD | A range of major currencies | AED 50,000 on Proprietor and Prime | AED 157.50 to AED 262.50 a month |
FAB | AED plus USD, GBP, JPY and EUR | AED 10,000 to AED 500,000 | AED 100 to AED 500 a month |
ADCB | AED, USD, EUR and GBP | AED 500,000 and up on Business First | AED 1,575 to AED 2,625 a month |
RAKBANK | AED, USD, EUR and GBP | AED 25,000, or 10,000 in USD, EUR or GBP | AED 52.50 a month plus AED 103.95 maintenance |
Dubai Islamic Bank | AED and USD | AED 50,000 to AED 500,000 | AED 525 to AED 630 a month |
Commercial Bank of Dubai | AED, USD, GBP, EUR, JPY and CNY | AED 100,000 to AED 3,000,000 | AED 367.50 to AED 1,050 a month |
HSBC UAE | Most major currencies | AED 20,000 | AED 150 a month plus AED 920 maintenance |
The table shows the trade-off. The banks with low minimums offer few currencies, and the banks with more currencies want larger balances. Digital accounts such as Wio Business and Mashreq NEO BIZ drop most minimum balances and add a few currencies, but they still need a valid UAE trade licence and are built for companies run from inside the UAE.
Balance Fees Every Month
A shortfall fee is charged every month the average balance dips. At Dubai Islamic Bank that is AED 525 to AED 630, and at Commercial Bank of Dubai AED 367.50 to AED 1,050. A company whose balance swings with supplier payments can pay these fees in half the months of the year without ever noticing the pattern.
Transfer Fees and Correspondent Charges
Online foreign currency transfers cost AED 21 to AED 52.50 at most banks, and branch or telex transfers AED 45 to AED 105. Correspondent banks then take their own cut. Emirates NBD adds AED 105 when you pay all charges on an AED transfer abroad, and HSBC UAE adds AED 50 to AED 100. At Commercial Bank of Dubai, a non-digital transfer on the Gold and Platinum packages costs AED 525.
Currency Conversion at the Bank's Rate
None of these banks publishes the margin it adds when converting currency on a transfer. HSBC UAE says the prevailing exchange rate applies, and card spending abroad carries 2% at Wio and 2.5% on non-AED transactions at Mashreq NEO BIZ. FAB charges 1% on foreign currency cash. On a company converting AED 2 million a year, a 1% hidden margin is AED 20,000.
Maintenance and Licence Penalties
Some packages charge a monthly fee on top of the balance rule: AED 920 per entity at HSBC UAE, AED 103.95 at RAKBANK below AED 250,000, and AED 275 to AED 800 for ADCB's Business First membership. If the trade licence expires, the penalties start: AED 210 a month at Wio, AED 300 at Mashreq NEO BIZ and AED 367.50 at RAKBANK, after short grace periods.
Read more: how to open a business bank account in the UAE and requirements to open a business bank account in the UAE.
Trumia
Business account
Monthly fees
€50
Onboarding fees
€500
Time to onboard
1 week
Accepts
Gambling, Betting, Casino, Crypto, and more
A Faster and Cheaper Way to Open a UAE Business Account
There is a better way to open a UAE business account with real multi-currency features. Our banking partners are licensed e-money institutions that onboard international companies every day. They open accounts online, with no minimum balance and no UAE-resident signatory, usually in days, and they offer far more currencies than most UAE banks.
One of our partners runs a branch in the DIFC regulated by the Dubai Financial Services Authority and issues dedicated AE IBANs, alongside UK, Luxembourg and Netherlands IBANs. Others are licensed by the Central Bank of Cyprus, the Malta Financial Services Authority and the FCA. Client money is safeguarded in segregated accounts at banks, apart from each partner's own funds.
Feature | UAE banks | Our partners |
|---|---|---|
Time to open | Three business days for low-risk complete files, longer for others | About 2 to 10 business days |
Resident signatory | Usually required, with Emirates ID | Not required |
Minimum balance | AED 10,000 to AED 500,000 at most banks | None |
Monthly cost | About AED 100 to AED 920, plus shortfall fees | Free to €100 a month |
Currencies | 2 to 6 at most banks | Up to 65+ at one partner |
IBANs | One AE IBAN per account | AE, EU and UK IBANs |
Currency conversion | Bank's own rate, margin not shown | One margin, shown before you confirm |
Visit | Branch meeting at most banks | None, identity checked online |
For a company that trades across borders, the partner route is faster, holds more currencies and frees up the cash a bank would lock in a minimum balance. A UAE bank still suits a company that needs cash deposits, a trade finance line or a local loan, and we say so when it applies.
How to Open a Multi-Currency Account in the UAE
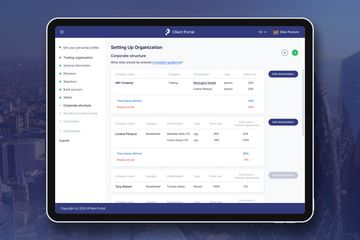
How to open a multi-currency account in the UAE with us takes five steps. First, we check your licence, activity, owners and currencies against each partner's rules. Second, we build the file: licence, memorandum, ownership chart, source of funds and expected payment flows by currency. Third, every director and owner completes an online identity check. Fourth, one partner reviews one complete file. Fifth, the account goes live with your IBANs.
Who Our Partners Accept
Our partners accept UAE free zone and mainland companies with real activity and a clear source of funds, including trading, e-commerce, software, logistics and holding companies. Offshore companies from RAK ICC or JAFZA are reviewed case by case, usually with a certificate of good standing. Companies linked to sanctioned countries are declined by every partner.
Best Multi-Currency Accounts in the UAE
The best multi-currency accounts in the UAE for a company that trades abroad are the ones that open without a resident signatory, hold the currencies you actually use and price conversion openly. These are the partners we work with, and who each one suits.
MoneyGate for High-Volume International Businesses
MoneyGate is an electronic money institution licensed by the Central Bank of Cyprus, with a branch in Greece and a passport to operate across the EU. It gives companies dedicated IBANs, SEPA, SWIFT and FX, accounts in EUR, GBP, USD, AED and CAD, physical and virtual cards, bulk payouts and an open API, with a named relationship manager from day one.
It suits UAE companies with high monthly volumes and complex payment flows: payment service providers, fintechs, marketplaces, shipping, e-commerce, investment firms and licensed gaming operators. It accepts UAE-incorporated companies and onboards remotely.
Moneygate
Business Banking
Monthly fee
€30
Onboarding fee
€500
Time to onboard
2-3 days
Features
Dedicated IBAN, SEPA, FX and more
3S Money for AE IBANs and 65+ Currencies
3S Money is licensed as an e-money institution by the FCA in the UK and the CSSF in Luxembourg, and runs a DIFC branch regulated by the DFSA. It covers more than 65 currencies and payments to more than 190 countries, with dedicated AE, GB, LU and NL IBANs. Its Standard plan costs €100 a month, and receiving payments from the EU, UK, US and UAE is free.
It suits UAE companies with up to five owners that pay and get paid across Europe, the Gulf and Asia, and it says most accounts are approved within 10 days. Gambling, FX services, adult businesses and shell companies are outside its rules.
3S Money
Cross-border payments
Time to onboard
4 Days
Account opening fee
Free
Monthly fee
Starting from € 100
Trumia for Multi-Currency IBANs in Europe
Trumia is a payment services provider and electronic money institution licensed by the Malta Financial Services Authority. Its corporate accounts cover 17 currencies, including AED, USD, EUR, GBP, CAD, SGD and HKD, with SEPA Instant payments that arrive in about 10 seconds for up to €100,000, SWIFT, an API and a Visa business card.
It suits companies that want a European account alongside their UAE setup, including groups with entities in several countries and businesses in sectors that local banks avoid. Plans start from €50 a month, and we confirm eligibility for your structure before you apply.
Trumia
Business account
Monthly fees
€50
Onboarding fees
€500
Time to onboard
1 week
Accepts
Gambling, Betting, Casino, Crypto, and more
Equals Money for UK and EU Group Companies
Equals Money offers a multi-currency business account with 35 or more currencies under a single set of account details, SWIFT, UK Faster Payments, SEPA and SEPA Instant. The account is provided by Equals Money PLC, authorised by the FCA as a payment institution, and by a Belgian entity supervised by the National Bank of Belgium for EU clients. AED can be held, sent and received.
It suits UK and EU companies inside a UAE group that need sterling, euros and dirhams side by side, and it says complete applications are usually processed within 24 hours. Plans are billed yearly, and we confirm which entity in your group fits best.
Read more: the best multi-currency business accounts and a business account for international payments.
Equals Money
Business Bank Account
Time to onboard
2 Days
Account opening fee
Free
Monthly fee
€30
Documents Needed for a Multi-Currency Account in the UAE
The documents needed for a multi-currency account in the UAE are the same whether you apply to a bank or to one of our partners. They cover the company, the people behind it and the business itself. Partners add one thing banks rarely ask for upfront: the currencies and countries you expect to use.
For the Company
Provide the valid trade licence, the memorandum and articles of association, the certificate of incorporation, the share register and a board resolution approving the account. Free zone companies add their free zone registration documents, and offshore companies add a certificate of good standing or incumbency no older than a year, which Mashreq's guidelines ask for.
For Each Director, Owner and Signatory
Every director, signatory, shareholder and beneficial owner provides a passport and proof of address. UAE banks usually add a residence visa and an Emirates ID for signatories. Our partners verify identity online with a passport and a selfie, so owners who live abroad do not need UAE residency documents to open the account.
For the Business
Provide an ownership chart with every level up to the beneficial owners, a business plan with expected turnover, contracts or invoices with key customers and suppliers, and a website. For a multi-currency account, list the currencies you will receive and pay, the countries involved and rough monthly volumes. Document the source of the first deposit with a sale agreement, dividend statement or loan contract.
Offshore and Holding Companies
A RAK ICC or JAFZA offshore company has no trade licence for activity inside the UAE, so the bank or partner looks harder at what it holds and where it trades. Add the group structure, the purpose of the company and financial statements for the entities it owns. Our guide to the best offshore business bank accounts in the UAE covers the offshore side in detail.
Read more: how to open a business bank account in Dubai and opening a free zone company bank account.
UAE Multi-Currency Account for Non-Residents
A UAE multi-currency account for non-residents opens quickly when the file is complete before the first review. We prepare it with you, including the documents needed for a multi-currency account in the UAE.
- No UAE residency needed: Owners and directors can live abroad.
- No Emirates ID required: Identity checked online with a passport and selfie.
- Currency plan written: Expected flows by currency, the way reviewers read them.
- Offshore files supported: Good standing and group documents prepared.
- One clean submission: No second round of questions from a half-finished file.
- Clear pricing: Every fee confirmed in writing before you apply.
Multi-Currency Account Costs in the UAE
Multi-currency account costs in the UAE are driven by the minimum balance, the shortfall fee and the currency margin more than by the advertised monthly fee. The table sets typical ranges at UAE banks against our partners' plans.
Charge | Typical range at a UAE bank | With our partners |
|---|---|---|
Minimum average balance | AED 10,000 to AED 500,000 | None |
Fee if the balance falls short | AED 100 to AED 1,050 a month | None |
Monthly maintenance or package fee | About AED 100 to AED 920 a month | Free to €100 a month |
Opening fee | Usually none | Free to €500 |
Currencies available | 2 to 6 at most banks | Up to 65+ at one partner |
Transfer abroad online | AED 21 to AED 52.50 plus correspondent charges | From €2 on SEPA, around €25 to €30 on SWIFT |
Transfer abroad at a branch | AED 70 to AED 105, AED 525 at one bank | Always online, same price |
Paying all correspondent fees | AED 50 to AED 105 extra | Shown before you send |
Currency conversion | Bank's own rate, margin not shown | One margin, shown before you confirm |
Expired licence penalty | AED 210 to AED 367.50 a month | Account reviewed, no monthly penalty |
Account closure | Up to AED 100 in the first six months, free after | Up to €200 |
The monthly fee is the number banks advertise, and it is rarely the real cost. A company keeping AED 100,000 idle to meet a minimum balance gives up whatever that cash could earn or buy, and one that misses the balance pays AED 367.50 to AED 1,050 a month at some banks. Add an unpublished conversion margin on every foreign currency payment, and the account costs far more than its package fee.
To be fair, online transfers abroad are cheap at UAE banks, often cheaper per payment than a SWIFT transfer through a partner. The saving with our partners is in the balance you no longer park, the currencies you no longer convert and the fees that no longer apply. All figures are planning ranges from published schedules, and we confirm your final price in writing before you apply.
Moneygate
Business Banking
Monthly fee
€30
Onboarding fee
€500
Time to onboard
2-3 days
Features
Dedicated IBAN, SEPA, FX and more
Trumia
Business account
Monthly fees
€50
Onboarding fees
€500
Time to onboard
1 week
Accepts
Gambling, Betting, Casino, Crypto, and more
How Long a UAE Multi-Currency Account Takes
Under C 2/2026, a low-risk SME with a complete file should have its account within three business days. In practice, a new company with foreign owners, a free zone licence or several currencies is rarely rated low risk on day one, so the review takes longer. With our partners, a complete file usually opens within 2 to 10 business days.
Stage | UAE bank | Our partners |
|---|---|---|
Preparing the file | 1 to 2 weeks, including visas and Emirates IDs | A few days, built with us |
Branch meeting | Several days to arrange | Not needed |
Review | Three business days if low risk, longer otherwise | A few days |
Adding currencies | Separate requests after opening | Included from the start |
What Slows It Down
The usual delays are a signatory without a residence visa or Emirates ID, a licence activity that does not match the business plan, an ownership chart that stops short of the beneficial owners and a source of funds without documents. Adding currencies after opening can mean another request and another review.
How to Speed It Up
Anyone working out how to open a multi-currency account in the UAE from abroad should start with the licence. Match the licence activity to what the company really does before you apply. Prepare the ownership chart, contracts and source of funds documents upfront, and list the currencies and countries you will use. For a company run from abroad, the fastest route is a partner that does not need a resident signatory at all.
What Happens After the Account Is Open
Once the account is open, fund it, add users and share the right IBAN with each customer and supplier. After that, three things keep the account healthy.
Corporate Tax and VAT
UAE corporate tax is 0% on taxable income up to AED 375,000 and 9% above, under Federal Decree-Law No. 47 of 2022. A Qualifying Free Zone Person pays 0% on qualifying income, as long as non-qualifying revenue stays below the lower of AED 5 million or 5% of total revenue. VAT is 5%, with registration mandatory above AED 375,000 a year. Keep the account records ready for both.
Keep the Trade Licence Current
Banks and partners check that the trade licence is valid at every review. An expired licence triggers monthly penalties at several banks and can restrict payments until it is renewed. Put the renewal date in the calendar the day the licence is issued, and send the renewed licence to the provider straight away.
Reviews and Protection of Funds
Expect a file review every year or two, with fresh documents for owners and activity. The UAE does not run an EU-style deposit guarantee with a published coverage limit, so it is worth knowing how each provider protects your money. Our partners safeguard client funds in segregated accounts at banks, apart from their own funds.
Why the Company Comes Before the Account
A bank or partner can only open an account for a company that exists, with a trade licence, a memorandum and registered shareholders. If you do not have the company yet, we form it for you in the UAE, whether in a free zone such as IFZA or DMCC or on the mainland, and prepare the bank file at the same time.
Read more: the cost of business setup in the UAE.
UAE Company Incorporation
Binderr
Corporate tax
0% up to AED 375,000
Freezone Tax
0%
Time to Incorporate
1 Week
Cost
Starting from €1,899
Common Multi-Currency Account Mistakes in the UAE
Most problems with multi-currency banking in the UAE come from choosing the account for the wrong reasons. These are the mistakes we see most, and what to do instead.
Choosing a Bank for Its Name, Not Its Currencies
A well-known bank can still be the wrong one. Dubai Islamic Bank offers its business current account in AED and USD only, and several banks stop at four currencies. If you pay suppliers in Turkish lira or Indian rupees, you will convert every payment at the bank's rate. List your currencies first, then pick the account that holds them.
Parking Cash to Meet a Minimum Balance
Some companies keep AED 100,000 or more sitting in an account only to avoid a shortfall fee. That money earns little and cannot fund stock, salaries or growth. If your balance swings with supplier payments, you may pay the shortfall fee anyway in the months it dips. Choose an account with no minimum balance if your cash moves a lot.
Letting the Trade Licence Expire
A lapsed licence costs AED 210 to AED 367.50 a month in penalties at several banks and can freeze outgoing payments until it is renewed. It also becomes a question at the next review. Renew a month early, and send the new licence to your bank or partner as soon as it is issued.
Opening Without a Signatory Plan
Many founders form a UAE company from abroad and only then learn the bank wants a UAE-resident signatory with an Emirates ID. Getting a visa and ID takes weeks and costs money. Decide early whether you will have a resident signatory, or use a provider that does not need one, before the company is formed.
Converting Everything to AED
Receiving dollars or euros into an AED account converts every payment at the bank's rate, and paying suppliers back in their own currency converts it again. That is two margins on the same money. Hold each currency in its own balance, convert only when you need to, and check the rate before you confirm.
Advice on a Multi-Currency Business Account in the UAE
Multi-currency banking in the UAE is very manageable when the provider and the file are chosen together. Talk to us before you apply.
- Currencies mapped: We match your payment flows to the right provider.
- Refused before: We review the old file and fix what failed.
- Offshore or free zone: Structures explained the way reviewers need.
- Regulated sectors: Partners that accept some licensed high-risk businesses.
- Honest advice: We tell you when a UAE bank is the better fit.
Bottom Line
A multi-currency business account in the UAE saves money on every cross-border payment, but UAE banks make it slow and costly to get: a trade licence, a resident signatory, minimum balances of AED 10,000 to AED 500,000, a short list of currencies and conversion margins you cannot see. The three-day rule helps only low-risk companies with complete files.
Our licensed partners open a multi-currency account online in days, with no minimum balance, no resident signatory, dedicated IBANs and dozens of currencies. Prepare a complete file, list your currencies and apply once. You can add a UAE bank later if you need cash services or local credit.
What is a multi-currency account in the UAE?
Which UAE banks offer multi-currency business accounts?
Can non-residents open a multi-currency account in the UAE?
What is the minimum balance for a multi-currency business account in the UAE?
How much does a multi-currency account in the UAE cost?
Can I open a business bank account in UAE in three days?
What documents are needed to open a multi-currency account in the UAE?
What is the best multi-currency account in the UAE?
Can offshore companies open a multi-currency account in the UAE?
Do I get a UAE IBAN with a multi-currency account?
Is money in a UAE business account protected?
Do I need to convert foreign currency into AED?
How do I open a UAE business account from abroad?
Sources
- Central Bank of the UAE, SME Customer Protection Regulation C 2/2026
- UAE legislation, Federal Decree-Law No. 10 of 2025 on anti-money laundering
- Central Bank of the UAE, IBAN standard
- Central Bank of the UAE, Dirham monetary framework
- UAE government portal, corporate tax
- Federal Tax Authority, Qualifying Free Zone Person guide
- Emirates NBD, business banking schedule of charges
- FAB, business banking fees and charges
- HSBC UAE, corporate tariff and charges, October 2026
- Commercial Bank of Dubai, business accounts schedule of charges
- FATF, outcomes of the February 2024 plenary