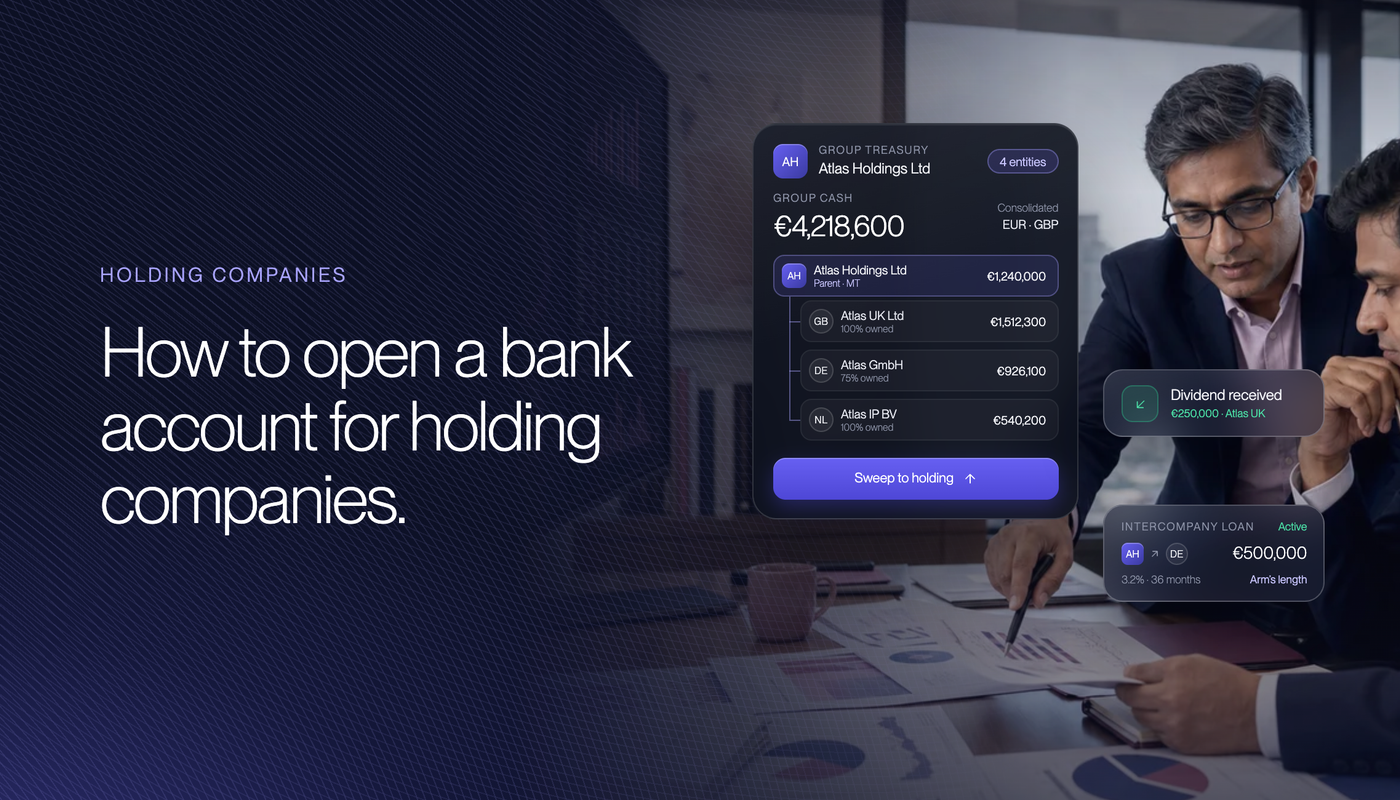
A bank account for holding companies does a different job from a trading account. Dividends come up from the subsidiaries, loans go down to them, acquisitions are paid for and cash is held in one place for the whole group. The right account keeps the holding company's money apart from the trading companies below it, works in several currencies and lets the group move money between entities without delay.
The hard part is the bank. Banking for holding companies is harder than for trading businesses because a holding company has no customers, little turnover and often owners who are companies themselves. Starling turns away holding companies, Metro Bank and Mettle want only individual owners, and a group with an offshore parent can wait weeks for a review.
You do not need to do that alone. We prepare the group's file, from the structure chart to the source of funds, and place it with our regulated banking partner, which specialises in complex structures and opens multi-currency accounts in about a week.
Our top-rated, licensed banking provider for complex structures opens multi-currency accounts for holding companies in about a week, with no branch visit and owners in most countries.
Interpolitan Money
Business account
Time to onboard
1 Week
Currency
EUR, USD, GBP, AED, and 50+
Monthly fee
Custom
Why Banking for Holding Companies Is Hard
Banking for holding companies is hard because the bank's usual checks are built for businesses that trade. A holding company owns shares, receives dividends and lends to its subsidiaries, so it has little turnover, few invoices and no customers to show. Its owners are often other companies, trusts or investors in several countries. The bank has to trace every layer back to people, understand where the money comes from and decide whether the whole group fits its appetite.
A Holding Company Has No Trading Story
UK company law defines a holding company by control: it holds a majority of the voting rights in another company, or can appoint or remove a majority of its board. That is all it does. Monzo Business wants a company that makes money "mostly from selling goods and/or providing services, not mostly from interest or investment income", which a pure holding company fails. Allica's business account is for companies "incorporated for a minimum of 12 months" with £50,000 to keep on deposit. A new parent company meets neither test.
Corporate Owners Break Simple Eligibility Rules
Many business accounts are built for companies owned by individuals. Starling says the business must not be "a holding company" and that all persons of significant control must be individuals. Metro Bank's business account requires that "Your business must be owned only by individuals and not a parent company." Mettle says "all PSCs must be individuals", and Zempler cannot accept "businesses with multiple corporate PSCs". So the rules shut out the holding company and, often, the subsidiaries it owns as well.
Open a Bank Account for Your Holding Company
A bank account for holding companies is very achievable when the structure is explained before the bank asks. This is what we do for you.
- Complex structure specialists: Our partner builds its accounts for layered and international groups.
- Corporate and non-resident owners welcome: Layered ownership accepted with a clear chart.
- Banks slow to onboard: An account in about a week, not months of back and forth.
- Dividends in 50+ currencies: EUR, USD, GBP, AED and more in one account.
- Structure chart and source of funds: Written the way reviewers want to read them.
- Clear pricing, no surprises: One quote before we start.
Every Layer Has to Be Traced
The bank must find the people who own or control more than 25% of the company, and with a holding company that means looking through each layer. Mercury gives a worked example: a holding company owns 50% of your business and two people each own 50% of the holding company, so each has "25% passthrough ownership" and both must be listed. From 10 July 2027, EU rules will calculate indirect ownership "by multiplying" the stakes held along each chain of companies, and add separate chains together.
Complex Structures Need a Reason
UK anti-money laundering guidance says "The use of complex structures without an obvious legitimate commercial purpose may, however, give rise to concern." A listed parent can qualify for lighter checks, because its shares trade on a regulated market. A private group with several layers and an offshore parent can be treated as higher risk, especially where the structure looks unusual or excessively complex for its business. HSBC in the Channel Islands and Isle of Man turns away businesses "owned or controlled by a nominee company, group structure, institution, or offshore holding structure."
Why Holding Company Bank Accounts Get Refused
The Dutch central bank found that financial holding companies were the sector with the most anti-money laundering exits at the four largest Dutch banks in 2021, with 374 relationships ended. Tide will not serve businesses that "have a shell company in their corporate structure." A parent with no staff, no office and money arriving from abroad can look like a shell to a reviewer, even when it is doing exactly what a holding company should. Banks rarely explain a refusal, so the file has to be right the first time.
Read more: Why banks reject business account applications and how to open a bank account for an SPV.
Banks That Open Holding Company Accounts
Plenty of banks will take a holding company in principle, but most have a rule that shuts out a large share of groups. The table shows what the main options publish.
Bank | Who it takes | Who it turns away | Monthly fee or minimum |
|---|---|---|---|
HSBC UK | UK tax resident companies, with a small business account for newer ones | Companies that are not UK tax resident | No monthly fee on the Small Business account |
Barclays | Established UK businesses, with a start-up route for new ones | Companies without 12 months of trading on the established route | Free for 12 months, then £8.50 a month |
Lloyds | UK businesses that can show activity and expected turnover | Applicants that cannot show UK residence | Free for 12 months, then £10 a month |
Metro Bank | Companies owned by individuals, with half the shares held in the UK | Companies owned by a parent company | Free above a £6,000 daily balance, otherwise £8 a month |
Starling | UK companies owned by UK-resident individuals | Holding companies and any corporate shareholder | Plan based |
Zempler Bank | Companies with one corporate shareholder, at extra cost | Companies with more than one corporate PSC | £100 extra on opening with a corporate owner |
Coutts | Private clients bringing £3 million or more | Businesses registered outside the UK | Relationship based |
Channel Islands banks | Groups introduced by fiduciaries and trust companies | Structures that fail enhanced checks | Relationship based, plus yearly risk charges |
Digital banks are not an answer for every group. Revolut Business does not name holding companies, but it lists special purpose vehicles as unsupported. Wise allows one account per business and restricts companies with bearer shares, and Airwallex needs each entity to onboard separately. Choosing a bank for a holding company comes down to where it is registered, who owns it and what it will receive.
UK Banks Want UK Owners
The UK government tells overseas owners that opening a business account "can take 4 weeks to 3 months" and that banks usually want identification for "all shareholders with over 10% of the business". Metro Bank asks for at least 50% of the shares to be held by UK residents and at least half the directors to live in the UK, and sends everyone else to its Inward Investment team. A UK holding company owned from Dubai or Singapore runs into these residency rules at most high street banks.
Group Tools Are Rare
A holding company needs to see and move money across the group. Wise lets you hold accounts for several businesses under one login, but each business needs its own account. Airwallex offers a group view through a sales-led product, with each entity onboarded separately. At most high street banks, each subsidiary opens its own account through its own application, and the holding company waits its turn like any other customer.
Offshore Parents Need an Intermediary
Banks in Jersey, Guernsey and the Isle of Man take holding companies mostly through licensed trust companies and fiduciaries. Barclays charges fiduciaries a £500 yearly intermediary fee. Coutts will not offer commercial banking to businesses registered outside the UK at all. An offshore parent without an administrator it trusts struggles to get in the door.
Risk Charges on Structure Files
Offshore banks price complexity into the account. In the Channel Islands, Butterfield charges £2,500 a year for a high-risk account and £4,500 where a politically exposed person is involved. Barclays charges from £2,500 a year for high risk and from £5,000 for a PEP, and Lloyds may add up to £10,000 a year per entity for enhanced due diligence. A group with several entities can pay these charges on each entity's account.
Read more: Business bank account vs EMI account and best countries for business banking.
Interpolitan Money
Business account
Time to onboard
1 Week
Currency
EUR, USD, GBP, AED, and 50+
Monthly fee
Custom
A Faster Way to Open a Bank Account for Holding Companies
There is a better alternative to the bank queue. Our partner, Interpolitan Money, is an electronic money institution authorised by the UK Financial Conduct Authority, with a Dubai International Financial Centre entity licensed by the DFSA. It offers FCA-regulated multi-currency accounts for corporations, trusts, funds, SPVs and non-resident businesses, and describes layered ownership and non-resident shareholders as features rather than red flags. In one published client story, an international group that "couldn't find a global bank that could handle complex shareholding structures" opened accounts for its various entities within two weeks.
Each company in the group gets a multi-currency account holding 50+ currencies, with a unique IBAN or account number for each currency. Payments run over SWIFT, SEPA, SEPA Instant, Faster Payments, BACS and CHAPS, and batch payments pay several recipients in one go. Currency can be exchanged at spot, fixed ahead with a forward or set with a limit order, which helps when dividends arrive in one currency and loans go out in another. Every client gets a named relationship manager. Interpolitan says straightforward structures open in as little as 48 hours and most complex applications in 7 to 10 days.
We prepare the file before the partner sees it: the company documents, the registers, a structure chart up to the people at the top, identity documents and a written source of funds. Client money is held in segregated safeguarding accounts at major banks, separate from the partner's own funds. Be clear about what the account does: it receives, holds, converts and pays money. It does not offer loans, pay interest or hold securities, and it is not covered by the UK deposit guarantee scheme.
Feature | Banks | Our partner |
|---|---|---|
Time to open | 4 weeks to 3 months for overseas owners in the UK | 48 hours to 10 days |
Corporate shareholders | Refused at Starling, Metro Bank and Mettle | Layered ownership accepted with a clear chart |
Owner residency | UK owners and directors at many banks | Non-resident owners accepted, outside restricted countries |
Minimum balance or deposit | £6,000 to avoid fees at Metro Bank, £50,000 at Allica | No minimum balance on non-resident accounts |
Monthly cost | £0 to £10 at UK high street banks, up to £20 offshore, or relationship based | Custom, set for the structure |
Currencies | Separate currency accounts, often with extra fees | 50+ currencies in one account |
International payments | £13 to £92 each at offshore banks | £5 to £15 each |
Lending and custody | Available at banks | Not offered, funds safeguarded instead |
For a holding company that needs to receive dividends, fund subsidiaries and hold several currencies, our partner is faster and simpler. A bank still suits a group that needs a loan or an overdraft, and the two can sit side by side.
Which Holding Companies Our Partner Accepts
Our partner works with complex structures and treats offshore incorporation, layered ownership and non-resident shareholders as features rather than red flags. We prepare groups whose holding company owns trading subsidiaries, property companies, shares in a family business or an investment portfolio, including structures with trusts or foundations above them, and we check the fit before anyone applies. What it will not take is a structure that hides who is behind it, money with no clear source, sanctioned links or payments to restricted countries and industries.
Opening a Bank Account for Holding Companies Online
Opening a bank account for holding companies online works in four steps. We build the file with you, the directors and owners verify their identity and sign the application, the partner's compliance team reviews the structure and asks any questions through us, and the account goes live with its IBANs and account numbers. No director has to visit a branch, and further group companies can follow once the first is open.
Interpolitan Money
Business account
Time to onboard
1 Week
Currency
EUR, USD, GBP, AED, and 50+
Monthly fee
Custom
Documents for a Holding Company Bank Account
The documents for a bank account for holding companies cover the company, every layer above it and the subsidiaries below. We gather them with you and write the parts reviewers care about most.
Company Documents and Registers
Start with the certificate of incorporation, the articles or other constitution, a certificate of good standing and the registers of directors and shareholders. Since 18 November 2025, UK companies no longer keep their own registers of directors or people with significant control, because that information now sits with Companies House. They must still keep a register of members. An offshore parent adds a certificate of incumbency from its registered agent, and HSBC in Hong Kong asks for a company search, company particulars or certificate of incumbency, issued within six months, for each corporate owner in the chain.
The Group Structure Chart
Show every company from the holding company up to the people at the top, and down to each subsidiary. HSBC in Hong Kong asks for each intermediate owner's name, ownership and voting percentage, country of incorporation and country of business address. Airwallex may ask for a signed diagram on company letterhead, dated within six months, showing the registration country and ownership percentage of each intermediate shareholder. A clear chart answers most of the questions a reviewer would otherwise send.
Director and Owner Identity
Every director, signatory and beneficial owner provides a certified passport and a recent proof of address. Our partner's guidance asks for proof of address dated within the last three months and does not accept mobile phone bills. In the UK, directors and people with significant control must also verify their identity with Companies House, a rule phased in from 18 November 2025.
Subsidiary Information
Name each subsidiary, its country, what it does and how money moves between it and the parent: dividends up, loans down, management fees across. Add the latest accounts for the main subsidiaries if you have them. Reviewers want to see that the flows in the holding company's account match a real group.
Source of Funds and Tax Forms
Show where the holding company's capital came from, such as the owners' own funds, the sale of a business or dividends already paid up the group. Add the CRS self-certification for the company and its controlling persons, and the W-9 or W-8BEN-E that documents its US tax status under FATCA.
Read more: Documents needed to open a business bank account and business bank account requirements.
Prepare Your Holding Company Bank Account File
A holding company account opens fastest when the whole group fits on one page and the money is traced. We prepare it with you.
- Group chart signed: Every layer up and every subsidiary down.
- Flows explained: Dividends, loans and fees across the group.
- Company pack: Incorporation, constitution, registers and good standing.
- Owner files ready: Identity, address and source of funds for each owner.
- Tax forms ready: CRS self-certification and the right US form.
Holding Company Bank Account Costs
A bank account for holding companies looks cheap at a UK high street bank and grows expensive once the parent is offshore or the owners live abroad. The real cost is in minimum balances, risk charges and payments. The table sets typical ranges at banks against our partner's published pricing.
Charge | Typical range at a bank | With our partner |
|---|---|---|
Account opening | Free at most UK banks, £100 extra with a corporate owner at Zempler, £250 to £500 at some offshore banks | Set in your fee schedule before you sign |
Monthly or maintenance fee | £0 to £10 a month at UK banks after any free period | Custom, set for the structure |
Minimum deposit or balance | £6,000 to £50,000 at some banks | No minimum balance on non-resident accounts |
Yearly high-risk charge | From £2,500 at some offshore banks | None published |
Yearly charge where a PEP is involved | From £4,500 | None published |
Enhanced due diligence fee | Up to £10,000 a year per entity | None published |
Payment out in EUR or GBP | £13 to £92 at offshore banks | £5 |
Payment out in USD | £13 to £92 | £10 |
Payment out in AED and other currencies | £13 or more, plus correspondent fees | £15 |
Urgent payment | Varies by bank | £10 extra |
Payment instructed by phone or email | £20 to £92 manual fee | £40 |
Additional currencies | Separate currency accounts, often with extra fees | 50+ currencies in one account |
For an international group, the biggest cost is usually the complexity charge. A holding company with a politically exposed owner and two offshore subsidiaries can face £4,500 or more a year in risk charges on each account at a Channel Islands bank before a single payment is made. Currency adds more: a 2% margin on €1 million of dividends and intra-group loans a year costs €20,000. A UK high street bank with no monthly fee can be the cheaper choice for a small UK group with UK owners, and it is fair to say so. All figures are planning ranges drawn from published tariffs, and we confirm your final price in writing before you apply.
Interpolitan Money
Business account
Time to onboard
1 Week
Currency
EUR, USD, GBP, AED, and 50+
Monthly fee
Custom
How Long Holding Company Bank Account Opening Takes
Opening a bank account for holding companies takes weeks at most banks and longer when the owners live abroad. The UK government puts it at 4 weeks to 3 months for overseas-owned businesses, allowing for meetings and approval. With our partner, straightforward structures can open in 48 hours and complex ones in 7 to 10 days.
Stage | Bank | Our partner |
|---|---|---|
Preparing the file | 1 to 3 weeks | A few days, built with us |
Review and follow-up questions | Weeks, longer with offshore owners | 48 hours to 10 days |
Account open and ready | 4 weeks to 3 months in total for overseas owners | 48 hours for simple structures, 7 to 10 days for complex ones |
What Slows It Down
The usual delays are a missing layer in the structure chart, a corporate owner whose own owners are not shown, a source of funds with no evidence, and a director who cannot verify their identity in time. Every missing item restarts part of the review.
Holding Company Accounts for Groups With Several Entities
A group that needs accounts for the parent and three subsidiaries can face four separate reviews at a bank, each with its own questions. With one complete group file, the same documents answer each entity's review. In our partner's published client story, a group opened accounts for its various entities within two weeks.
How to Speed It Up
Build the structure chart and source of funds first, collect every director's and owner's documents in one round, and agree the signatories before you apply. Apply once, to a provider that takes your kind of group, rather than to several banks at the same time.
Interpolitan Money
Business account
Time to onboard
1 Week
Currency
EUR, USD, GBP, AED, and 50+
Monthly fee
Custom
What Happens After the Account Is Open
After the account opens, fund it, add the authorised users and set up the payments the group needs: dividends in, loans out and fees across. Record each intra-group payment with a board decision or loan agreement, so the flows in the account match the group's books.
Keep the file current, because providers review groups regularly. Tell the provider when an owner, director or subsidiary changes, and update Companies House within the time the law allows. In the UK, dividends a holding company receives from its subsidiaries are usually exempt from corporation tax, and a gain on selling a subsidiary can be exempt under the substantial shareholding exemption when the parent has held at least 10% for 12 months and other conditions are met. Take tax advice on your own group.
Rules on ownership are also tightening. From 10 July 2027, EU rules require banks to calculate indirect ownership across every layer of the group, so a chart that stops at the first corporate owner will not be enough.
Why the Structure Comes Before the Account
A provider can only review a holding company that is properly formed: registered, with directors in place, shares issued and the subsidiaries on their registers. Where the parent sits also shapes how the group is taxed and banked. The Netherlands exempts dividends and gains from holdings of at least 5% under its participation exemption when its conditions are met, Cyprus exempts dividends from other Cyprus tax resident companies subject to anti-avoidance rules, and Malta offers a participation exemption subject to conditions. Set up the structure first, then open the account with a complete file.
Common Holding Company Bank Account Mistakes
Most problems with a bank account for holding companies come from how the group is presented, not from the group itself. These are the mistakes we see most.
Stopping the Chart at the First Company
A chart that shows the holding company but not who owns it leaves the reviewer to find out, and the review stalls until they do.
Applying to Banks That Exclude Corporate Owners
A holding company, or a subsidiary owned by one, that applies to a bank requiring individual owners is refused by the eligibility rules.
Calling the Company Dormant
A holding company that receives dividends has investment income, and GOV.UK treats it as active for Corporation Tax. Describe it as a holding company, not a dormant one.
Mixing Group Money
Paying a subsidiary's costs from the parent's account, or personal costs from either, breaks the paper trail and worries every reviewer.
Opening Each Entity at a Different Bank
Spreading the group across banks with different rules multiplies the reviews and the documents. Plan one provider for the core entities where you can.
Get Help With a Holding Company Bank Account
Holding company banking is very manageable when the group is planned with the bank in mind. Talk to us before the directors apply.
- Structure checked first: We confirm our partner can bank your group.
- Layered and offshore owners: Parents, trusts and foundations handled.
- Refused before: We review the file and fix the gaps.
- Honest advice: We tell you when a high street bank should sit alongside.
- One point of contact: From the first call to the first dividend.
Bottom Line
Banking for holding companies is harder than most owners expect. Banks built for trading businesses turn away parents with no turnover, several refuse any corporate owner, UK banks want UK shareholders and directors, and offshore banks take groups mostly through intermediaries and charge for the complexity.
For groups with international owners or an offshore parent, the faster route is a regulated partner built for complex structures. With a complete file, including the company documents, a group chart and a traced source of funds, a bank account for holding companies takes about a week, with no branch visit.
How do I open a bank account for a holding company?
Why is it hard to open a bank account for holding companies?
Which banks accept holding companies?
Can a subsidiary owned by a holding company open a bank account?
What documents does a holding company need to open a bank account?
How long does it take to open a holding company bank account?
Can an offshore holding company open a bank account?
Is a holding company dormant if it only receives dividends?
How much does a bank account for holding companies cost?
Can a holding company hold several currencies in one account?
Does each company in a group need its own bank account?
Do banks need to see every owner of a holding company?
Can a holding company keep a bank account and a partner account together?
Sources
- Companies Act 2006, section 1159: meaning of subsidiary and holding company
- HMRC International Manual, INTM652010: dividend exemption for small companies
- HMRC Capital Gains Manual, CG53070: substantial shareholding exemption
- GOV.UK: Dormant companies and associations
- GOV.UK: Changes to company registers from 18 November 2025
- UK government: Business bank accounts in the UK
- The Money Laundering Regulations 2017, regulation 37
- De Nederlandsche Bank: From recovery to balance
- FCA Financial Services Register: Interpolitan Money P.L.C.