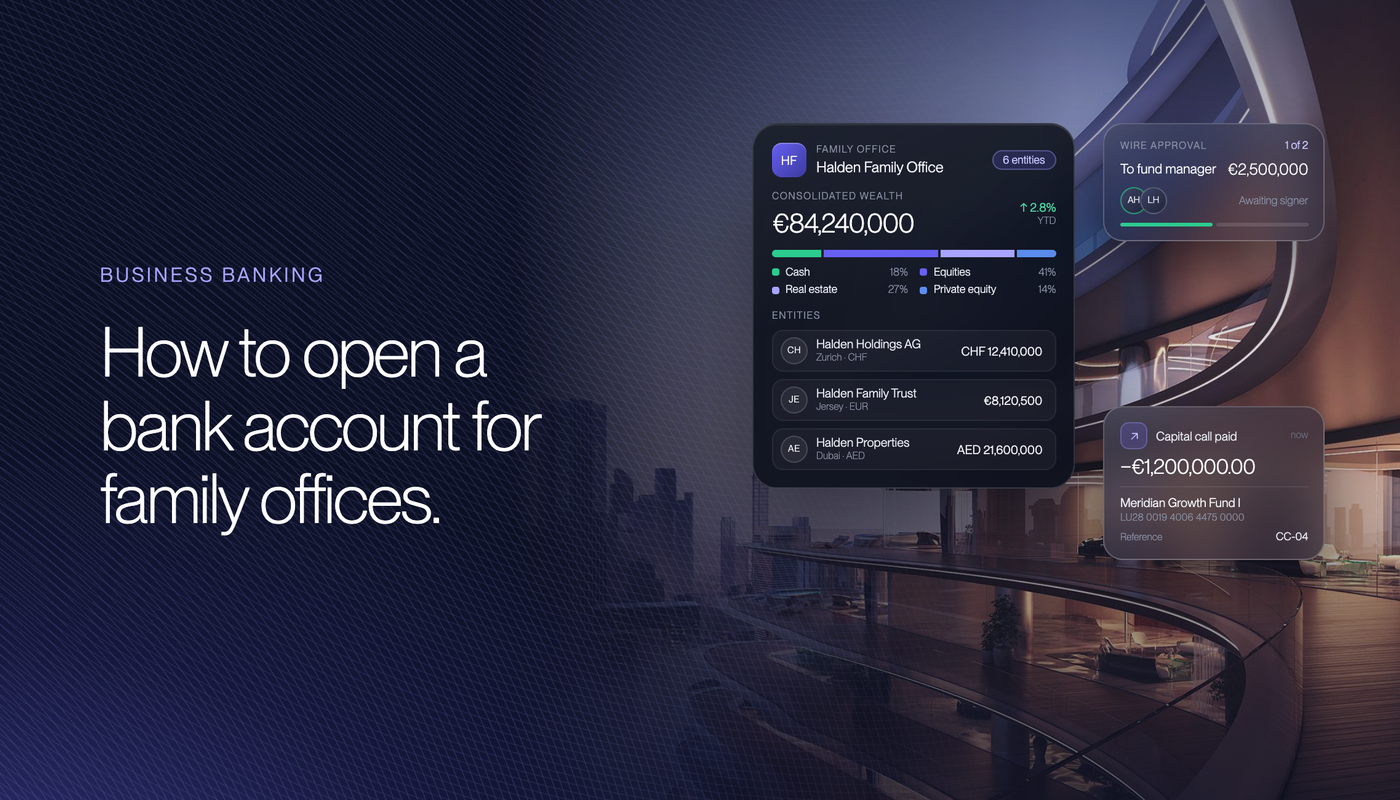
A bank account for family offices is where the family's day-to-day money runs. Investment income arrives, staff and advisers are paid, capital goes out to deals and cash moves between its companies, trusts and foundations. The right account keeps each entity's money apart, works in several currencies and sits alongside the private bank that holds the investments.
The hard part is the bank. A family office is a web of entities across countries, owned through trusts or holding companies, with wealth the bank must trace. Citi's family office services start at $100 million in assets, private banks at £1.5 million to £5 million, and Singapore account opening was said to take three to four months after its 2023 money laundering case.
You do not need to do that alone. We prepare the family office file, from the structure chart to the family's source of wealth, and place it with our regulated banking partner, which specialises in family offices and complex structures and opens multi-currency accounts in about a week.
Our top-rated, licensed banking provider for complex structures opens multi-currency accounts for family offices in about a week, with no branch visit and families in most countries.
Interpolitan Money
Business account
Time to onboard
1 Week
Currency
EUR, USD, GBP, AED, and 50+
Monthly fee
Custom
Why Banking for Family Offices Is Hard
Banking for family offices is hard because a family office is rarely one company. It is a management company sitting on top of holding companies, trusts, foundations and investment vehicles, often in three or four countries, all owned by one family. The bank has to understand every entity, trace the family's wealth back to where it was made and be sure the office serves one family and no one else.
A Family Office Sits on Top of Many Entities
BNY's guide lists the legal forms as a mix of "LLC, FLP, PTC, purpose trust, non-charitable foundation, etc.", and a family investment company or private trust company often sits in the middle. Citi's guide to setting up a family office mentions "several hundred bank accounts that need to be reconciled periodically" as a cost issue in its own right. Each entity needs its own account, and each account needs its own review.
Private Banks Want Assets First
Private banks serve family offices, but on their terms. Citi says "Our family office services are only available to single family offices with over $100 million in AUM." Barclays Private Bank serves clients "who can establish an investment portfolio of at least £3 million" in the UK, or £5 million elsewhere. HSBC's private bank in the Channel Islands and Isle of Man starts at £1.5 million in assets. The bank earns its fees on the investments, so a family office that mainly needs to pay staff and move money is not the client these banks are built around.
Open a Bank Account for Your Family Office
A bank account for family offices is very achievable when the structure is explained before the bank asks. This is what we do for you.
- Family office specialists: Our partner builds its accounts for family offices and complex structures.
- Every family entity: Management company, holding companies, trusts and foundations.
- Banks slow to onboard: An account in about a week, not months of back and forth.
- Payments in 50+ currencies: EUR, USD, GBP, AED and more in one account.
- Structure chart and source of wealth: Written the way reviewers want to read them.
- Clear pricing, no surprises: One quote before we start.
Source of Wealth Is Checked in Depth
Singapore's industry best practice papers, issued in May 2025 by a partnership led by the Monetary Authority of Singapore, name family offices among the clients that may need full source of wealth due diligence. The wealth management paper describes a single family office case where clients "had no public profile, seeking to open accounts based on a SoW which is only supported by documents provided by the client". The source of wealth paper adds that "merely obtaining documents is not the end of a SoW process." A family office file has to show how the wealth was made, with evidence the bank can check.
One Family, Not Several
A single family office manages one family's money, and banks check that it stays that way. The wealth management paper warns of the "Risk of co-mingling assets of multiple parties under the guise of a single family" and tells banks to make clear that "3rd-party funding is not expected." In the US, the SEC's family office rule applies only to an office that "Has no clients other than family clients" and is wholly owned and controlled by the family. Money from a friend of the family or an outside co-investor raises questions straight away.
Why Family Office Bank Accounts Get Refused
UK money laundering rules list "a legal person or legal arrangement that is a vehicle for holding personal assets" as a higher-risk factor, and that describes most family office structures. Politically exposed family members add enhanced checks and senior management approval. After Singapore's 2023 money laundering case, account opening that took less than a month was reported as possibly taking three to four months, and some existing accounts were closed. Banks rarely explain a refusal, so the file has to be right the first time.
Read more: Why banks reject business account applications and how to open a bank account for holding companies.
Banks That Open Family Office Accounts
Family offices bank mostly with private banks, and each one sets an entry point. The table shows what the main options publish.
Bank | Who it takes | Who it turns away | Monthly fee or minimum |
|---|---|---|---|
Citi Private Bank | Single family offices with more than $100 million in assets | Multi family offices and smaller offices, for its family office services | Net worth from $10 million, or $25 million in Europe, the Middle East, Africa and Latin America |
Barclays Private Bank | Family offices alongside individuals, trusts and charities | Portfolios below its threshold | Portfolio of £3 million in the UK, £5 million elsewhere |
HSBC Private Bank (Channel Islands and Isle of Man) | Clients with assets over £1.5 million | Clients below the threshold | £1.5 million in assets |
Coutts | Private clients bringing £3 million or more | Businesses registered outside the UK | Relationship based |
J.P. Morgan, UBS and Julius Baer | Family offices through their family office services | Decided case by case | Relationship based |
Mercury (US) | US companies, LLCs and partnerships | Trusts and companies formed outside the US | $0 to $299 a month |
Starling (UK) | UK companies owned by UK-resident individuals | Holding companies and corporate shareholders | Plan based |
Digital banks are not an answer either. Revolut, Wise and Mercury have no stated policy on family offices, Mercury turns away trusts, and Starling refuses holding companies, which is how many family offices are owned. Choosing a bank for a family office comes down to where it is based, how much the family will keep with the bank and how many entities need accounts.
Private Banks Price on Assets Under Management
Private banks earn on the assets they manage, and family offices cost money to run. Citi's guide says the family office model now scales to families with "US$200 million or more in investible wealth", with a small office costing "about $2 million to $4 million annually". The UBS Global Family Office Report 2025 puts the average pure cost of running an office at 41.1 basis points of assets. A bank that wins the investment mandate will open the accounts; one that does not may not.
Singapore Requires a Local Bank
From 15 June 2026, under Singapore's revised licensing exemption framework, a single family office must notify the Monetary Authority of Singapore and "maintain bank accounts with a MAS-licensed bank", and so must each of its Singapore fund vehicles. A fund vehicle incorporated abroad may instead bank in a country whose anti-money laundering standards are consistent with FATF standards. Its annual return has to list those accounts. Funds that claim the 13O or 13U tax incentive must also hold a private banking account with a MAS-licensed financial institution, with a three-month grace period to open it for awards from 1 August 2026.
Onboarding Takes Weeks, Even at Private Banks
Singapore's private banks report a median of five to six weeks to open an account, and longer for complex cases, and have committed to bring it within one month by the end of 2026. Elsewhere, banks do not state a time, and a family office with entities in several countries meets several reviews.
Operating Accounts Come Second
Private banks sell custody and investment management first. Bank of America notes that some family offices "like to control their own checkbook and therefore wish to pay bills internally", and sells a separate treasury platform for it. For most offices, the operating account for payroll, fees, deal deposits and transfers between entities is the one that is hardest to get quickly.
Read more: Business bank account vs EMI account and best countries for business banking.
Interpolitan Money
Business account
Time to onboard
1 Week
Currency
EUR, USD, GBP, AED, and 50+
Monthly fee
Custom
A Faster Way to Open a Bank Account for Family Offices
There is a better alternative to the bank queue. Our partner, Interpolitan Money, is an electronic money institution authorised by the UK Financial Conduct Authority, with a Dubai International Financial Centre entity licensed by the DFSA. It names private clients and family offices as a core segment, for "International wealth structuring, mobility planning, property portfolios and diversification of jurisdictional risk", and offers dedicated one-to-one support for family offices, complex business structures and offshore trusts. It describes layered ownership, multiple beneficiaries and non-resident owners as features rather than red flags.
Each entity gets a multi-currency account holding 50+ currencies, with a unique IBAN or account number for each currency. Payments run over SWIFT, SEPA, SEPA Instant, Faster Payments, BACS and CHAPS, and batch payments pay several recipients in one go. Currency can be exchanged at spot, fixed ahead with a forward, or set with a limit or stop-loss order. Every wealth client gets a named relationship manager, "Not a chatbot. Not a queue." Interpolitan says straightforward structures open in as little as 48 hours and most complex applications in 7 to 10 days.
We prepare the file before the partner sees it: the company documents for each entity, a structure chart up to the family, identity documents and a written source of wealth. Client money is held in segregated safeguarding accounts at major banks, separate from the partner's own funds. Be clear about what the account does: it receives, holds, converts and pays money. It does not offer loans, pay interest or hold securities, and it is not covered by the UK deposit guarantee scheme.
Feature | Private banks | Our partner |
|---|---|---|
Time to open | Five to six weeks median in Singapore, longer for complex cases | 48 hours to 10 days |
Entry point | £1.5 million to £5 million in assets, or $100 million for Citi's family office services | No minimum balance on non-resident accounts |
Who they accept | Families bringing an investment mandate | Family offices and their entities, outside restricted countries |
Relationship | Banker focused on investments | Named relationship manager for payments and currency |
Monthly cost | Relationship based | Custom, set for the structure |
Currencies | Available, often through separate accounts | 50+ currencies in one account |
International payments | £13 to £92 each at offshore banks | £5 to £15 each |
Lending and custody | Available at private banks | Not offered, funds safeguarded instead |
For a family office that needs to pay staff, fund deals and move money between entities in several currencies, our partner is faster and simpler. A private bank remains the right home for custody, investment management and lending, and the two work side by side.
Which Family Offices Our Partner Accepts
Our partner names private clients and family offices as a core segment and works with trusts, foundations, SPVs and structures with several entities, including DIFC and ADGM foundations. For UK property held in separate companies it offers dedicated property SPV accounts. We check the fit before anyone applies. What it will not take is a structure that hides who is behind it, money with no clear source, sanctioned links or payments to restricted countries and industries.
Opening a Bank Account for Family Offices Online
Opening a bank account for family offices online works in four steps. We build the file with you, the directors and family members verify their identity and sign the application, the partner's compliance team reviews the structure and asks any questions through us, and the accounts go live with their IBANs and account numbers. No one has to visit a branch, and the account owner can add authorised users such as the office's finance staff.
Interpolitan Money
Business account
Time to onboard
1 Week
Currency
EUR, USD, GBP, AED, and 50+
Monthly fee
Custom
Documents for a Family Office Bank Account
The documents for a bank account for family offices cover the office itself, every entity it manages and the family behind it. We gather them with you and write the parts reviewers care about most.
A Structure Chart Across Every Entity
Show every company, trust and foundation from the family down to each investment vehicle. One Hong Kong bank asks for an "Ownership chart showing the company name, the country of incorporation and ownership/voting % of each shareholder of the intermediate layer in the ownership structure up to the ultimate beneficial owners." Mark who controls each entity, including trustees, protectors and foundation councils, and not only who owns it.
Company Documents and Board Authority
For each entity, provide the certificate of incorporation, constitution and a company search report or certificate of incumbency issued within the last six months. Add a board resolution or mandate that authorises the account and names the signatories. Where a trust or foundation sits above the office, add the trust deed or foundation charter as well.
The Family's Source of Wealth
This is the part reviewers read most closely. Singapore's industry guidance lists the evidence banks treat as corroboration: audited accounts, sale and purchase agreements, tax returns, a "deed of gift, will, probate", portfolio and bank statements and property records. Where wealth was gifted or inherited, banks may assess the person who gave or left it. Write the story in plain terms and back each step with a document.
Regulatory Status
Show how the office is set up under local rules. A new Singapore single family office files a notice of commencement within 14 days of starting business and an annual return within four months of its year end. A DIFC family office holds its registration, an ADGM office its licence, and a US office relies on the SEC's family office exclusion. Include the relevant certificate or a short note on why the office needs none.
Tax Forms
Add the CRS self-certification for each entity and its controlling persons, and a W-9 or W-8BEN-E where US income or US persons are involved. An investment company run by a licensed manager may count as an investment entity under CRS, so check its status before you fill in the form.
Read more: Documents needed to open a business bank account and business bank account requirements.
Prepare Your Family Office Bank Account File
A family office account opens fastest when every entity fits on one page and the family's wealth is traced. We prepare it with you.
- Structure chart signed: Every company, trust and foundation, with control shown.
- Source of wealth written: Clear, evidenced and in the format reviewers use.
- Entity packs: Incorporation, constitution, good standing and board authority.
- Regulatory status: Registration, licence or exemption shown.
- Tax forms ready: CRS self-certification and the right US form.
Family Office Bank Account Costs
The cost of a bank account for family offices is mostly hidden in the relationship. A private bank rarely charges a visible monthly fee, but it expects assets under management and prices its services around them. Offshore banks add yearly charges for accounts they rate high risk or linked to a PEP. The table sets typical ranges at banks against our partner's published pricing.
Charge | Typical range at a bank | With our partner |
|---|---|---|
Entry point | £1.5 million to £5 million in assets at private banks | No minimum balance on non-resident accounts |
Monthly or relationship fee | Relationship based, or $0 to $299 a month at Mercury | Custom, set for the structure |
Yearly high-risk charge | From £2,500 at some offshore banks | None published |
Yearly charge where a PEP is involved | From £4,500 | None published |
Enhanced due diligence fee | Up to £10,000 a year per entity | None published |
Payment out in EUR or GBP | £13 to £92 at offshore banks | £5 |
Payment out in USD | £13 to £92 | £10 |
Payment out in AED and other currencies | £13 or more, plus correspondent fees | £15 |
Urgent payment | Varies by bank | £10 extra |
Payment instructed by phone or email | £20 to £92 manual fee | £40 |
Additional currencies | Separate currency accounts, often with extra fees | 50+ currencies in one account |
For a family office, the biggest cost is usually the money a bank wants to manage before it opens the accounts. A family with £4 million to invest may qualify at one private bank and not another, and the office's own operating needs rarely move the decision. Currency adds more: a 2% margin on $3 million of transfers a year costs $60,000. A private bank is still the right home for the investment portfolio, and it is fair to say so. All figures are planning ranges drawn from published tariffs, and we confirm your final price in writing before you apply.
Interpolitan Money
Business account
Time to onboard
1 Week
Currency
EUR, USD, GBP, AED, and 50+
Monthly fee
Custom
How Long Family Office Bank Account Opening Takes
A bank account for family offices takes weeks at most banks and longer for structures that cross several countries. Singapore's private banks report a median of five to six weeks, and the Monetary Authority of Singapore says most applications for its family office tax incentives are now approved within three months, down from as long as a year. With our partner, straightforward structures can open in 48 hours and complex ones in 7 to 10 days.
Stage | Private bank | Our partner |
|---|---|---|
Preparing the file | 2 to 4 weeks for a multi-entity family | A few days, built with us |
Review and follow-up questions | Five to six weeks median in Singapore, longer for complex cases | 48 hours to 10 days |
Account open and ready | After every entity and signatory is cleared | 48 hours for simple structures, 7 to 10 days for complex ones |
What Slows It Down
The usual delays are an entity missing from the chart, a trust or foundation whose controllers are not named, a source of wealth that rests only on the family's own documents, and a family member who cannot verify their identity in time. Every missing item restarts part of the review.
Banking for Family Offices in Singapore and the UAE
In Singapore and the UAE, the family office regime and the bank go together. Singapore has more than 2,000 single family offices with tax incentives and requires a MAS-licensed bank. The DIFC had 1,408 family business related entities by the first half of 2026, up 36% in a year, and its family office regime asks for at least USD 50 million in family net assets. Our partner's DIFC entity is licensed in the same centre.
How to Speed It Up
Build the structure chart and source of wealth first, collect every family member's and director's documents in one round, and agree the signatories for each entity before you apply. Apply once, to a provider that takes your kind of family office, rather than to several banks at the same time.
Interpolitan Money
Business account
Time to onboard
1 Week
Currency
EUR, USD, GBP, AED, and 50+
Monthly fee
Custom
What Happens After the Account Is Open
After the accounts open, fund them, add the authorised users and set up the regular payments: salaries, adviser fees, capital calls and transfers between entities. Keep each entity's money in its own account and record every transfer between them, so the books match the structure.
Keep the file current, because providers review family offices regularly. Tell the provider when a family member joins or leaves a role, when a trust or foundation changes, or when a new entity is added. In Singapore, list the office's MAS-licensed bank accounts in each annual return. From 10 July 2027, the EU's new anti-money laundering regulation applies, with a 25% direct or indirect ownership test.
Families are also moving. In a Standard Chartered survey of more than 300 wealthy families in 2025, 54% said they were considering relocating their family office that year, and a move means a new banking relationship. Take tax and legal advice before you move the office or its entities.
Why the Family Office Comes Before the Account
A provider can only review a family office that is properly set up: its companies registered, its trusts or foundations in place, and any registration or tax incentive applied for where the family wants one. The table shows the main regimes and what each asks of the family.
Jurisdiction | Regime | Entry test | Key condition |
|---|---|---|---|
Singapore | Single family office exemption, plus 13O or 13U tax incentive | S$20 million (13O) or S$50 million (13U) in designated investments | MAS-licensed bank account for the office and its funds |
DIFC (Dubai) | Registered family office | USD 50 million in family net assets | One family only, unless licensed |
ADGM (Abu Dhabi) | Single family office licence | Minimum family net assets set by ADGM | Incorporation USD 5,600, yearly renewal USD 5,300 |
Hong Kong | Family-owned investment holding vehicle tax concession | HK$240 million in specified assets | Two full-time staff and HK$2 million spending in Hong Kong |
United States | SEC family office exclusion | Family clients only | Wholly owned and controlled by the family |
Switzerland | Exemption under the Financial Institutions Act | Managing assets of family members only | No licence needed for family-only managers |
Many family offices hold their investments through a holding company, with a trust or foundation at the top for succession. Our guides to setting up a family office in Singapore and a family office in Hong Kong walk through the steps. Set up the structure first, then open the accounts with a complete file.
Common Family Office Bank Account Mistakes
Most problems with a bank account for family offices come from how the structure is presented, not from the family itself. These are the mistakes we see most.
Mixing in Money From Outside the Family
A co-investor's money or a friend's contribution paid into a single family office account breaks the one-family test and prompts the questions reviewers ask most.
Using the Private Bank as the Operating Account
Running payroll and adviser fees through an investment account slows both down. Keep an operating account for payments and the private bank for the portfolio.
Describing the Wealth in One Line
"Family wealth" is not a source of wealth. Show how the money was made, how it moved and how it reached each entity.
Leaving a Trust or Foundation Off the Chart
A trust or foundation above the office has controllers the bank must identify. A chart that stops at the holding company leaves the reviewer to find them.
Applying to Banks That Exclude Holding Structures
A family office owned by a holding company that applies to a bank refusing holding companies or corporate owners is turned away by the eligibility rules.
Get Help With a Family Office Bank Account
Family office banking is very manageable when the structure is planned with the bank in mind. Talk to us before the family applies.
- Structure checked first: We confirm our partner can bank your family office.
- Every entity covered: Companies, trusts, foundations and property vehicles.
- Refused before: We review the file and fix the gaps.
- Honest advice: We tell you when a private bank should sit alongside.
- One point of contact: From the first call to the first transfer.
Bottom Line
Banking for family offices is harder than most families expect. Private banks want assets to manage before they open accounts, source of wealth is checked in depth, every entity needs its own review, and digital banks turn away the holding companies and trusts family offices are built on.
For families with entities in several countries, the faster route is a regulated partner built for complex structures. With a complete file, including a structure chart, the entity documents and a traced source of wealth, a bank account for family offices takes about a week, with no branch visit.
How do I open a bank account for a family office?
Why is banking for family offices so hard?
What is the minimum to bank a family office with a private bank?
What documents do you need for a bank account for family offices?
Does a Singapore family office need a Singapore bank account?
How long does it take to open a bank account for family offices?
Can a multi family office use the same route?
Why do banks worry about money from outside the family?
How much does a bank account for family offices cost?
Can one account hold several currencies for a family office?
Does each family entity need its own bank account?
Can a family office in the DIFC open an account quickly?
Can a family office keep a private bank and a partner account together?
Sources
- SEC Rule 202(a)(11)(G)-1: family offices (eCFR)
- Monetary Authority of Singapore: Fund tax incentive scheme for family offices
- Association of Banks in Singapore: ACIP best practices on source of wealth due diligence
- Association of Banks in Singapore: ACIP best practices on risks in wealth management
- ADGM: Family offices
- Inland Revenue Department Hong Kong: Family-owned investment holding vehicles
- Hong Kong Government: Family office figures, 30 July 2025
- BIS: Speech by the MAS Deputy Chairman, 16 September 2024
- The Money Laundering Regulations 2017, regulation 33
- DFSA Public Register: Interpolitan Money (DIFC) Limited