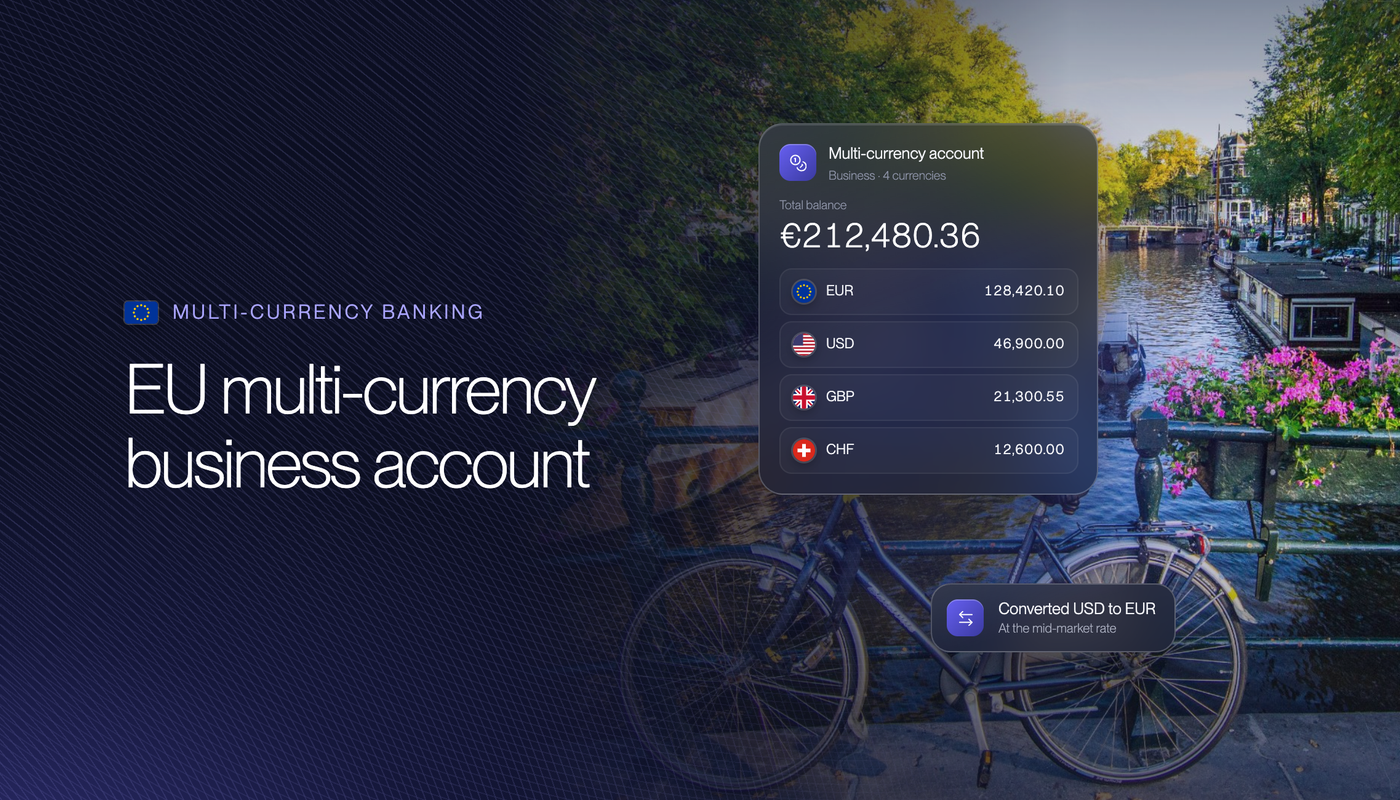
An EU multi-currency business account lets your company hold euros, US dollars, pounds and other currencies in one account with an EU IBAN. Euro clients pay you by SEPA, and under EU law no payer in the EU may refuse your IBAN because it was issued in another member state.
The hard part is the banks. In Cyprus, Malta and Ireland, a currency account is an add-on to a main account that foreign-owned companies struggle to open. Bank of Cyprus charges companies from outside the EEA €75 a month, HSBC Malta charges international companies €175, and every conversion carries a commission or margin.
This is where we come in. Our EU-licensed partners hold several currencies in one account and open it in 4 days to about a week, fully remotely. We handle the work for you: the company file, the KYC pack, the source of funds and every question in review. One team, one point of contact, and we get it done.
Our top-rated, licensed banking providers open EU multi-currency accounts for companies in 4 days to about a week, with no branch visit.
Moneybase
Multi Currency Business Account
Time to onboard
4 Days
Account opening fee
Free
Monthly fee
Starting from € 9.99
3S Money
Cross-border payments
Time to onboard
4 Days
Account opening fee
Free
Monthly fee
Starting from € 100
Why an EU Multi-Currency Business Account Is Hard to Get
An EU multi-currency business account is hard to get at a bank because currency accounts are sold as extras to existing customers. Banks in Cyprus, Malta and Ireland open the euro account first, charge more when the owners or the company sit outside the EEA, and review every foreign currency flow slowly. With a complete file and the right provider, it is very doable.
Euro Is Simple, Other Currencies Are Not
Euro payments inside the EU are cheap and fast. Since 9 October 2025, every bank in the euro area that offers standard euro transfers must also send and receive SEPA Instant payments, at no higher price than a standard transfer. The other currencies are where the cost sits. A US dollar or sterling balance at a bank needs a separate currency account, each payment outside SEPA goes through SWIFT with its own fee, and each conversion carries a margin. A multi-currency business account in the EU earns its keep on that non-euro side.
Banks Sell Currency Accounts to Existing Customers
AIB opens Currency Current Accounts for business customers only, with US dollars, sterling, Canadian dollars and Australian dollars readily available and other currencies on request. Bank of Ireland runs its currency accounts through Global Markets, again for business customers only. In both cases the euro relationship comes first. In Cyprus, Bank of Cyprus asks international clients to visit an International Business Unit in person or apply through a local professional intermediary, and Eurobank starts with an International Customer Questionnaire and a virtual or physical meeting.
Open an EU Multi-Currency Business Account
You can open an EU multi-currency business account for your company without a branch visit or a local director. This is what we handle.
- Several currencies, one account: Hold euros, dollars, pounds and more under one login.
- EU-licensed partners: Regulated in Malta and Luxembourg, built for cross-border companies.
- KYC pack built for you: We tell you what is needed and prepare it before review.
- Remote identity checks: Directors verify by passport and live selfie, no branch visit.
- Live in days: 4 days at two partners, about a week at the third.
- Conversion from 0.25%: Published margins well below typical bank rates.
Surcharges for Foreign-Owned Companies
Banks price foreign ownership in. Bank of Cyprus, in its June 2026 schedule for International Business Unit customers, charges €50 a month to keep an active account for a company incorporated in the EEA or an equivalent country and €75 a month for a company incorporated elsewhere. New legal entities from outside the EEA pay a €300 application fee, or €500 where enhanced due diligence applies, and periodic review fees run from €500 to €2,000. HSBC Malta's April 2026 tariff charges €175 a month and a one-off €100 to an international company, meaning one registered outside Malta or 50% owned by a parent outside Malta. A local company pays €30.
Sectors and Refusals
Gaming and payment companies pay most. Bank of Valletta's tariff effective 1 September 2026 charges a gaming company or payment processor €3,000 to open and up to €600 a month, against €300 to open and up to €60 a month for other corporate entities in its Specialised Business Banking unit. Bank of Cyprus says it may decline an application for legal, regulatory or other reasons without explaining why, and it charges €320 a month to a client it has not accepted until the accounts close. A refusal also stays in your history, because the next bank asks whether you were refused before. Our guide on why banks reject business account applications lists the usual reasons, each one fixable.
What to Do After a Refusal
Do not send the same file to the next bank. Find the gap first: an ownership chain that stops at a company, a source of funds without evidence, or currency flows that do not match the business. Fix it, then apply once to a provider that takes your sector and your owners' countries. One of our partners accepts gambling, betting, casino and crypto businesses, so a high-risk sector is not a dead end. See our guide to banking for a gambling company.
Read more: business bank account in Europe and European business bank account for non-residents.
EU Rules for a Multi-Currency IBAN in the EU
A multi-currency IBAN in the EU works anywhere in the euro payment system because EU law makes it so. The SEPA Regulation bans IBAN discrimination, the Instant Payments Regulation adds instant euro transfers and a free name check, and the deposit guarantee covers bank balances up to €100,000. A few new rules arrive in 2027.
The EU IBAN Rule
Article 9 of the SEPA Regulation, Regulation (EU) No 260/2012, says a payer or payee may not specify the member state in which the other side's euro account must be located. A Maltese or Luxembourg IBAN on an EU multi-currency account therefore works for a German customer, an Irish tax office or a Dutch supplier. If a client insists on a local IBAN, the rule is on your side. Our planned guide to Cyprus IBAN accounts for businesses covers local IBANs in more depth.
SEPA Instant and Verification of Payee
The Instant Payments Regulation, Regulation (EU) 2024/886, made banks in the euro area receive instant euro payments from 9 January 2025 and send them from 9 October 2025. From the same October date, they must offer Verification of Payee free of charge, which checks the payee's name against the IBAN before a euro payment leaves. For your company, that means the account name must match the registered company name exactly, or clients will see a warning when they pay you. E-money and payment institutions get longer: they must receive and send instant euro payments by 9 April 2027.
Deposit Guarantee or Safeguarding
Bank deposits in the EU are covered up to €100,000 per depositor per bank, the limit the Central Bank of Cyprus confirms for its scheme. E-money institutions are not banks. They do not lend client money out, and they must safeguard it, kept separate from their own funds, so it is protected if the firm fails but not by a deposit guarantee. Our guide to deposit guarantee schemes for business accounts explains the difference.
New EU Rules Coming in 2027
The Anti-Money Laundering Regulation, Regulation (EU) 2024/1624, applies from 10 July 2027 and puts one rulebook on every bank and e-money institution in the EU, supervised in part by the new EU Anti-Money Laundering Authority in Frankfurt. The EU right to a basic payment account covers consumers only, so companies still have no legal right to an account. PSD3 and the Payment Services Regulation were agreed in November 2025 and are expected to apply from around 2028.
Read more: what an EMI account is and business bank account vs EMI account.
Bank Currency Accounts in Cyprus, Malta and Ireland
Banks in Cyprus, Malta and Ireland all offer currency accounts, but the price of holding several currencies there is a monthly fee for the main account, a fee for each payment outside SEPA and a commission or margin on each conversion. The table shows what each bank publishes in its own current tariff.
Bank | Currency accounts | Who it takes | Account fees | Conversion cost |
|---|---|---|---|---|
Bank of Cyprus | Foreign currency balances on its business accounts | International companies through an International Business Unit or an intermediary | €50 a month (EEA), €75 (outside the EEA), plus €300 to €500 application fee | 0.40% commission per conversion, min €5, max €400 |
Eurobank | International current account in multiple currencies | International clients after a questionnaire and a meeting | Relationship based, by account type | Relationship based |
HSBC Malta | Euro and non-euro accounts | Local and international companies | €30 a month (local), €175 (international), plus €100 opening for international | 0.50% commission on its revaluation rate |
Bank of Valletta | Euro and foreign currency accounts | Corporate entities, with higher fees for gaming and payment firms | €300 to €3,000 opening, up to €60 or €600 a month | At the bank's own exchange rate |
APS Bank | EUR, GBP, USD, AUD, CAD, CHF, JPY, NOK, SEK and DKK accounts | Companies, including foreign shareholding | €100 application, €95 periodic review | 1.75% on card conversions |
AIB | USD, GBP, CAD and AUD, others on request | Business customers only | €0.80 per transaction | Published standard rate, negotiated above a threshold |
Bank of Ireland | Most major currencies through Global Markets | Business customers only | €0.95 per transaction | Up to 2.5% each side up to €10,000 |
Every bank in the table treats foreign currency as an extra. You win the main account first, then pay per account, per payment and per conversion. For a foreign-owned company, the main account is where most applications stall, and the surcharges apply before a single currency is held.
Multi-Currency Business Account in Cyprus
A multi-currency business account in Cyprus at Bank of Cyprus costs €50 to €75 a month to keep, plus payment fees. Its June 2026 schedule charges SWIFT payments in any foreign currency at 0.15%, minimum €5 and maximum €250, plus a €17 processing fee up to €10,000 through its online banking. Incoming payments cost €3 to €30 online depending on the amount, and accounts with four or fewer transactions in a month pay a €20 low activity fee unless the average foreign currency balance tops €20,000. The market has also consolidated. Hellenic Bank absorbed Eurobank Cyprus on 1 September 2025 and is being renamed Eurobank Limited, and Alpha Bank Cyprus took over AstroBank's banking business on 31 October 2025. Eurobank and Alpha Bank Cyprus set business fees in their own charge schedules, so ask for the current one before you apply. See our guide to the best banks for Cyprus companies.
Multi-Currency Business Account in Malta
A multi-currency business account in Malta is cheap for local owners and expensive for everyone else. HSBC Malta charges €12 for an outgoing SWIFT payment in a currency other than euro through online banking and €10 to credit a foreign currency payment to a non-euro account. Bank of Valletta charges €12 plus foreign bank charges for a SWIFT payment from its online banking, and APS Bank charges €12 through myAPS. APS holds accounts in ten currencies. Read our guide to opening a Malta business bank account.
Multi-Currency Business Account in Ireland
A multi-currency business account in Ireland means a currency current account next to your euro account. AIB's online route is for companies registered and trading in Ireland, owned directly by up to five directors, and identity is still checked in a branch. Its currency accounts have no cards, direct debits, standing orders or instant transfers. Bank of Ireland's currency accounts have no cards, cash or instant credit transfers either, and its April 2025 Global Markets tariff allows a 4% spread, up to 2.5% each side, on sterling and dollar deals up to €10,000. See business bank accounts in Ireland for new companies.
Why Stacking Bank Currency Accounts Costs More
Each bank account adds its own fee, its own review and its own payment charges. A company that holds euros at a Cypriot bank, dollars at a second bank and sterling at a third pays three sets of fees and passes three reviews. Conversions between the banks cost a margin each time, and SWIFT charges apply on both sides. One European multi-currency business account removes the stack: every currency sits under one plan and moves between balances at one published margin. Other EU countries follow the same pattern; see our guides for Germany, the Netherlands, Spain and Luxembourg.
Trumia
Business account
Monthly fees
€50
Onboarding fees
€500
Time to onboard
1 week
Accepts
Gambling, Betting, Casino, Crypto, and more
A Faster and Cheaper Way to Open an EU Multi-Currency Business Account
There is a better route than stacking bank currency accounts. Our partners are e-money and financial institutions licensed in the EU: two by the Malta Financial Services Authority and one through a Luxembourg entity authorised by the CSSF. They open one EU multi-currency account for business that holds several currencies, in 4 days at two partners and about a week at the third, fully remotely and with no branch visit.
It is cheaper where the money goes. One partner publishes conversion margins of 0.95%, 0.70% and 0.25% on its plans, against Bank of Cyprus's 0.40% commission on top of its own rate and Bank of Ireland's ceiling of 2.5% each side. Monthly plans run from €9.99 to €100, against €75 at Bank of Cyprus or €175 at HSBC Malta for a foreign-owned company. One partner exchanges 24 currencies and gives up to 20 IBANs on its top plan. Another holds more than 65 currencies with local IBANs in Luxembourg, France and the Netherlands as well as the UK. Opening is free at two partners. The partner that takes high-risk sectors charges a one-off €500 onboarding fee.
We prepare the file before the partner sees it: the company documents, the owners' identity documents, what the business does, who pays you in which currencies, and a written source of funds. Because the usual questions are answered upfront, the review happens once.
Feature | Cyprus, Malta and Irish banks | Our partners |
|---|---|---|
Time to open | Weeks, with a meeting or branch identity check | 4 days at two partners, about a week at the third |
Who they accept | Mostly local or existing customers; surcharges for foreign ownership | Companies with owners abroad; gambling, betting, casino and crypto at one partner |
Account structure | A main euro account plus a currency account per currency | One account holding several currencies |
Currencies | 4 readily available at AIB, 10 at APS Bank | 24 exchanged at one partner, 65+ held at another |
IBANs | One IBAN per account | Up to 20 IBANs at one partner; local IBANs in LU, FR, NL and GB at another |
Monthly cost for a foreign-owned company | €75 at Bank of Cyprus, €175 at HSBC Malta | From €9.99 to €100 on published plans |
Opening | €100 to €3,000 at HSBC Malta, Bank of Valletta and Bank of Cyprus | Free at two partners, €500 at one |
Conversion | 0.40% to 0.50% commission plus the bank's rate; up to 2.5% each side at Bank of Ireland | From 0.25% on published plans |
Lending and cash | Overdrafts, loans and cash at most banks | No lending, no cash, no interest |
Protection | €100,000 deposit guarantee per bank | Safeguarded client money |
Our partners win on conversion, on holding every currency in one account, on monthly fees for foreign-owned companies and on speed. To be fair to the banks, a Maltese company with local owners that only pays in euros pays €30 a month at HSBC Malta and €0.15 for a small online SEPA payment, which is hard to beat. If you mostly pay in euros and rarely convert, a local bank can be the cheaper choice, and we will tell you so.
What Our Partners Do Not Do
Our partners do not lend, so there is no overdraft or business loan. They do not take cash and do not pay interest on balances. Money is safeguarded rather than covered by the €100,000 deposit guarantee. Many companies keep a local bank for lending and a reserve balance, and run payments and currencies through the partner account.
3S Money
Cross-border payments
Time to onboard
4 Days
Account opening fee
Free
Monthly fee
Starting from € 100
Trumia
Business account
Monthly fees
€50
Onboarding fees
€500
Time to onboard
1 week
Accepts
Gambling, Betting, Casino, Crypto, and more
Documents Needed for an EU Multi-Currency Business Account
The documents needed for an EU multi-currency business account are the company's registry records, identity documents for every director and owner, and a clear picture of your currency flows. Banks and partners ask for the same core set. A complete pack in one round is what makes the account open in days.
Company Documents
You need the certificate of incorporation, the memorandum and articles, a recent registry extract, the register of directors and shareholders, and the beneficial ownership details. In Cyprus that is the Registrar of Companies, in Malta the Malta Business Registry, and in Ireland the Companies Registration Office. If a holding company sits above yours, show every layer up to the real people. Bank of Cyprus charges €30 to €120 just to collect corporate documents digitally, so arrive with them. See our full list of documents needed to open a business bank account.
Owners, Directors and Signatories
Each director, signatory and owner of 25% or more gives a valid passport and a recent proof of address. Partners check identity remotely with a live selfie, so nobody travels. Banks often want a branch visit or a meeting instead. Read how to open a business bank account remotely.
Currency Flows and Source of Funds
This is the part most applicants leave thin, and it matters most for a European multi-currency business account. The reviewer wants to know:
- Which currencies you receive, from which countries and from whom
- Which currencies you pay out, and to whom
- Expected monthly volumes in and out, per currency
- Contracts, invoices or a website that show real trade
- Where the first deposit comes from, with evidence
Read more: business bank account for non-residents.
Prepare Your EU Multi-Currency Account File
An EU multi-currency account opens fastest when the file explains every currency you plan to use. We prepare it with you.
- Registry pack complete: Extract, articles and ownership chart in one set.
- Owners verified remotely: Passports and address proofs, checked by live selfie.
- Currency map written: Who pays you and whom you pay, by currency and volume.
- Source of funds evidenced: Written in the format reviewers expect.
- Fit checked first: We confirm your sector and countries before you apply.
EU Multi-Currency Business Account Costs
EU multi-currency business account costs come from four places: the account fee, payment fees, the conversion margin and fees on incoming money. At a bank in Cyprus, Malta or Ireland, foreign ownership raises the account fee and each conversion carries a commission or margin. The table sets published bank charges against our partners' plans.
Charge | Typical range at a local bank | With our partners |
|---|---|---|
Account opening | Free for local companies; €100 to €3,000 for international or high-risk ones | Free at two partners, €500 at one |
Monthly fee, local company | €30 at HSBC Malta and Bank of Valletta | From €9.99 to €100 on published plans |
Monthly fee, foreign-owned company | €75 at Bank of Cyprus, €175 at HSBC Malta | From €9.99 to €100 on published plans |
Application or review fee | €95 to €2,000 per review | Quoted with your setup |
Extra currency accounts | A separate account per currency | Included in one account |
SEPA payment out | Free to €12 online | From €0.20 at one partner, €2 at another |
SEPA payment in | Free up to €10,000 in Malta; €3 to €30 at Bank of Cyprus | Free at one partner |
SWIFT payment out | €12 in Malta; 0.15% plus €17 at Bank of Cyprus | From €5 at one partner |
SWIFT payment in | Up to €10 in Malta; €5 to €12.50 at Bank of Ireland | €5 at one partner |
Conversion | 0.40% to 0.50% commission plus the rate; up to 2.5% each side at Bank of Ireland | From 0.25% on published plans |
Card spending in other currencies | 1.75% at APS Bank | Shown on the plan |
Low activity or dormancy | €20 a month at Bank of Cyprus; €35 a year at Bank of Valletta after two idle years | Shown on the plan |
Account closure | €200 at Bank of Cyprus | Shown on the plan |
Protection | €100,000 deposit guarantee per bank | Safeguarded client money |
The monthly fee is rarely the biggest line. The money goes on the margin, because it is charged on every conversion, and on SWIFT fees, because they apply to every non-euro payment. A foreign-owned company also pays the surcharge before it converts anything. The more currencies you hold and the more you convert, the more the partner route saves.
A Worked Example in Euros
This is an illustration with assumed numbers, not a quote. Take an Irish company that receives US dollar sales worth €40,000 a month in ten payments, converts them to euros in four deals of €10,000, and sends six SWIFT payments a month of about €4,000 each.
At Bank of Ireland's Global Markets ceilings, the margin can reach 2.5% on deals up to €10,000, so the conversions can cost up to €12,000 a year. Six payments a month at 1% of value cost €2,880 a year, ten incoming payments over €1,500 cost €1,500 a year at €12.50 each, and the €0.95 transaction fee adds about €230. The total can reach about €16,600 a year.
With one of our partners, a 0.25% margin on the €85 plan makes the conversions €1,200 a year and the plan €1,020. Incoming SWIFT at €5 costs €600 and outgoing payments from €5 cost from €360. Opening is free. The total is about €3,200 a year, or about €5,600 on the €9.99 plan at a 0.95% margin. Most of the saving comes from the margin, so it shrinks if you rarely convert.
All figures are planning ranges taken from published tariffs. We confirm your final price in writing before you apply.
Read more: business bank account fees and the multi-currency business account guide.
Moneybase
Multi Currency Business Account
Time to onboard
4 Days
Account opening fee
Free
Monthly fee
Starting from € 9.99
Trumia
Business account
Monthly fees
€50
Onboarding fees
€500
Time to onboard
1 week
Accepts
Gambling, Betting, Casino, Crypto, and more
How Long an EU Multi-Currency Business Account Takes
An EU multi-currency business account with our partners opens in 4 days at two of them and about a week at the third, once the file is complete. At a bank, the main account comes first, often after a meeting or a branch identity check, and the currency accounts follow. AIB alone allows up to 10 business days for its final check after identity is verified.
Stage | Local bank | Our partners |
|---|---|---|
Company registration | Needed first | Needed first |
Application | Questionnaire, meeting or branch visit | Online, identity checked by live selfie |
Review | About 5 business days to first response at AIB, plus a final check of up to 10 | 4 days at two partners, about a week at the third |
Currency accounts | Added after the main account | Included from the start |
First payment | Once each account is set up | As soon as the account is live |
With a bank, the euro account and each currency account are separate steps. With our partners, you apply once for one account that holds several currencies.
What Slows It Down
Delays come from gaps in the file: an ownership chain that stops at a company, a source of funds without evidence, currency flows that do not match the business, or a sector the provider must review. Each question adds days, and a late answer puts the file back in the queue.
How to Speed It Up
Register the company first, collect every document in one round and write down your currency flows before you apply. Answer questions the same day. Apply once, to a provider that takes your sector and your owners' countries.
3S Money
Cross-border payments
Time to onboard
4 Days
Account opening fee
Free
Monthly fee
Starting from € 100
What Happens After the Account Is Open
After your EU multi-currency account opens, you fund it, add your users and share the right details with each client and supplier. Then keep the file current, because every provider reviews its customers and asks about changes.
Share the Right Details for Each Currency
Give euro clients your EU IBAN and check that the account name matches your registered company name exactly, so Verification of Payee shows a match. Give clients in other currencies the details for that currency. Ask suppliers to confirm new details in writing before the first payment.
Hold Currencies Until You Need Them
Keep money in the currency you will spend it in. Pay dollar suppliers from the dollar balance and convert only the surplus, in fewer and larger deals. This is how an EU multi-currency business account pays for itself.
Reviews and Changes You Must Report
Tell the provider before you add an owner, change the activity, start trading with a new country or move much larger amounts. Unexplained changes trigger reviews and can hold payments. From 10 July 2027, the EU anti-money laundering rulebook makes these checks more uniform across the EU.
Read more: banking for EU holding companies and best EU countries for business banking.
UK Multi-Currency Accounts Outside the EU
A UK multi-currency account is not an EU account. The UK left the EU, so UK firms lost their EU passport, and a UK company is a non-EU business for EU rules. The UK still takes part in the SEPA schemes as a non-EU country, so euro payments work, with extra payer details.
Factor | UK | Cyprus, Malta and Ireland |
|---|---|---|
EU member | No | Yes |
SEPA payments | Yes, as a non-EU participant; payer's full address required | Yes |
EU IBAN rule protects your account | No, a GB IBAN is outside the EU | Yes |
Name check on payments | Confirmation of Payee | Verification of Payee |
Deposit protection | £120,000 per bank under the FSCS | €100,000 per bank |
For a company whose customers are in the EU, an EU IBAN is the safer choice, because the EU IBAN rule protects it and payments need no extra payer data. A UK company can still use a European multi-currency business account if the provider takes UK companies. See our planned guide to UK multi-currency business accounts.
Why the Company Comes Before the Account
No bank and no partner opens a business account for a company that does not exist yet. Every provider asks for the registration number, the registry extract and the ownership records, so the order is always company first, account second. If you are still choosing an EU base, read our guide to EU company formation for non-residents. We form the company and build the account file at the same time, so you can apply the day the company is registered. See Malta company formation with a bank account and Cyprus company formation with a bank account.
Moneybase
Multi Currency Business Account
Time to onboard
4 Days
Account opening fee
Free
Monthly fee
Starting from € 9.99
Common EU Multi-Currency Business Account Mistakes
Most of the money lost on an EU multi-currency business account comes from a few avoidable choices. These are the ones we see most.
Opening One Bank Account per Currency
Many companies add a bank currency account each time a client pays in a new currency. At Bank of Cyprus, a foreign-owned company already pays €75 a month for the main account, plus periodic reviews of €500 to €2,000 and fees on every payment. Spread the currencies across two or three banks and the fixed costs multiply. The fix is one account that holds every currency under a single plan, so each new currency is a balance, not a new relationship.
Converting Every Payment on Arrival
A euro-only account converts every foreign payment on the day it lands, at the bank's rate. At Bank of Ireland's 2.5% ceiling for deals up to €10,000, €300,000 of dollar sales a year can cost €7,500 in conversion alone, and you pay again if the money goes back out in dollars. Hold the currency, pay suppliers from it and convert only the surplus.
Asking for a Local IBAN You Do Not Need
Some founders open a second bank account just to get a local IBAN for one client. Under Article 9 of the SEPA Regulation, a payer in the EU may not refuse your euro account because it sits in another member state. Two bank accounts in Malta and Cyprus cost €80 to €250 a month together in account fees alone. Point the client to the rule instead, and keep one EU IBAN.
Treating Safeguarded Money as Insured
A partner account is safeguarded, not covered by the €100,000 deposit guarantee. That is a sound model for payments and working balances, but it is not a deposit. Keep long-term reserves in a bank, up to €100,000 per bank, and run currencies and payments through the partner account.
Get Help With an EU Multi-Currency Business Account
An EU multi-currency business account is simple to set up when the file and the provider fit your business. Send us your details and we get back to you.
- Sector checked first: We confirm a partner takes your sector and countries.
- Harder sectors accepted: Gambling, betting, casino and crypto at one partner.
- Refused before: We review what went wrong and fix the file.
- Honest advice: We tell you when a local bank is the cheaper choice.
- Company and account together: We form the company and build the account file.
- One point of contact: From the first document to the first payment.
Bottom Line
An EU multi-currency business account saves money once your company is paid or pays in more than euros. Banks in Cyprus, Malta and Ireland offer currency accounts, but as add-ons to a main account, with surcharges of €75 to €175 a month for foreign-owned companies at Bank of Cyprus and HSBC Malta and a commission or margin on every conversion. For a local company that pays only in euros, a local bank can still be cheaper.
For a company owned from abroad, or any business that converts every month, one account with an EU IBAN, several currencies and margins from 0.25% is the better answer. Our partners open it in 4 days to about a week, remotely, and we prepare the file so the review runs once.
What is an EU multi-currency business account?
Can a non-resident open a multi-currency business account in the EU?
Which currencies can an EU multi-currency account for business hold?
How much does an EU multi-currency business account cost?
Is a European multi-currency business account protected?
Do I need a local IBAN for a multi-currency business account in Europe?
How long does it take to open an EU multi-currency business account?
What documents do I need for a multi-currency business account in the EU?
What is Verification of Payee and how does it affect my EU multi-currency account?
Can a high-risk business open an EU multi-currency business account?
Is a UK multi-currency account the same as an EU one?
Should I keep a bank account as well as a multi-currency account in the EU?
Which EU country is best for a multi-currency business account?
Sources
- Bank of Cyprus, Commissions and Charges for International Business Units Customers, June 2026
- Bank of Cyprus, Account opening for international clients
- Eurobank, International Current Account
- HSBC Malta, Commercial Banking General Tariff, April 2026
- Bank of Valletta, Tariff of Charges, effective 1 September 2026
- APS Bank, Tariff of Charges, applicable from 18 May 2026
- AIB, A Guide to Currency Accounts
- AIB, Centralised Account Opening Q&As
- Bank of Ireland Global Markets, Currency Accounts Fees and Charges, effective 7 April 2025
- Politis, Hellenic Bank and Eurobank Cyprus complete merger on 1 September 2025
- Politis, Alpha Bank completes AstroBank acquisition, 3 November 2025
- European Central Bank, Instant Payments Regulation
- Regulation (EU) No 260/2012 (SEPA Regulation), EUR-Lex
- Regulation (EU) 2024/1624 (Anti-Money Laundering Regulation), EUR-Lex
- Central Bank of Cyprus, Deposit Guarantee Scheme
- European Payments Council, UK participation in SEPA after the transition period