An ecommerce payment gateway lets your online store take cards, wallets and local payment methods at checkout and have the money paid into your business account. Customers pay in their own currency, you settle in USD, EUR, GBP, CAD or another major currency, and refunds, disputes and reporting all run through one connection.
Setting it up well is the hard part. Your real rate depends on your customers' card mix, your platform may add its own fee, and every declined payment is a lost sale. Shared accounts also sign stores up quickly, then review them later and sometimes hold their payouts.
We handle that for you. Through one intake form, Binderr Chooses, we match your store with a regulated payment partner that fits your products and markets, set up the gateway and merchant account, and handle the application. Most stores are taking payments within 5 to 7 business days, with one team handling it from start to finish.
Get an E-commerce Payment Gateway Approved
Get an e-commerce payment gateway approved with a regulated partner that fits your products and markets.
- Binderr Chooses: one intake form, and we match your store with the right partner.
- Gateway and merchant account: set up together, ready for your checkout.
- Fast approval: a preliminary answer in about 1 business day.
- Cards, wallets and local methods: the ways your customers actually pay.
- Major currencies: settle in USD, EUR, GBP, CAD and more.
- Website checked: refund, contact and pricing pages fixed before review.
What Is an Ecommerce Payment Gateway?
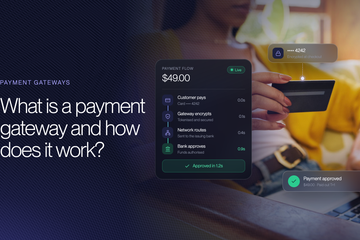
An e-commerce payment gateway sits between your online checkout and the card networks. It takes the card details, protects them, sends the payment to the customer's bank for approval and returns a yes or no to your store, usually within two seconds. Everything else in your payment setup hangs off that one exchange.
What an Ecommerce Credit Card Payment Gateway Handles
An ecommerce credit card payment gateway handles more than cards. It shows the payment methods your customers use, runs fraud checks, applies 3D Secure where it is needed, captures the payment when the order ships, and handles refunds, partial refunds and disputes. It also sends the data you reconcile against your bank statement each month. You will see the same product called an e-commerce payment gateway or an ecommerce website payment gateway. The names differ, the job does not.
Gateway, Acquirer and Merchant Account
Three parts of the setup get confused, and the difference decides who approves you. The gateway captures and routes the payment. The acquirer is the licensed institution that holds your relationship with Visa and Mastercard and carries the risk of your refunds and chargebacks. The merchant account is where your money sits before it reaches your business bank account. Most providers bundle all three, but they remain separate approvals. A store can pass the gateway's technical checks and still be declined by the acquirer. Our guide to payment gateway vs merchant account explains each part.
Why E-commerce Payment Gateways Cost More
E-commerce payment gateways cost more than in-store terminals because every online sale is a card-not-present payment. Nobody checks a chip or a PIN, so the customer's bank carries more fraud risk and prices it in. Visa's US interchange schedule effective 18 April 2026 shows it clearly: 0.80% plus $0.15 on an exempt debit card used in a store, and 1.65% plus $0.15 on the same kind of card used online.
Online stores also carry more of the fraud risk. In a shop, a chip and PIN payment generally protects the merchant against a fraud claim. Online, the merchant carries it unless the payment was authenticated with 3D Secure. Our guide to what a payment gateway is covers the full payment flow.
Ecommerce Payment Gateway Costs
Ecommerce payment gateway services usually cost a percentage of each sale plus a small fixed fee, and your card mix decides most of it. These are typical market ranges on the lower side for standard online stores, taken from published industry guides in 2026.
Cost item | Typical range |
|---|---|
Setup fee | Usually none |
Monthly fee | Often none |
Processing rate | 1.5% to 3.5% of each sale, lower on domestic EEA consumer cards |
Fee per transaction | $0.05 to $0.30 |
Chargeback fee | $15 to $25 per dispute |
Currency conversion | Around 2% when you sell in a currency you do not settle in |
Platform fee for third-party gateways | 0% to 2%, depending on your ecommerce platform and plan |
Your final price depends on your products, volume, card mix and markets, and it is confirmed in writing before you sign.
Your Card Mix Sets Most of the Cost
What your ecommerce credit card payment gateway really costs depends on card groups, and the gap between them is wider than the gap between most providers. The cost underneath each sale is interchange, which goes to the customer's bank. A store selling mainly to consumers in its own EEA market sits almost entirely in the cheapest group. A store selling internationally, or to other businesses, does not.
Card type | Interchange underneath |
|---|---|
EEA consumer debit card | 0.2%, capped by EU law |
EEA consumer credit card | 0.3%, capped by EU law |
Non-EEA consumer card, online | Up to 1.15% debit and 1.50% credit |
UK card sold to an EEA customer | 1.15% debit and 1.5% credit |
Business or corporate card | Not capped, often above 1.5% |
The EEA caps come from Regulation (EU) 2015/751. The non-EEA figures come from caps Visa and Mastercard agreed with the European Commission in 2019. Business cards were never capped, which catches out stores selling software, wholesale goods or services that companies buy on corporate cards. Knowing your own mix is what lets you judge any quote on the number you will actually pay.
UK to EU Sales After Brexit
After the UK left the EU, Visa and Mastercard raised interchange on online sales between the UK and the EEA from 0.2% and 0.3% to 1.15% and 1.5%. The UK's Payment Systems Regulator found this costs UK businesses an extra GBP 150 million to GBP 200 million a year. On 15 January 2026, the High Court confirmed the regulator's power to cap these fees, and the level of the cap is still being consulted on. Until it lands, the higher figures are a live cost for any UK store with EU customers.
Fixed Fees and Average Order Value
The fixed fee per transaction is easy to ignore, and that is a mistake for stores selling low-value items. EUR 0.10 on a EUR 120 basket is 0.08%. The same EUR 0.10 on a EUR 12 basket is 0.83%, more than half a typical headline rate again. Below roughly EUR 25 average order value, the fixed fee becomes something to negotiate. Above EUR 100, spend your attention on the percentage instead.
Flat Pricing and Interchange-Plus
Providers price in one of two ways. Flat pricing charges one rate, sometimes split by card type, and hides the underlying costs inside it. It is easy to budget and suits smaller stores. Interchange-plus passes the real interchange and scheme fees through and adds a fixed markup. It shows every cost line and usually works out cheaper at higher volume on a mostly domestic card mix. Stores with heavy cross-border sales often prefer flat pricing, because it caps what they pay on expensive foreign cards.
How Long Ecommerce Setup Takes
With a complete file, a payment gateway for an online store is usually live within 5 to 7 business days with our partners. This is the timeline they work to.
Stage | Typical time |
|---|---|
Quick assessment | 5 minutes |
Preliminary approval | 1 day |
Complete onboarding requirements | 15 minutes |
Provision of services | 3 days |
Total | 5 to 7 business days |
It can run a little longer when your website needs changes, but a week is the usual maximum. An ecommerce website payment gateway connected through a plugin or a hosted payment page can be live the day the credentials arrive. Our guide on how to add a payment gateway to your website covers that step.
Ecommerce Payment Gateway Services With Clear Pricing
Our partners' ecommerce payment gateway services come with every fee line in writing, priced on your real card mix.
- Priced on your card mix: not a headline rate that only fits one card type.
- No hidden fee lines: monthly, dispute and conversion fees listed upfront.
- Platform plugins covered: Shopify, WooCommerce, Magento and custom checkouts.
- Multi-currency settlement: get paid in the currencies you sell in.
- Regulated partners: licensed payment providers only.
Payment Gateway for Ecommerce Platforms
Your ecommerce platform affects the real cost of any payment gateway for ecommerce. Some platforms charge a fee on every sale you process through anyone else, and some change how much compliance work you carry. Neither shows up in a gateway quote, so check both when you price payment gateways for ecommerce. Most e-commerce payment gateways ship ready-made plugins for Shopify, WooCommerce and Magento.
Payment Gateways for Ecommerce on Shopify
Shopify charges a transaction fee on top of your provider's rate whenever you use a third-party gateway instead of Shopify Payments. That fee does not appear in the gateway's quote.
Shopify plan | Fee on third-party gateways | Shopify Payments online rate |
|---|---|---|
Basic | 2% | 2.9% plus 30 cents |
Grow | 1% | 2.7% plus 30 cents |
Advanced | 0.6% | 2.5% plus 30 cents |
Plus | 0.2% | Negotiated |
On Basic, the 2% platform fee usually makes Shopify Payments the cheaper option. From Grow upwards, a specialist gateway on a mostly domestic card mix usually costs less, and on Advanced and Plus the gap grows. Shopify Payments is also not available in every country, and where it is unavailable the third-party fee still applies, so check your registered country first.
Ecommerce Website Payment Gateway Integration
Open platforms such as WooCommerce and Magento let you connect any ecommerce website payment gateway with no platform fee. What they hand you instead is a choice about where card details are typed. A hosted or fully embedded checkout keeps card data on the provider's systems, which puts you in the lightest PCI DSS category, a short self-assessment. Building your own form and passing card data through your server moves you into a heavier category with quarterly scans. Take the hosted or embedded route unless you have a strong reason not to. Our guide to hosted vs third-party payment gateways explains the options.
Marketplaces and Multi-Vendor Stores
If money passes through you on its way to someone else, you are not running a normal checkout. You need split settlement, where the provider pays each seller directly, or you need a licence to hold client funds yourself. Ask about split payouts in the first conversation, not at integration. Our guides on how split payment gateways work and marketplace payment gateways cover the setup.
Ecommerce Payment Gateway Approval Rates
Stores negotiate rates hard and ignore approval rates, which is backwards. The approval rate is the share of attempted payments the customer's bank accepts, and the money it moves is far larger than the money in a rate negotiation.
What a Two Point Approval Gap Is Worth
Online card payments typically see approval rates between 85% and 92%, and cross-border cards run 5 to 15 percentage points below domestic ones. A store attempting EUR 500,000 of sales at an 88% approval rate collects EUR 440,000. At 90% it collects EUR 450,000. That two point gap is EUR 10,000 of revenue. Cutting your card rate by 0.3% on the same volume saves EUR 1,500. Ask any provider for its approval rate by card type and issuing country before you sign. E-commerce payment gateways report this number in different ways, so ask how it is calculated too.
SCA Exemptions and 3D Secure
Strong customer authentication applies to most online card payments in the EEA and the UK, and every challenge screen loses some customers. Exemptions help. Payments under EUR 30 can skip authentication until five exempt payments in a row or EUR 100 in total. Transaction risk analysis allows up to EUR 100, EUR 250 or EUR 500 depending on the acquirer's fraud rate. Customers can also whitelist a trusted merchant, and follow-on subscription charges fall outside the rules once the first payment was authenticated.
The catch is that an exempt payment gets no liability shift, so a fraud chargeback on it is yours. Use exemptions on low-value, low-risk orders and let the challenge run on the rest. Our guide to payment gateway security features covers the tools.
Retries, Network Tokens and Card Updater
Many card declines are recoverable. A proper retry reads the decline code, waits the right interval and does not keep hitting the bank. For subscription and repeat-purchase stores, network tokens and card updater services matter even more, because they refresh stored cards when customers get new ones. Without them, every expired card is a lost customer who never chose to leave.
Checkout data shows why this matters. Baymard Institute puts cart abandonment at around 70%, and among shoppers who left at checkout, 19% did not trust the site with their card, 17% found checkout too long, 10% had a card declined and 9% could not find the payment method they wanted. Read more: how to improve payment gateway success rates and smart routing and payment orchestration.
More Approved Sales From Your E-commerce Payment Gateway
A higher approval rate is worth more than a lower fee, so we set your checkout up to approve more sales.
- Approval reporting: approval rates by card type and country, not one blended figure.
- 3D Secure set up properly: exemptions on low-risk orders, challenges on the rest.
- Smart retries: recoverable declines retried the right way.
- Card updater: stored cards refreshed when customers get new ones.
- Local methods: the payment options each market expects.
- Support after launch: we stay with you after your first payout.
Ecommerce Payment Gateways for Cross-Border Sales
Selling into another country changes the card mix, the payment methods customers expect and the currency you are paid in. Ecommerce payment gateways handle this well or badly, and the difference shows in your conversion rate within a month.
Local Payment Methods Beat Cards Abroad
Cards are no longer the default in much of Europe. Digital wallets accounted for 56% of global ecommerce value in 2025, and in Germany wallets reached 52% of online value. In the UK, cards are down to 46% of online spending. In the Netherlands, iDEAL has historically taken around 92% of online payments. In Poland, BLIK processed over 420 million transactions in 2024. In Sweden, buy now pay later accounts for 23% of online transactions. Offering cards only means competing for a shrinking share of the market. Our guide to buy now pay later and e-wallet payment gateways covers these methods. The better payment gateways for ecommerce add each new method through the same integration.
Settlement Currency and FX Margin
Two currency conversions can happen on a cross-border sale, and both cost money. The first is at checkout, if you price in the customer's currency but settle in yours. The second is at payout, if your provider settles in a currency your bank does not hold. A 2% margin at each end can turn a low card rate into something far higher. Settle in the currencies you actually sell in and hold balances in them where you can. Our guides to how multi-currency payment gateways work and international payment gateways explain the setup.
Pricing in the Customer's Currency
Showing prices in the shopper's own currency usually lifts conversion by more than the conversion costs you. The mistake is letting the card networks do it at the point of sale through dynamic currency conversion, where the margin is high and the customer sees it. Price in local currency in your own catalogue, take the payment in that currency and convert once at settlement. Read more: how to accept international payments online.
Ecommerce Payment Gateway Solutions We Set Up
Our partners' ecommerce payment gateway solutions cover the full setup, not just the card rate: a merchant account with an acquirer that accepts your products, a gateway connected to your platform, local payment methods, multi-currency settlement, fraud and dispute tools, and a business account for your payouts. We put it together for you through Binderr Chooses, and each ecommerce payment gateway solution is built around your products and markets.
What Underwriters Check for Online Stores
Before approving a payment gateway for an online store, underwriters check the company and the website, running the same business verification checks payment firms are required to run. Expect to provide incorporation documents, details of anyone owning 25% or more, a passport and proof of address for each owner, and 3 to 6 months of bank statements. On the website, card scheme rules require your contact details, your country and your refund policy to be visible before checkout. Terms, privacy and shipping policies, prices in the right currency and a working SSL certificate are checked too. Our guide to payment gateway requirements lists every item.
Restricted Products and High Risk Stores
Stores selling supplements, CBD, vapes, alcohol, subscriptions with free trials or other restricted products need an acquirer that accepts those lines, and they usually pay more and hold a reserve. Our guide to high risk ecommerce merchant accounts covers that route. If a mainstream provider has already declined you, start with how to open a high risk merchant account.
Company and Banking First
For any payment gateway, ecommerce businesses need a registered company with a settlement account, so both have to exist before the gateway goes live. You can run all three at the same time rather than one after another. Our guides on setting up a company and how to open a business bank account cover the first steps.
A Payment Gateway for Ecommerce That Stays Open
A payment gateway for ecommerce is only worth having if it survives your busiest month, so we set it up to last.
- Your own merchant account: a dedicated account in your company name, not a shared one.
- Products declared upfront: your catalogue approved before you go live.
- Payouts agreed in writing: no surprise holds after a big sale.
- Chargeback alerts: refund before a dispute counts against you.
- One point of contact: no back-and-forth emails with several providers.
Common E-commerce Payment Gateway Mistakes
These are the mistakes stores make when they set up ecommerce payment gateways, in the order they usually happen.
Comparing Headline Rates
Headline rates on payment gateways for ecommerce apply to one card type. Work out your blended rate on last quarter's sales, including fixed fees, platform fees and currency conversion, or you are comparing nothing.
Ignoring the Platform Fee
A low gateway rate on Shopify Basic still carries the 2% third-party fee on top. Put the platform fee into the cost from the start.
Never Asking About Approval Rates
Two points of approval rate is worth several times a small rate cut on the same volume. Ask for the number by card type and country before you sign.
Launching Abroad on Cards Only
In the Netherlands, Poland and Belgium, the local method often beats cards. Check which methods your gateway supports in each market before you launch there.
Leaving the Company and Banking Until Last
Doing the company, the bank account and the gateway one after another adds weeks. Run them together so the same documents are used for each.
Apply Once for Your Online Store Payments
Apply once, and we choose the partner and prepare the file before anything is sent.
- One intake form: Binderr Chooses reads your store and picks the partner.
- Honest answer upfront: told what is realistic for your products first.
- No provider shopping: no comparing rates across a dozen sites.
- Documents handled: KYC pack, statements and policies prepared for you.
- Live in days: most stores take payments within 5 to 7 business days.
Bottom Line
Setting up a payment gateway for an online store is the easy part of taking payments online. What decides your real cost is your card mix, your platform's fees, your approval rate and how you handle currencies. When choosing a payment gateway, ecommerce stores should look past the headline rate. Work out your blended rate from your own sales, and ask about approval rates before you sign. The best ecommerce payment gateway solutions are the ones that still fit when your volume and markets grow.
We set your store up with a regulated payment partner, open the gateway and merchant account, connect your platform and handle the application, with most stores live within 5 to 7 business days. If you sell digital goods or run a game, our guides to payment gateways for digital products and payment gateways for video games and online gaming cover those setups.