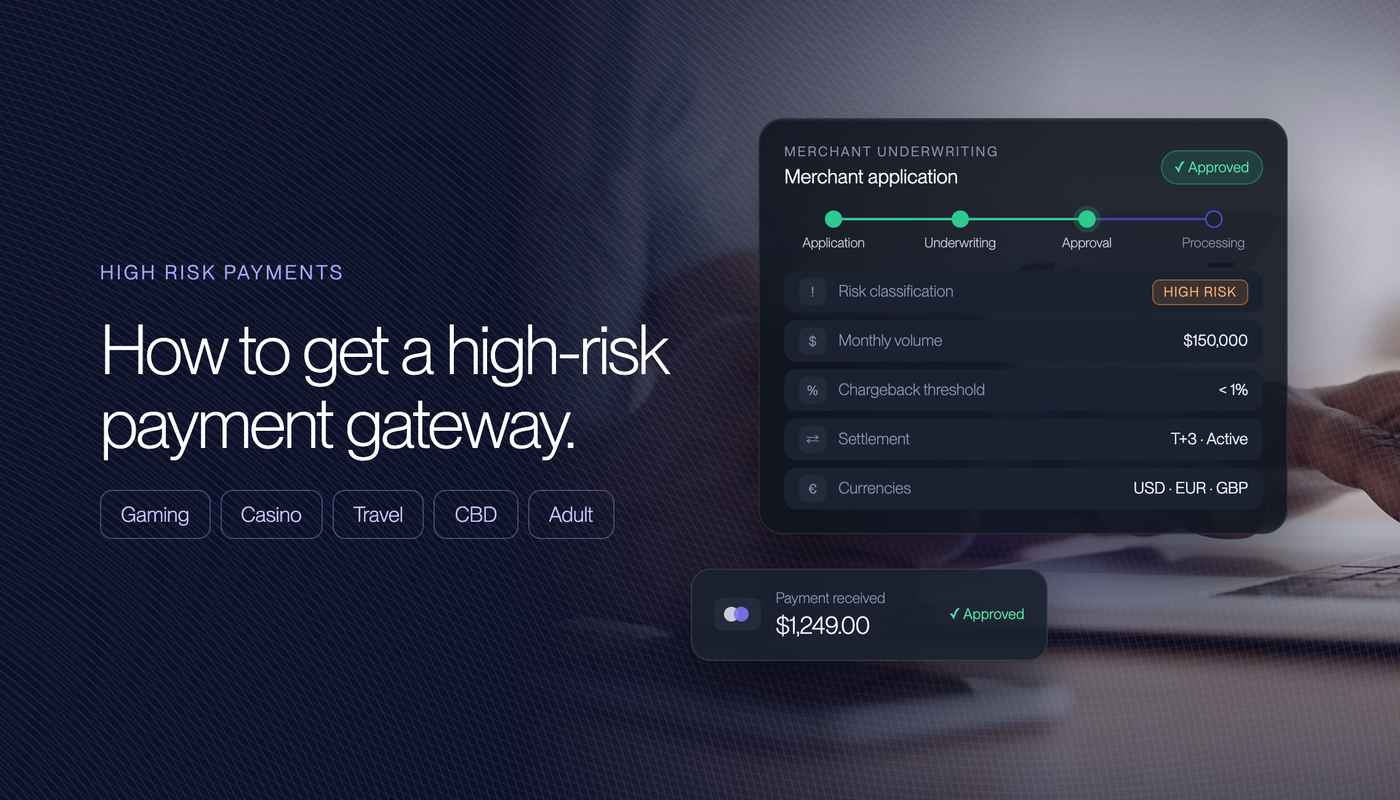
A high risk payment gateway connects your website to an acquirer that accepts your industry. It takes cards, wallets and local payment methods, supports 3D Secure, can route payments across more than one merchant account, and settles in USD, EUR, GBP, CAD and other major currencies.
Setting one up is harder than it looks. Stripe, PayPal and most plug-and-play gateways exclude sectors such as gambling, adult, CBD and nutraceuticals. A gateway on its own is also not an approval: it only works if a high risk acquirer sits behind it, and that acquirer runs its own underwriting.
Setting it up with us is simple. You fill in one intake form, and we match you with a regulated partner that provides the gateway and the merchant account together. We prepare your KYC pack, support the integration and stay with you until your first live payment. Most setups are done in 5 to 7 business days.
Get Fast Approval for a High Risk Payment Gateway
One application, and we match you with a regulated partner that already accepts your industry.
- Fast approval: a preliminary answer from our partner in about 1 day.
- Binderr Chooses: we pick the gateway partner for you, no shopping around.
- Gateway and account together: no separate acquirer to find.
- High risk accepted: gaming, adult, CBD, nutra, travel, peptides and more.
- Major currencies: settle in USD, EUR, GBP, CAD and more.
- KYC pack prepared: your documents ready before underwriting starts.
How High Risk Payment Gateways Work
High risk payment gateways do the same job as any gateway: they capture the card details at checkout, check them, and send the payment to the acquirer for authorisation. The difference is what sits behind them. A high risk payment gateway is connected to an acquirer that has underwritten your industry, and it carries the tools high risk merchants need, such as 3D Secure, fraud screening and routing across several merchant accounts.
Gateway, Acquirer and Merchant Account
The gateway sends and authorises payments. The merchant account, held with the acquirer, is where the money settles before it is paid out to your business bank account. You need both. This is the part many guides skip: a gateway that works perfectly is worth nothing if the merchant account behind it is not approved for your sector. The acquirer will close the account, and the gateway stops with it.
If you are new to the terms, start with our guide on what a high risk payment gateway is. The merchant account side is covered in our guide on how to open a high risk merchant account.
Your High Risk Gateway Merchant Account
Your high risk gateway merchant account is the merchant ID, or MID, the acquirer opens for you. Each MID has its own rate, reserve, monthly limit and approved countries, so each high risk gateway merchant account is underwritten on its own. The gateway uses the MID to tell the acquirer which account a payment belongs to. When we set up a high risk payment gateway, the MID is approved first and the gateway is configured around it, not the other way round.
Why High Risk Gateways Use More Than One MID
High risk gateways often connect to several merchant accounts at once, and this is one of the main ways high risk gateways differ from consumer ones. Load balancing splits your volume between MIDs by a monthly cap or a percentage, so no single account carries all the risk or hits its limit early. Cascading sends a declined payment to a second MID within the same payment attempt, which recovers sales that would otherwise be lost.
Multiple MIDs are a normal tool for growing high risk merchants, but they must be honest. Each MID must be opened in the name of the real business with the right merchant category code. Our guide on smart routing and payment orchestration explains how routing works in practice.
What a Payment Gateway for High Risk Merchants Needs
A payment gateway for high risk merchants needs more than a checkout. Look for 3D Secure on every card flow, built-in fraud screening, chargeback alerts, recurring billing with card updates, routing across more than one MID, settlement in several currencies and clear reporting on disputes and refunds. These are the tools that keep your ratios inside card scheme limits.
Good high risk payment gateways also support the payment methods your customers use. Depending on your markets, that can include Apple Pay and Google Pay, bank transfers, open banking and local methods. Every extra method is a way to take a sale that a declined card would have lost. If your market is gaming, our guides on gaming payment gateways and how casino payment gateways work cover the sector detail.
High Risk Payment Gateway and Merchant Account
Binderr Chooses
Time to onboard
5 to 7 days
Currencies
USD, EUR, GBP and more
Industries
Gambling, Adult, CBD, Crypto, Travel, Forex and more
Why Mainstream Gateways Decline High Risk Businesses
Most mainstream gateways are built around their own merchant account, so their terms decide who can use them. In high risk industries, payment gateways from the big consumer brands are usually not available at all, or are available until the first review. That is the gap high risk payment gateways fill.
Restricted Industry Lists
Stripe's restricted businesses list, updated in May 2026, prohibits adult content, gambling, weapons, nutraceuticals, marijuana and some travel services, among others. PayPal requires pre-approval for gambling, crypto, prescription drugs, telemedicine, adult content, dating and tobacco. For an online payment gateway, high risk sectors on these lists are simply out of scope. When you pick an online payment gateway, high risk status has to be accepted in writing, not assumed. Our guide on whether Stripe and PayPal allow high risk merchants covers both lists.
Card Scheme Registration for High Risk Merchants
Visa and Mastercard also require acquirers to register certain high risk merchants. Visa's Integrity Risk Program, in force since 1 May 2023, covers categories such as gambling, dating, online pharmacies, crypto and inbound telemarketing, and Visa's registration fee is USD 950 per merchant. An acquirer that fails to register a merchant in the top tiers faces fines of up to USD 100,000 a month.
That is why a mainstream gateway will not simply act as a payment gateway for high risk business such as gambling or pharmacy: its acquirer would need to register it, monitor it and carry the fines if it goes wrong. A high risk payment gateway is built on acquirers that do this every day. See Visa and Mastercard high risk merchant registration for the full rules.
Read more: high risk merchant services and solutions.
Get a High Risk Payment Gateway Without Rejection
Most declines come from applying to a gateway whose acquirer excludes your sector. We only send your file where it fits.
- No blind applications: your file goes only to a partner that accepts your industry.
- Registration handled: card scheme registration sorted by the acquirer, not you.
- Clean record kept: no string of declines that follows you around.
- Pre-screened fit: your model is checked before anything is submitted.
- Backup route ready: a second partner if the first asks for more.
How to Set Up a High Risk Payment Gateway
To set up a high risk payment gateway, you need a registered company, a business bank account, a compliant website and an approved merchant account behind the gateway. Then you integrate the gateway, test it and go live. With the right partner, the whole setup takes less than a week.
Set Up the Company and Bank Account First
Gateways and acquirers approve companies, not individuals. You need a registered entity, its incorporation documents and a business bank account in the company's name to receive payouts. Choose a jurisdiction your acquirer supports and keep the company, the bank account and the website consistent. A mismatch between them is one of the most common reasons a file stalls.
Get Your Website Ready for Review
Underwriters check your website before they approve a high risk merchant payment gateway. Visa's rules require a customer service email or phone number, your company's country, and a refund policy shown before checkout with a box the customer ticks to accept it. Acquirers also look for clear terms, a privacy policy, shipping and cancellation terms, prices in the right currency and card logos.
Check that every product on the site matches what you declare on the form. A site that sells something the application does not mention is the fastest way to a decline. Most website gaps take an hour to fix, and fixing them first saves days of back-and-forth. If you are new to gateways in general, our guide on how to set up an online payment gateway covers the basics.
Apply for a High Risk Business Payment Gateway
Most founders lose weeks here, filling in separate forms for several gateways and collecting declines. With Binderr you apply once. Our intake form, Binderr Chooses, asks about your business model, volume, markets and history, and we match you with a regulated partner that provides the high risk business payment gateway and the merchant account together. You do not need to research providers or compare offers.
For a payment gateway, high risk business owners often assume the rate is what decides the choice, and when they compare a payment gateway, high risk business needs such as sector approval come second. The real decision is which acquirer accepts your sector and your markets. That is what the matching does.
Pass Underwriting on the First File
Underwriting checks the company, its owners, its products, its website and any past processing. Expect to provide incorporation documents, owner IDs and proof of address, 3 to 6 months of bank and processing statements if you have them, and any licence your sector needs. Our partners give a preliminary decision in about 1 business day when the file is complete, which is the fastest way to get a high risk business payment gateway approved. Our guide on how to get approved for a high risk merchant account explains what underwriters look for.
High Risk Payment Gateway Integration
Once the merchant account is approved, you receive gateway credentials for your high risk merchant account payment gateway and choose how to connect. Most merchants use a hosted payment page or a plugin, which is the fastest high risk payment gateway integration. Larger merchants use the API for full control of the checkout. The options are explained in the next section.
Test Transactions and Going Live
Before going live on your high risk online payment gateway, run test payments in the sandbox: an approved card, a declined card, a 3D Secure challenge, a refund and a partial refund. Check that your billing descriptor shows your trading name, that receipts are sent and that payouts reach the right account. Then switch to live credentials and take a small real payment to confirm everything settles.
Set Up a High Risk Merchant Payment Gateway
Our partners work to a clear timeline, and most high risk merchants are live in 5 to 7 business days.
- Quick assessment: a 5 minute intake form tells us where you fit.
- Preliminary approval: a first answer in about 1 day.
- Onboarding in minutes: the remaining requirements take about 15 minutes.
- Live in days: services provisioned in about 3 days.
- Integration support: help with the hosted page, plugin or API.
- One point of contact: one person from application to first payment.
Integration Options for a High Risk Merchant Gateway
A high risk merchant gateway can be connected in three main ways, and high risk payment gateways generally support all three. The right one depends on your platform, your team and how much of the PCI compliance work you want to carry.
Hosted Payment Page
With a hosted payment page, the customer enters card details on a page run by the gateway, either by redirect or inside an embedded frame. Your servers never touch the card data. That keeps you in the smallest PCI scope, usually the short self-assessment questionnaire known as SAQ A. It is the fastest way to go live and the right starting point for most high risk merchants. In high risk industries, payment gateways with hosted pages also reduce your exposure if something goes wrong on your own site.
Direct API Integration
With a direct API, you build the checkout yourself and send card data to the gateway from your own systems. You get full control over the design and the payment flow, but you also take on far more PCI work, usually the full SAQ D. Under PCI DSS v4.0.1, the requirements that were future-dated became mandatory on 31 March 2025, so the compliance workload for a self-built checkout is higher than it was. Most merchants should only move to the API once volume justifies it. Our guide on hosted vs third-party payment gateways compares the two in more detail.
Plugins for Shopify and WooCommerce
If you run an online store, a plugin is often the quickest route. WooCommerce stores can usually install the gateway's plugin and connect in an afternoon. Shopify is stricter about third-party gateways and charges an extra fee when you do not use its own payments product. Our guides on high risk payment processors for Shopify and high risk payment gateways for WooCommerce cover each platform.
High Risk Payment Gateway and Merchant Account
Binderr Chooses
Time to onboard
5 to 7 days
Currencies
USD, EUR, GBP and more
Industries
Gambling, Adult, CBD, Crypto, Travel, Forex and more
Security, 3D Secure and SCA
A high risk payment gateway must protect you from fraud as well as take payments. Fraud reports count against you in Visa's monitoring program, so a secure checkout is also what keeps your account open. The best high risk payment gateways treat security as part of approval, not an add-on.
3D Secure and Strong Customer Authentication
In the European Economic Area, the PSD2 rules on strong customer authentication require most online card payments to be confirmed with two of three factors: something the customer knows, has or is. EMV 3D Secure is how this works at checkout. Low value payments under EUR 30 can be exempt. When a payment is authenticated with 3D Secure, fraud liability usually shifts from you to the card issuer, which is a major benefit for high risk merchants.
When a High Risk 2D Payment Gateway Makes Sense
A high risk 2D payment gateway processes cards without the 3D Secure step. Checkout is faster and conversion can be higher, but you keep the fraud liability. It is mainly used for traffic from outside the EEA, for phone and mail orders, and for trusted repeat customers. The safest setup uses 3D Secure by default and 2D only where it is allowed and the risk is low. Read more: secure payment processing for high risk merchants and payment gateway security features.
Get a Secure High Risk Online Payment Gateway
A secure checkout keeps fraud down and your account open. Our partners build it in from day one.
- 3D Secure ready: SCA-compliant checkout for EEA cards.
- Fraud screening: suspect payments stopped before they count against you.
- Lower PCI scope: hosted pages keep card data off your servers.
- Smart routing: payments spread across more than one MID where needed.
- Regulated partners: licensed acquirers only, no grey-market processors.
What a High Risk Payment Gateway Costs
A high risk payment gateway costs more to run than a standard one, mostly because of the merchant account behind it. The gateway fee itself is small. The processing rate, the reserve and the chargeback fees are where the money goes. The ranges below are typical market figures on the lower side, taken from published industry guides in 2026.
Cost item | Typical range |
|---|---|
Setup or application fee | $0 to $500, one-off |
Gateway monthly fee | $10 to $30 |
Gateway fee per transaction | $0.05 to $0.15 |
Processing rate | 2.5% to 5% of each sale |
Processing fee per transaction | $0.10 to $0.35 |
Chargeback fee | $15 to $35 per dispute |
Rolling reserve | 5% to 10% of sales, held 90 to 180 days |
PCI compliance | $99 to $200 a year |
For comparison, low risk businesses usually pay 1.5% to 2.9% per sale. On USD 50,000 of monthly sales, the gateway itself might cost USD 30 to USD 100 a month, while the processing rate costs USD 1,250 to USD 2,500 and a 10% reserve holds USD 5,000 of cash each month. That is why the whole package matters more than the gateway line.
Your final pricing depends on your industry, volume, chargeback history and markets, and it is confirmed in writing before you sign. Payment gateways for high risk business are priced as a package, so compare the package. Our guide on high risk merchant account fees and rates breaks down every line.
Read more: credit card processing for high risk merchants and high risk ACH payment processing.
High Risk Payment Gateway and Merchant Account
Binderr Chooses
Time to onboard
5 to 7 days
Currencies
USD, EUR, GBP and more
Industries
Gambling, Adult, CBD, Crypto, Travel, Forex and more
How Long High Risk Payment Gateway Setup Takes
With a complete file, most high risk payment gateways are live in 5 to 7 business days with our partners, and the same timeline applies to a high risk merchant payment gateway for a new business. Banks and some specialist gateways take several weeks. This is the timeline our partners work to.
Stage | Typical time |
|---|---|
Quick assessment | 5 minutes |
Preliminary approval | 1 day |
Complete onboarding requirements | 15 minutes |
Provision of services | 3 days |
Total | 5 to 7 business days |
Integration time comes on top and depends on the method. A hosted page or plugin can be ready the same day the credentials arrive. A custom API build takes longer. Delays almost always come from missing documents or a website that fails review, so send a complete file on day one.
Get a Payment Gateway for a High Risk Business
One intake form, one matched partner, and a gateway that stays open because your sector was approved upfront.
- Built for high risk: the acquirer underwrote your sector, so no surprise shutdowns.
- Reserve agreed upfront: terms set before you sign, not imposed later.
- Cards and wallets: Visa, Mastercard and alternative payment methods.
- Clear pricing: every fee shown in writing before you sign.
- Handled end to end: from application to your first live payment.
Keeping Payment Gateways for High Risk Merchants Running
Payment gateways for high risk merchants are monitored closely, both by the acquirer and by the card schemes, and high risk payment gateways share their data with the acquirer every day. The account stays open as long as your fraud and dispute levels stay inside the limits.
Chargeback Limits That Close Accounts
Visa's Acquirer Monitoring Program adds fraud reports and disputes together and divides them by settled transactions. Since 1 April 2026, merchants at 1.5% or more with at least 1,500 fraud reports and disputes in a month are flagged as excessive in the US, Canada, Europe and Asia Pacific, with fees reported at about USD 8 per case. Mastercard flags merchants at 1.5% and 100 chargebacks in a month, with fines starting at USD 1,000 and rising to USD 100,000 a month if the problem runs for 19 months.
Most acquirers act well before those limits. Treat 1% as your ceiling. An account closed for excessive chargebacks can land on the MATCH list for 5 years. See what the Mastercard MATCH list is.
Descriptors, Alerts and Refunds
Many disputes come from customers who do not recognise the charge. Use a billing descriptor with your trading name and a contact, send clear receipts, and send reminders before subscription renewals. Chargeback alerts let you refund before a dispute is filed, and a quick refund costs far less than a chargeback. Our guides on chargeback management for high risk merchants and payment gateway fraud detection cover the tools.
Never Change Merchant Data to Hide Risk
Some operators try to stay under the limits by changing merchant details or using the wrong merchant category code. Visa's rules treat this as a serious breach, with fines of USD 25,000 per merchant per month and possible disqualification. It also ends the relationship with the acquirer. Honest data and honest MIDs are the only setup that lasts.
High Risk Payment Gateway and Merchant Account
Binderr Chooses
Time to onboard
5 to 7 days
Currencies
USD, EUR, GBP and more
Industries
Gambling, Adult, CBD, Crypto, Travel, Forex and more
Business Bank Account for Gateway Payouts
Your gateway pays out to a business bank account, and that account has to accept your industry too. Many local banks decline high risk sectors or close the account once card payouts start arriving, which leaves an approved gateway with nowhere to send the money.
We open the settlement account alongside the gateway, with regulated banking partners that accept high risk sectors. You get real IBANs, multi-currency balances and no minimum balance. Read our guide on how to open a high risk bank account.
Open a Business Bank Account for High Risk Payouts
Your gateway needs a settlement account that accepts your sector. We open it alongside your merchant account.
- Payouts land safely: an account that accepts your industry.
- Real IBANs: EUR and multi-currency accounts from day one.
- Opened fast: your account ready in about a week.
- No minimum balance: no idle cash locked up.
- Same team: one contact for payments and banking.
Common High Risk Payment Gateway Mistakes
Most failed setups and closed accounts come from a handful of mistakes. Each one is easy to avoid if you know it before you start.
Using a Gateway Without a High Risk Acquirer
Some merchants connect a popular gateway, start selling and assume they are approved. If the acquirer behind it does not accept the sector, the account is closed at the first review, often with funds held. Always confirm that the merchant account behind your gateway was approved for your industry.
Using the Wrong Merchant Category Code
A merchant category code that does not match what you sell may get you approved faster, but it breaks card scheme rules and puts the whole account at risk. When it is found, the account is usually closed and the merchant can end up on the MATCH list. Declare your real business from the start.
Skipping 3D Secure on EEA Cards
Turning off 3D Secure to lift conversion leads to declines on EEA cards under SCA rules and leaves you with the fraud liability. Fraud reports then push up your VAMP ratio. Keep 3D Secure on by default and use exemptions properly.
Building a Full API Too Early
A custom API checkout looks professional, but it moves you into the full PCI questionnaire and adds weeks to setup. Most high risk merchants should start with a hosted page or plugin, prove the account, and build a custom checkout later if the volume justifies it.
Relying on a Single MID
With one merchant account, a single bad month or a hit monthly limit can stop all your sales. Growing merchants should plan for a second MID and routing once they have steady volume, so a problem on one account does not stop the business. Read more: international and offshore high risk payment gateways.
Get a High Risk Merchant Account Payment Gateway
Skip every mistake above. We handle the partner, the file and the introduction.
- One intake form: a single application instead of five.
- We choose for you: the partner picked on your sector, volume and markets.
- Honest answer upfront: told what is realistic before you apply.
- Ongoing support: help when your volume or model changes.
- No back-and-forth emails: one person who gets it done.
Read more: what a payment gateway is and the list of high risk merchant industries and MCC codes.
Bottom Line
A high risk payment gateway is only as good as the acquirer behind it. Stripe, PayPal and most consumer gateways exclude the sectors that need one, and a gateway that is not backed by an approved merchant account will not last.
Choosing an online payment gateway, high risk merchants should look past the brand and check the acquirer. The route that works is simple: get the company, bank account and website ready, apply once to a partner that accepts your industry, start with a hosted page or plugin, keep 3D Secure on and keep chargebacks under 1%. We handle the matching, the KYC pack and the introduction, and most merchants are taking live payments in 5 to 7 business days.