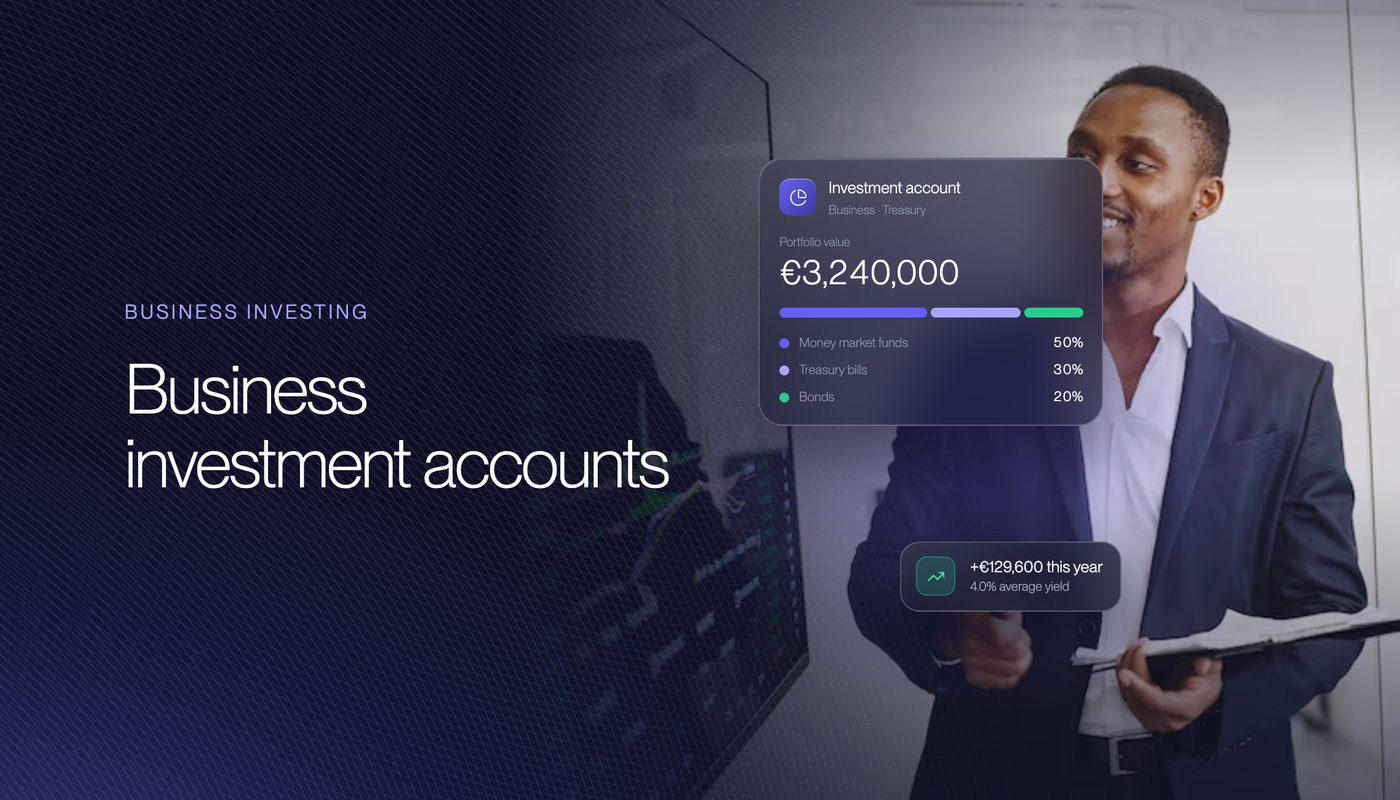
A business investment account lets your company hold securities such as money market funds, Treasury bills and government bonds in its own name. Cash the business does not need this quarter can earn a market rate while it stays in the company's name, ready to sell whenever you need the money back.
The hard part is the setup. A corporate investment account needs company documents, checks on directors and owners and an active LEI, and getting all three ready takes time if you start late. Meanwhile euro area banks paid companies an average of 0.61% on overnight deposits in August 2026.
This is where we come in. We introduce your company to Sophic, a service of Athlos Capital Investment Services Ltd, a CySEC-regulated investment firm. You choose the instruments and amounts. Sophic executes your orders and holds the investments. We check that you qualify and prepare the onboarding with you.
Open a Business Investment Account for Company Cash
An investment account with Sophic in your company's name. We prepare the onboarding with you, and you choose the instruments and amounts.
- Money market funds: Currently from 2% p.a. before fees, a variable return that can fall.
- Treasury bills: Currently from 2.5% p.a. before fees, repaid at maturity.
- Government bonds: Currently from 3% p.a. before fees, with regular interest.
- Your company's name: Holdings are held for the company, not for a director.
- Digital onboarding: About a day, then invested 2 to 3 business days later.
- No lock-in: Sell when you need cash, at the market price.
When investing, your capital is at risk. Yields may vary.
Sophic
Treasury management
Yield
2% to 3%+ p.a
Fees
0.3% a year + €10 per order
Eligibility
EU/EEA businesses with an LEI
When investing, your capital is at risk. Yields may vary.
What Is a Business Investment Account
A business investment account is an account with an authorised investment firm that holds securities, such as funds, bills and bonds, in a company's name. It is not a bank deposit. An investment account for business works like a personal one, but in the company's name, with company documents and directors' approval behind every order. The company buys and sells through the firm, and a custodian holds the assets apart from the firm's own.
How It Differs From a Business Savings Account
A savings account is a bank deposit: the bank owes you the balance plus interest, and the deposit guarantee covers €100,000 per bank. A business investment account holds securities instead. Their value can move, they are not covered by the deposit guarantee, and repayment depends on the issuer or the fund's holdings rather than on the bank. Our guide to the best business savings account covers the deposit side.
Who Holds the Assets
MiFID II requires investment firms to protect clients' ownership rights in their securities and money, and to keep them apart from the firm's own assets (Article 16(8) and (9)). In practice the securities sit with a custodian and client cash in segregated accounts at a bank. With Sophic, client cash is held in segregated accounts at J.P. Morgan and investments are safeguarded by SIX Group.
What a Corporate Investment Account Can Hold
What a corporate investment account can hold depends on the firm. Some offer shares and corporate bonds. Others focus on cash-like instruments. Sophic offers money market funds in EUR, GBP and USD, Treasury bills from the EU, Germany, France, Cyprus, the UK and the US, and government bonds from the same issuers plus Greece and Spain.
Who Can Open a Company Investment Account
Any company with legal capacity to hold investments can open a company investment account, subject to the firm's checks. The firm will look at where the company is incorporated, its sector, its owners and its documents, classify it as a retail or professional client and ask for an LEI before it can trade bills or bonds.
Limited Companies and Holding Companies
A limited company investment account is opened in the company's name, with directors authorised to place orders under a board resolution. Holding companies often use one for dividends from subsidiaries or the proceeds of a sale. Holding companies may need additional checks before onboarding. Our guide to opening a bank account for holding companies covers the banking side.
Retail or Professional Client
Under MiFID II, a company is treated as a professional client by default only if it meets two of three tests: a balance sheet total of €20,000,000, net turnover of €40,000,000 and own funds of €2,000,000 (Annex II). Most small and mid-sized companies are retail clients, which gives them the fullest information and protection rules. A small business investment account is usually a retail one.
You Need an LEI
EU investment firms cannot buy Treasury bills or bonds for a company without a Legal Entity Identifier (Article 13(2) of Delegated Regulation (EU) 2017/590). Buying fund shares directly from a fund's administrator is not covered by that rule, but Sophic asks for an active LEI at onboarding. See how to get an LEI number.
Sophic
Treasury management
Yield
2% to 3%+ p.a
Fees
0.3% a year + €10 per order
Eligibility
EU/EEA businesses with an LEI
When investing, your capital is at risk. Yields may vary.
Documents for a Corporate Investment Account
Opening a corporate investment account needs much the same documents as a business bank account. The firm checks that the company exists, who runs it, who owns it and where its money comes from. Having the set ready before you apply is the quickest way to cut onboarding time.
- Certificate of incorporation: Proof the company exists, plus any change of name.
- Articles of association: To confirm the company can hold investments.
- Registers of directors and shareholders: Current versions, certified if asked.
- Beneficial owner details: Everyone owning or controlling 25% or more, with ID and proof of address.
- Board resolution: Approving the account and naming who can place orders.
- Active LEI: The 20-character code, with its renewal date.
- Source of funds: A short explanation of where the cash to be invested comes from.
The list matches what banks ask for, as our guide to the documents needed to open a business bank account shows. If any document is old, refresh it before you apply.
Why the Firm Asks About Source of Funds
Investment firms must run anti-money laundering checks on every client, as banks do. They ask where the cash comes from, such as trading profits, a funding round or the sale of a subsidiary, and may ask for evidence. A clear one-paragraph answer with a recent bank statement usually settles it. Our guide to business bank account requirements explains the same checks on the banking side.
Keep Your LEI Current
An LEI must be renewed every year, and a lapsed one can block new orders on bills and bonds. Check its status before you apply and put the renewal date in the finance calendar. Our guide to LEI renewal covers the process.
Corporate Investment Account Setup Done With You
We check whether your company qualifies for Sophic and prepare the file with you, so nothing is missing when you apply.
- Eligibility checked first: Country, sector and LEI checked before any paperwork.
- One document list: Everything onboarding needs, asked for once.
- Beneficial owners covered: We tell you exactly what each owner needs to provide.
- Three currencies: Money market funds in EUR, GBP or USD.
- One point of contact: We stay with you until onboarding is complete.
When investing, your capital is at risk. Yields may vary.
Business Investment Account vs Savings Account
A business investment account and a savings account suit different cash. A savings account gives deposit guarantee cover up to €100,000 per bank and a known rate. An investment account holds funds, bills and bonds that pay a market rate with no lock-in, but are not covered by the guarantee and can move in value.
Factor | Business savings account | Money market fund | Treasury bills | Government bonds |
|---|---|---|---|---|
Current rate | 0.75% on demand, 2.25% fixed for 12 months (permanent tsb, July 2026) | Currently from 2% p.a. before fees, variable and can fall | Currently from 2.5% p.a. before fees | Currently from 3% p.a. before fees |
Access to cash | Same day, or after the notice period or term | Usually the same day or the next | At maturity, or sold early at the market price | At maturity, or sold early at the market price |
Lock-in | None on demand accounts, yes on fixed terms | None | None, but the price moves if sold early | None, but the price moves if sold early |
Deposit guarantee cover | Up to €100,000 per bank | Not covered | Not covered | Not covered |
Main risk | The bank's balance sheet above €100,000 | Value can fall, rare limits on redemptions | Price change before maturity | Price change before maturity, larger for longer bonds |
The table shows why many companies use both. A savings account holds cash under the guarantee limit or cash needed at a fixed date. A business investment account holds the larger balances above it. Fund, bill and bond figures are Sophic's current starting yields, before fees. When investing, your capital is at risk. Yields may vary.
The Business Investment Savings Account Label
Some banks sell a "business investment savings account" that is really a notice or fixed deposit with a higher rate. Others use the name for an account that holds funds. Before you open one, ask a single question: is this a bank deposit covered by the guarantee, or are these securities held for me? The answer decides the risk and the protection.
When a Savings Account Still Makes Sense
A savings account suits balances under €100,000 per bank, cash needed on a set date within the term and companies that do not yet have an LEI. Offshore centres offer them too, as our guide to business savings accounts in Guernsey shows. Our guide to short-term investments for business cash compares the options in depth.
Sophic
Treasury management
Yield
2% to 3%+ p.a
Fees
0.3% a year + €10 per order
Eligibility
EU/EEA businesses with an LEI
When investing, your capital is at risk. Yields may vary.
How a Business Investment Account With Sophic Works
A business investment account with Sophic is opened online in the company's name. You choose the instruments and amounts. Sophic executes your orders and holds the investments. Onboarding takes about a day, money is invested 2 to 3 business days later and there is no lock-in period.
What You Can Hold
Money market funds in EUR, GBP and USD are currently from 2% p.a. before fees, with a variable return that can fall. Treasury bills from the EU, Germany, France, Cyprus, the UK and the US are currently from 2.5% p.a. before fees. Government bonds are currently from 3% p.a. before fees. Yields may vary. Sophic does not offer shares.
How Your Investments Are Held
With Sophic, client cash is held in segregated accounts at J.P. Morgan and investments are safeguarded by SIX Group. Bills and bonds are claims on the issuing government, so repayment depends on that government rather than on a single bank's balance sheet.
Which Companies Sophic Onboards
Sophic onboards businesses incorporated in Cyprus, Austria, Belgium, Bulgaria, Estonia, France, Germany, Greece, Ireland, Italy, Luxembourg, Portugal, Slovenia, Spain and Switzerland. Companies also need an active LEI, proof of legal existence and a sector Sophic accepts. Holding companies may need additional checks before onboarding. If you are still forming the company, see holding company formation in Cyprus or our Ireland company formation guide.
Read more: How Sophic works for businesses.
Business Investment Account UK Options
Sophic does not onboard companies incorporated in the UK, so a UK company looking for a business investment account usually opens one with a firm authorised by the FCA. Eligible companies in the countries Sophic covers can still hold UK Treasury bills and sterling money market funds through a Sophic account.
UK Companies Use FCA-Authorised Firms
A corporate investment account in the UK is opened with a firm on the FCA's register, which runs the same kind of company, director and owner checks. Check the firm's legal name and permissions on the FCA register before applying. A UK company still needs a UK operating account first, as our guide to the UK business bank account explains.
Holding UK Treasury Bills and Sterling Funds
Eligible companies can hold UK Treasury bills and money market funds in GBP through Sophic, alongside euro and dollar holdings. For UK companies themselves, our guide on how to set up a UK holding company covers group structures.
Put Company Cash Into Funds, Bills and Bonds
For eligible companies with cash that has no job for months. You decide how to split cash between funds, bills and bonds. Sophic executes your orders and holds the investments.
- Fund returns: Money market funds currently from 2% p.a. before fees, variable.
- Bill returns: Treasury bills currently from 2.5% p.a. before fees.
- Bond returns: Government bonds currently from 3% p.a. before fees.
- Familiar issuers: Bills and bonds from the EU, Germany, France, Cyprus, the UK and the US.
- Segregated client cash: Held in segregated accounts at J.P. Morgan.
- Safeguarded investments: Safeguarded by SIX Group.
When investing, your capital is at risk. Yields may vary.
Corporate Investment Account Taxation
Corporate investment account taxation follows the company, not the account. Interest, fund income and gains on bills and bonds are normally taxed as part of the company's profits, under the rules of the country where it is resident. Rates for passive income can differ from trading rates, so check before you invest.
Investment Income Is Taxed in the Company
The company reports the income and gains in its own tax return. A director who invests company money does not pay personal tax on it, unless the money is later paid out as salary or dividends. Foreign government bonds can also carry withholding tax at source, which may be reclaimable under a tax treaty.
Passive Income Can Carry a Different Rate
In Ireland, non-trading income such as interest is taxed at 25%, against 12.5% for trading income. In the UK, the main corporation tax rate is 25% on profits above £250,000 and the small profits rate is 19% on profits of £50,000 or less. Take local tax advice. Our guides to tax planning for business owners and the lowest corporate tax in Europe cover the wider picture.
Keep Records for the Tax Return
Keep the firm's statements of every purchase, sale, coupon and fund distribution. Your accountant needs them to calculate gains and income at the year end. A personal investment company is a different structure with its own rules, so do not mix the two.
Sophic
Treasury management
Yield
2% to 3%+ p.a
Fees
0.3% a year + €10 per order
Eligibility
EU/EEA businesses with an LEI
When investing, your capital is at risk. Yields may vary.
Costs of a Business Investment Account
A business investment account usually costs a yearly fee on the invested balance, a fee per order, the ongoing charges of any fund you hold and the dealer spread on bills and bonds. Add the yearly LEI renewal fee. The card on this page shows Sophic's fees. Ask any firm for every cost in writing before you open an account.
Fixed Fees Matter More on Small Amounts
A fixed fee per order weighs more on a small purchase than a large one. Fewer, larger orders spread the fixed fee further.
Compare the Total With What the Bank Pays
The cost only makes sense next to the alternative. In August 2026, euro area banks paid companies an average of 0.61% on overnight deposits and 2.24% on deposits fixed for up to a year. Our guide to business treasury management covers where the account fits.
Common Business Investment Account Mistakes
Most business investment account mistakes happen before the first order. Companies apply with old documents, let the LEI lapse, invest money they need soon or open an account that turns out to be a deposit with a new name. Each one costs time or return, and each one is easy to avoid.
Applying With Out-of-Date Documents
An old shareholder register or a missing beneficial owner is the most common reason onboarding stalls. Refresh every document before you apply, and check that names match across the registers, the articles and the ID copies. Use our LEI search guide to confirm your LEI record matches too.
Letting the LEI Lapse
A lapsed LEI can block new orders on bills and bonds. Renewal is yearly and easy to miss when nobody owns it. Put it in the finance calendar with a reminder a month ahead.
Investing Cash Needed Soon
A business investment account is for cash with no job for months. Putting next month's payroll into a 6-month bill forces a sale at the market price if cash runs short. Keep operating cash and a reserve in the bank first.
Not Asking Whether It Is a Deposit
"Investment account" means different things at different banks. If you do not ask whether the money is a deposit or securities, you may end up with less protection than you assumed, or more lock-in than you wanted. Get the answer in writing.
Bottom Line
A business investment account holds funds, bills and bonds in the company's name, outside the deposit guarantee but in segregated custody. Get your documents and LEI ready, check whether you are a retail or professional client and keep operating cash in the bank. Sophic onboards eligible companies in 15 countries, with no lock-in.
What is a business investment account?
What is a corporate investment account?
Can a limited company have an investment account?
What is the difference between a business investment account and a savings account?
What is a business investment savings account?
What can I hold in a company investment account?
What documents do I need to open a corporate investment account?
Do I need an LEI for a business investment account?
Is a business investment account protected?
How is a corporate investment account taxed?
Can a UK company open a business investment account with Sophic?
What is a small business investment account?
How much does a business investment account cost?
Sources
- European Central Bank, Euro area bank interest rate statistics, August 2026 (released 1 October 2026)
- permanent tsb, Non-personal deposit interest rates effective 7 July 2026
- Directive 2014/65/EU on markets in financial instruments (MiFID II), Article 16 and Annex II, EUR-Lex
- Commission Delegated Regulation (EU) 2017/590 (RTS 22), EUR-Lex
- GLEIF, Introducing the Legal Entity Identifier (LEI)
- Directive 2014/49/EU on deposit guarantee schemes, EUR-Lex
- Regulation (EU) 2017/1131 on money market funds, EUR-Lex
- Local Enterprise Office Fingal, Understanding Taxes (Irish corporation tax rates)
- GOV.UK, Corporation Tax rates and allowances
Binderr is not an investment provider or adviser. We connect businesses with regulated investment providers and help with the setup. Every investment is made under the provider's own terms, fees and risk disclosures, which you review and accept directly with them, and the decision to invest is yours. Binderr is not responsible for investment performance or for any loss. This article is general information, not investment, tax or legal advice, and figures can change after the time of writing. When investing, your capital is at risk. Yields may vary.