Government bonds let a business earn a fixed rate on cash it will not need for a year or more. You lend to a state such as Germany, France or the United States, receive interest on set dates, and get the full face value back when the bond matures. You can also sell before then, because the market trades every business day.
The hard part is price risk. When interest rates rise, the market value of a bond falls, and longer bonds fall the most, so selling early can mean a loss. Issuers carry different credit risk, coupon dates and tax rules differ by country, and bonds sit outside the €100,000 deposit guarantee.
We make it easy. We connect your company with our regulated treasury partner, which offers government bonds alongside Treasury bills and money market funds. We check your eligibility, prepare the onboarding with you and stay your one point of contact. Your cash is invested 2 to 3 business days after onboarding, with no lock-in.
Invest Company Cash in Government Bonds
Cash you will not need for a year or more can earn a fixed coupon. We set up the bond side with you.
- Government bonds from 3% p.a.: A fixed coupon paid on set dates until the bond matures.
- Shorter options too: Treasury bills from 2.5% p.a. and money market funds from 2% p.a.
- Sell when needed: No lock-in, so you can sell at the market price before maturity.
- Regulated investing: A CySEC-regulated investment firm handles the investing.
- Quick start: Digital onboarding that usually takes about a day.
- One contact: We handle the setup and the paperwork with you.
When investing, your capital is at risk. Yields may vary.
Sophic
Treasury management
Yield
2% to 3%+ p.a
Fees
0.3% a year + €10 per order
Eligibility
EU/EEA businesses with an LEI
What Are Government Bonds
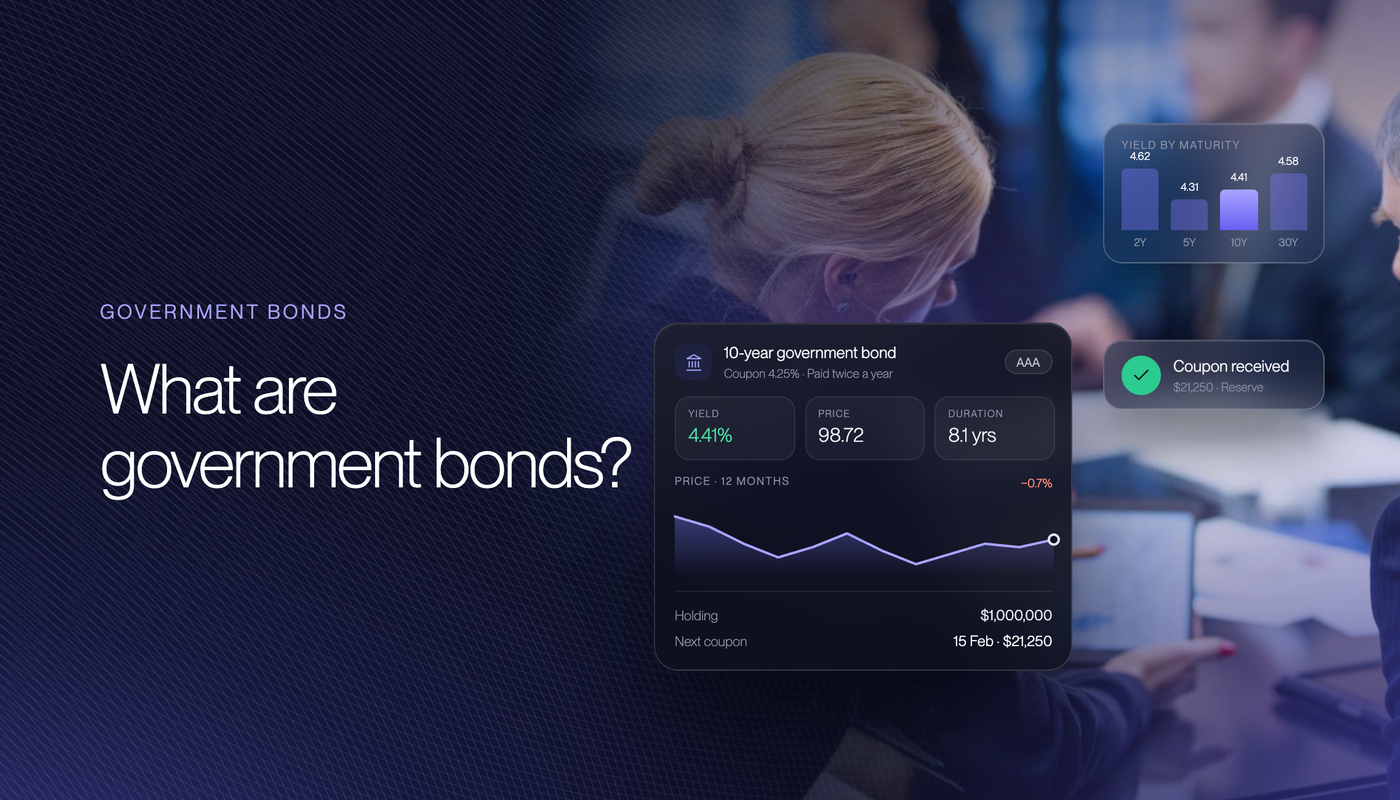
Government bonds are loans that investors make to a national government. The state sells each bond at auction, pays a fixed rate of interest, called the coupon, on set dates, and repays the face value on the maturity date. Every euro area country issues them, and so do the UK and the US.
A Bond Has a Face Value, a Coupon and a Maturity Date
The face value, also called par, is the amount repaid at the end, and prices are quoted per 100 of it. The coupon is the yearly interest on that face value. The maturity date is when the state repays. The new German bond the Bundesbank announced on 6 October 2026 has a 3.30% coupon, paid each 15 November, and matures on 15 November 2033.
German and French government bonds pay their coupon once a year. UK gilts pay every six months, according to the UK Debt Management Office (DMO), and so do US Treasury notes, according to TreasuryDirect.
Each Country Sells Bonds Through Its Own Debt Office
Germany borrows through the Finanzagentur, and the Bundesbank runs its auctions. France uses Agence France Trésor (AFT), Italy the Treasury Department of its Ministry of Economy and Finance, Spain the Tesoro Público, the UK the DMO and the US the Department of the Treasury.
The names differ too: Bunds, Bobls and Schätze in Germany, OATs in France, BTPs in Italy, Bonos and Obligaciones in Spain and gilts in the UK. The US sells Treasury notes of 2 to 10 years and Treasury bonds of 20 and 30 years. Our guide to European government bonds sets the euro issuers side by side.
Bills Under One Year Are a Separate Product
Debt that matures within a year is sold as bills, such as German Bubills, French BTFs and US Treasury bills. Bills pay no coupon, as our guide to what Treasury bills are explains. Government bonds run from about two years to 30 years or longer.
Gilt and Treasury Markets Run Into Trillions
The DMO listed 105 gilts in issue on 5 October 2026, worth £2.66 trillion at face value. US marketable Treasury debt was $31.83 trillion on 31 August 2026, according to the Treasury's Monthly Statement of the Public Debt. That depth is why government bonds can usually be sold on any business day.
Sophic
Treasury management
Yield
2% to 3%+ p.a
Fees
0.3% a year + €10 per order
Eligibility
EU/EEA businesses with an LEI
How Government Bonds Work From Auction to Maturity
This is how government bonds work in practice. A debt office sells a new bond at auction, investors trade it every day afterwards, the state pays the coupon on fixed dates, and it repays the face value at maturity. A company can buy at any point in that life, at that day's market price.
The Debt Office Sells New Bonds at Auction
On 6 October 2026, the Bundesbank announced an auction for the next morning of the new 3.30% Federal bond maturing in 2033, with a target of €4 billion. Only members of the Bund Issues Auction Group, a set of banks, may bid. Everyone else buys through them or in the market afterwards.
In a 2-year Schatz auction the same day, bids totalled €4.87 billion. The Bundesbank allotted €4.53 billion at an average yield of 3.1%, and Germany kept €1.47 billion back to sell into the market later. On 29 September 2026, the DMO sold £4.25 billion of a 4⅞% gilt maturing in 2036 at an average yield of 5.383%, with bids 3.34 times the amount on offer. When investing, your capital is at risk. Yields may vary.
Prices Are Quoted per 100 of Face Value
A price of 96.154 for that gilt means each £100 the UK repays in 2036 cost £96.154. Buy between coupon dates and you also pay the seller the interest built up since the last coupon, called accrued interest. It comes back with the next coupon, so it is not a cost.
Coupons Arrive on Fixed Dates
The coupon is set when the bond is created and never changes. On €500,000 face value of the new 3.30% Bund, a company earns €16,500 for each full year, paid every 15 November from 2027 to 2033, whatever market rates do. When investing, your capital is at risk. Yields may vary.
The State Repays the Face Value at Maturity
At maturity, the debt office repays the face value with the last coupon. If you paid 96 for a bond that repays 100, the 4-point gain adds to your return. If you paid 104, you lose 4 points by maturity, offset by a higher coupon. That is why you compare yields, not coupons.
Read more: Treasury bills vs bonds and how a company buys government bonds.
Hold Government Bonds Without a Treasury Team
You do not need a dealing desk or treasury staff. Tell us how much cash you hold and when you need it.
- Segregated client cash: Held in segregated accounts at J.P. Morgan.
- Assets safeguarded: Your investments are safeguarded by SIX Group.
- Bond details upfront: See the issuer, coupon, maturity and yield before you buy.
- Dates that fit: Choose bonds that mature before you need the cash.
- Paperwork handled: We prepare the onboarding documents with you.
- Your decisions: You choose what to buy, how much and when to sell.
When investing, your capital is at risk. Yields may vary.
Why Government Bond Prices Fall When Yields Rise
A government bond's coupon is fixed, so when newer bonds pay more, older ones fall in price until their yield matches. When rates fall, the reverse happens. The longer a bond has left to run, the more its price moves. That price risk becomes a real loss only if you sell before maturity.
Bond Prices and Bond Yields Move in Opposite Directions
The yield is your return if you buy at today's price and hold to maturity. Because the payments are fixed, a lower price means a higher yield. The market moves bond yields every day, and bond prices follow.
A 1-Point Rise Cuts a 10-Year Bond by About 7%
Say your company buys €100,000 face value of a new 10-year government bond with a 3.5% coupon, at a price of 100. A year later, similar bonds yield 4.5%, so the price of yours drops to about 92.73. On paper it is worth €92,731, a loss of €7,269. Had yields fallen to 2.5%, it would be worth about €107,971.
Hold it to the end and the swing disappears. You still receive €3,500 a year and €100,000 at maturity, as long as the issuer pays. When investing, your capital is at risk. Yields may vary.
Longer Bonds Move More When Yields Change
Duration, measured in years, shows roughly how many points a bond's price moves for each 1-point change in its yield. The table assumes bonds bought at 100 with coupons close to the ECB's euro area AAA curve on 5 October 2026, then an immediate 1-point rise.
Maturity | Coupon | Duration | Price after a 1-point rise | Change on €100,000 |
|---|---|---|---|---|
2 years | 3.00% | 1.9 years | 98.11 | €1,886 loss |
5 years | 3.17% | 4.6 years | 95.57 | €4,431 loss |
10 years | 3.50% | 8.3 years | 92.09 | €7,913 loss |
30 years | 3.77% | 17.8 years | 84.22 | €15,784 loss |
A 30-year bond moves about eight times as much as a 2-year bond. Keeping company cash in short to medium maturities, matched to when it is needed, is a core part of treasury risk management. When investing, your capital is at risk. Yields may vary.
A 2048 OAT Bought at 100 in 2017 Now Sells Near 57
AFT launched its 2% OAT maturing on 25 May 2048 on 16 May 2017 at a price of 100.069, a yield of 1.997%. At AFT's auction on 1 October 2026, the same bond sold at 57.23, a yield of 5.40%. €1 million of face value bought at launch is now valued at about €572,000, yet France still owes the full €1 million in 2048. When investing, your capital is at risk. Yields may vary.
Sophic
Treasury management
Yield
2% to 3%+ p.a
Fees
0.3% a year + €10 per order
Eligibility
EU/EEA businesses with an LEI
Government Bond Yields in October 2026
At the time of writing, 10-year government bond yields run from about 3.5% in Germany to above 5% in the UK and the US. Shorter bonds pay less than longer ones in each market, and the ECB deposit rate, 2.50% since 16 September 2026, anchors short euro yields. When investing, your capital is at risk. Yields may vary.
Bond | Yield | Date | Source |
|---|---|---|---|
German Bund, 10 years | 3.51% | 5 Oct 2026 | Bundesbank yield curve |
German Schatz, 2 years | 3.1% at auction | 6 Oct 2026 | Bundesbank auction result |
French OAT, 3.70% 2036 | 4.93% at auction | 1 Oct 2026 | Agence France Trésor |
Spanish bonds, 10 years | 3.63% monthly average | August 2026 | ECB |
Italian bonds, 10 years | 3.99% monthly average | August 2026 | ECB |
UK 4⅞% Treasury Gilt 2036 | 5.383% at auction | 29 Sep 2026 | UK DMO |
US Treasury, 2 years | 4.84% | 5 Oct 2026 | US Treasury par yield curve |
US Treasury, 10 years | 5.31% | 5 Oct 2026 | US Treasury par yield curve |
The table mixes daily readings, auction results and monthly averages, so read each figure with its date. Government bond yields change daily and are shown before costs and tax. When investing, your capital is at risk. Yields may vary.
The Yield Curve Slopes Upward in Euros and Dollars
On 5 October 2026, the ECB's yield curve for AAA-rated euro area government bonds stood at 2.85% for 1 year, 3.00% for 2 years, 3.17% for 5 years, 3.50% for 10 years and 3.77% for 30 years. Investors want more for lending longer, so this upward slope is the normal shape.
US Treasury yields that day ran from 4.22% for 3 months to 4.84% for 2 years, 5.31% for 10 years and 5.66% for 30 years. When short yields rise above long ones, the curve is inverted, which markets read as a sign that rates are expected to fall. When investing, your capital is at risk. Yields may vary.
Going Longer Adds Little Yield for Much More Price Risk
On the euro curve, moving from 1 year to 5 years added about 0.3 points of yield, while duration rose from about 1 to about 4.6. For cash needed within two years, that extra yield is small next to the extra price risk. Short euro yields track the ECB most closely, as do the returns of money market funds.
Read more: why most business current accounts pay so little.
Sophic
Treasury management
Yield
2% to 3%+ p.a
Fees
0.3% a year + €10 per order
Eligibility
EU/EEA businesses with an LEI
Credit Risk and Spreads Between Sovereign Bonds
Sovereign bonds are not all priced the same. Investors ask more from governments with higher debt or weaker public finances, and the extra yield over Germany is called the spread. Ratings agencies such as Fitch, S&P Global and Moody's grade governments, and both ratings and spreads change over time.
Country | 10-year yield, August 2026 average | Spread over Germany |
|---|---|---|
Germany | 3.19% | Benchmark |
Netherlands | 3.29% | 0.10 points |
Spain | 3.63% | 0.44 points |
Greece | 3.87% | 0.68 points |
Italy | 3.99% | 0.80 points |
France | 4.00% | 0.81 points |
France paid about as much as Italy in August 2026, and more than Spain or Greece, according to the ECB. On €100,000 of 10-year bonds, a 0.81-point spread is €810 a year of extra income for taking more credit risk. When investing, your capital is at risk. Yields may vary.
Fitch Rates Germany AAA and Italy BBB+
Fitch affirmed Germany at AAA with a stable outlook on 15 May 2026. AFT's own ratings page lists France at A+ with Fitch (reviewed on 28 August 2026) and S&P (29 May 2026), and at Aa3 with a negative outlook at Moody's (10 April 2026). Fitch kept Italy at BBB+ in September 2026 and affirmed the US at AA+ in August 2026.
A Wider Spread Means a Lower Price
Spreads move with politics and public finances. If the spread on a 10-year bond widens by 0.5 points, its price drops by about 4 points per 100, even if German bond yields stay put. Your treasury policy should limit how much of the reserve sits with any one government.
Inflation-Linked Government Bonds
Inflation-linked government bonds raise their repayment amount, and with it the coupon, in line with a consumer price index. They start with a lower yield than ordinary bonds and pay off when inflation runs above what the market expected. France, the UK and the US issue them, while Germany stopped in 2024.
France Links OAT€is to Euro Area Prices
AFT first issued an OAT€i in October 2001. It tracks the euro area HICP excluding tobacco, published by Eurostat, and both the annual coupon and the repayment rise with it. If prices are lower at maturity than at the start, AFT still repays at least the face value.
UK Index-Linked Gilts Follow the RPI
The UK sold its first index-linked gilt on 27 March 1981. Coupons and repayment track the Retail Prices Index (RPI). On 5 October 2026, the DMO listed 34 index-linked gilts worth £710 billion including the inflation uplift, about a quarter of all gilts.
US TIPS Repay the Higher of Two Amounts
TreasuryDirect sells Treasury Inflation-Protected Securities (TIPS) for 5, 10 or 30 years. The principal moves with the consumer price index, and interest is paid every six months on that adjusted amount. At maturity you get the adjusted or the original principal, whichever is higher.
Germany Stopped New Issues in 2024
The Finanzagentur announced on 22 November 2023 that Germany would issue no new inflation-linked securities from 2024 and would not reopen old ones. The four already outstanding, worth €66.25 billion at the time, still trade.
Match Government Bond Maturities to Your Cash Plan
Split company cash by when you need it. We set up all three with you.
- Reserves for later years: Government bonds from 3% p.a. with coupons on fixed dates.
- Cash due within a year: Treasury bills from 2.5% p.a., held to a set maturity.
- A ready buffer: Money market funds from 2% p.a. for cash you may need at short notice.
- A ladder of maturities: Spread bonds across several years so one repays each year.
- Fees shown first: A small yearly fee and a flat charge per order, before you invest.
When investing, your capital is at risk. Yields may vary.
Holding Government Bonds to Maturity or Selling Early
Hold a government bond to maturity and, as long as the issuer pays, you receive every coupon and the full face value, whatever prices did in between. Sell early and you get that day's market price, which can be above or below what you paid. Matching maturities to payment dates removes most of that risk.
Holding to Maturity Locks In Your Yield
The yield at purchase is your return if you hold to the end, before costs and tax. Price moves in between are gains and losses on paper. That makes government bonds a fit for cash with a known date, such as a loan repayment in three years or a building project due to start in two.
Selling Early Turns a Paper Loss Into a Real One
Silicon Valley Bank shows the risk. On 8 March 2023, after months of deposit outflows, its parent company said it had sold about $21 billion of securities at an after-tax loss of about $1.8 billion. A bank run followed the next day, and the bank was closed on 10 March 2023. The Federal Reserve's review found that at the end of 2022 its held-to-maturity book, mostly long-dated mortgage securities backed by US government agencies, had an average duration of 6.2 years. Credit was not the problem. The cash was needed before the securities matured.
A Ladder Spreads Maturities Across the Years
A ladder splits the cash across bonds that mature at intervals, for example a quarter each in one, two, three and four years. Each year one rung repays, and you spend that cash or reinvest it at the yields of the day. Part of the reserve is always close to cash, and you avoid putting everything in at one rate.
Keep the Next Few Months of Cash Out of Bonds
Payroll, suppliers and tax due in the next few months belong in the current account or an EMI account. Size that buffer with a cash reserve rule and a rolling forecast, the base of cash flow management, and put the layer above it into bonds. Good liquidity management writes down which cash goes where.
Read more: where to put business cash for the short term.
Sophic
Treasury management
Yield
2% to 3%+ p.a
Fees
0.3% a year + €10 per order
Eligibility
EU/EEA businesses with an LEI
Businesses That Hold Government Bonds
Businesses hold government bonds when cash builds up well before it is spent and the spending date is known. A bond that matures just before that date earns a fixed yield in the meantime. Insurers and pension funds are the classic holders, but many smaller firms have dated cash too.
Business | Why cash builds up | When it is needed |
|---|---|---|
Premiums paid upfront and reserves for claims | Claims paid over months and years, some long after the policy ends | |
Fees paid a term or a year ahead, plus a building fund | Salaries every month, the building fund when work starts | |
Endowments, legacies and the board's reserve | Grants promised over several years | |
Partner capital and money set aside for tax (firm cash only, never client money) | Partner retirements and the firm's tax dates | |
A funding round paid in at once | Runway spent month by month over the next two or three years | |
Property companies | Rent collected ahead of a loan repayment | The date a bank loan or bond falls due |
Shipping companies ordering vessels | Cash set aside for the shipyard | Instalments due at fixed building milestones |
Holding companies after a sale | Proceeds from selling a business or property | Deferred payments, earn-outs or the next deal |
Energy project companies | Reserve accounts that lenders require | Loan payment dates, and dismantling costs at the end of the project |
Family-owned groups | Retained profits the business does not need | Succession, buyouts or large purchases years ahead |
In every row the cash has a date, or a range of dates, a year or more away. That is the cash government bonds suit. Money that may be needed any week fits a fund or a deposit better, and money due within a year fits a Treasury bill.
Large Groups Set Bond Limits in a Treasury Policy
Large groups run this through a treasury team that matches investments to cash forecasts and sets limits per issuer, currency and maturity, as our guide to corporate treasury management explains. A smaller business can follow the same rules with a simple forecast and a one-page policy. Our guide to what treasury management is covers the basics.
Sophic
Treasury management
Yield
2% to 3%+ p.a
Fees
0.3% a year + €10 per order
Eligibility
EU/EEA businesses with an LEI
Government Bonds Compared With Deposits, Funds and Bills
Government bonds fix a coupon for longer than a deposit, a fund or a bill, and at the time of writing they also yield more than all three, but their price moves most when rates change. Deposits keep the €100,000 guarantee, funds give the quickest access, and bills mature within a year.
Factor | Bank deposit | Money market fund | Treasury bills | Government bonds |
|---|---|---|---|---|
Typical return | 0.61% overnight, 2.24% fixed up to 1 year (ECB, euro area companies, August 2026) | From 2% p.a. with our partner, variable | From 2.5% p.a. with our partner, fixed to maturity | From 3% p.a. with our partner, fixed coupon |
Access to cash | Same day on demand, notice or term on others | Any dealing day | At maturity within a year, or sold earlier | At maturity, or sold earlier at market price |
Lock-in | None on demand, term deposits lock in | None with our partner | None with our partner | None with our partner |
Deposit guarantee cover | Up to €100,000 per depositor per bank | None, not a deposit | None, not a deposit | None, not a deposit |
Main risk | Bank failure above €100,000, low return | Holdings can lose value | Issuer credit, price if sold early | Price falls when rates rise, issuer credit |
Deposits suit money needed now, funds the buffer, bills dated cash inside a year, and bonds dated cash further out. Weigh bonds against business savings accounts and fixed deposit accounts on access and cover as well as yield. When investing, your capital is at risk. Yields may vary.
Bonds Sit Outside the €100,000 Deposit Guarantee
The EU Deposit Guarantee Schemes Directive 2014/49/EU covers deposits up to €100,000 per depositor, per bank (Articles 6 and 7). Bonds are not deposits, so it never covers them. Your protection is the issuer's ability to pay and, with our regulated treasury partner, client assets held with an independent custodian. See our guide to deposit guarantee schemes for business accounts.
You Need an LEI Before You Can Buy Bonds
An LEI is a 20-character code under ISO 17442, renewed every year, according to GLEIF. Article 13(2) of Delegated Regulation (EU) 2017/590 bars an investment firm from carrying out a reportable trade, such as buying a government bond, for an eligible company that has no LEI. This "no LEI, no trade" rule has applied since 3 January 2018. See what an LEI is and who needs one.
Read more: money market funds for companies.
Sophic
Treasury management
Yield
2% to 3%+ p.a
Fees
0.3% a year + €10 per order
Eligibility
EU/EEA businesses with an LEI
What It Costs to Invest in Government Bonds
Government bonds have no ongoing fund charge, but buying and holding them still costs money: the bid-offer spread, a service or custody fee, order fees and sometimes currency conversion. Accrued interest is not a cost. Check the total before you invest, because costs take a bigger share when yields are low.
Spreads, Fees and Currency Margins Add Up
Cost | How it is charged | What to check |
|---|---|---|
Bid-offer spread | Built into the buying and selling price | The gap between the two prices |
Service or custody fee | A yearly percentage of your balance | What it covers, such as reporting |
Order fee | A flat amount per buy or sell | How often you plan to trade |
Accrued interest | Paid to the seller between coupon dates | Not a cost, it returns with the next coupon |
Currency conversion | A margin on the exchange rate | Only if the bond is in another currency |
LEI | Paid to an LEI issuer every year | The renewal date, so it never lapses |
If you hold to maturity, the yearly fee and the spread when you buy matter most.
Costs Take About a Tenth of a 3% Yield
Assume a company puts €500,000 into government bonds at 3%, the starting yield our partner quotes, for a year. That earns about €15,000. After assumed total costs of 0.3% a year and two order fees, about €13,480 is left. At the ECB's August 2026 average of 2.24% on company deposits fixed for up to a year, the same money earns about €11,200. When investing, your capital is at risk. Yields may vary.
Tax is not included and depends on where your company is based, so check with your tax adviser. A business investment account holds the bonds, and our treasury service for businesses covers the setup.
Check Your Eligibility to Invest in Government Bonds
Most EU and EEA companies can start quickly. We confirm the details with you before onboarding begins.
- EU or EEA business: Our partner works with companies based in the EU and EEA.
- LEI checked first: We tell you upfront if you still need one.
- One document list: Everything to send, listed once, with no repeat requests.
- Sector screened early: Excluded industries are flagged on the first call.
- Invested in days: Cash goes in 2 to 3 business days after onboarding.
When investing, your capital is at risk. Yields may vary.
Common Government Bond Mistakes
Most mistakes with government bonds come from treating them like cash, chasing the highest yield or ignoring currency. Each one below has a real cost in money or access to cash, and each is easy to avoid with a cash forecast and a short written policy.
Buying a Bond That Matures After You Need the Cash
A company needs €400,000 in 18 months but buys a 10-year bond because it pays more. If yields rise by 1 point before the sale date, the worked example above shows a loss of about 7%, close to €29,000, taken on the day the cash is needed. The extra yield over a 2-year bond, about 0.5 points on the euro curve, would earn roughly €3,000 in that time. Pick bonds that mature shortly before each planned payment, and keep cash with no fixed date in a fund or a deposit. When investing, your capital is at risk. Yields may vary.
Chasing the Highest Yield Without Asking Why
In August 2026, French 10-year bonds paid 0.81 points more than German ones, according to the ECB. On €500,000, that is about €4,050 a year. It is payment for credit risk, not free money. If the spread then widens by 0.5 points, a 10-year bond loses about 4%, or €20,000, close to five years of the extra income. Set a limit per issuer and a minimum rating in your treasury policy, and compare yields only between bonds of similar maturity and credit. When investing, your capital is at risk. Yields may vary.
Taking Currency Risk for a Few Extra Points
On 5 October 2026, the US 10-year yield was 5.31% against 3.51% for the German Bund, a gap of 1.8 points. On €1 million, that is €18,000 a year. For a euro-based company, a 5% fall in the dollar against the euro costs €50,000, almost three years of the extra yield. Hold bonds in the currency of the costs they will pay, or hedge as part of your wider cash management and know what the hedge costs. When investing, your capital is at risk. Yields may vary.
Sophic
Treasury management
Yield
2% to 3%+ p.a
Fees
0.3% a year + €10 per order
Eligibility
EU/EEA businesses with an LEI
Bottom Line
Government bonds lend your company's cash to a state for a fixed coupon and return the face value at maturity. They suit cash with a known date a year or more away. Prices fall when yields rise, so match maturities to your payment dates and hold to the end where you can. They carry no deposit guarantee.
What are government bonds in simple terms?
How do government bonds work?
What are government bond yields in 2026?
Why do bond prices fall when interest rates rise?
Can you lose money on government bonds?
What happens if I sell a government bond before maturity?
How is a government bond different from a Treasury bill?
Are government bonds covered by the deposit guarantee?
What do credit ratings mean for sovereign bonds?
What are inflation-linked government bonds?
Do companies need an LEI to buy government bonds?
Why would a business buy government bonds?
How much does it cost to invest in government bonds?
Sources
- Deutsche Bundesbank, Bundesanleihen tender announcement, 3.30% Bundesanleihe 2026 (2033), 6 October 2026
- Deutsche Bundesbank, Bundesschatzanweisungen allotment, 3% Schatz 2026 (2028), 6 October 2026
- Deutsche Bundesbank, Term structure of interest rates on listed Federal securities, 10 years, daily (5 October 2026)
- Finanzagentur, Federal government discontinues programme for inflation-linked bonds, 22 November 2023
- Agence France Trésor, Latest auction results, OAT auction of 1 October 2026
- Agence France Trésor, Launch of the new OAT 2.00% 25 May 2048, 16 May 2017
- Agence France Trésor, France's credit ratings (checked 6 October 2026)
- Agence France Trésor, OAT€is characteristics
- UK Debt Management Office, Result of the auction of 4⅞% Treasury Gilt 2036, 29 September 2026
- UK Debt Management Office, Gilts in issue, 5 October 2026
- UK Debt Management Office, Index-linked gilts
- US Department of the Treasury, Daily Treasury Par Yield Curve Rates, 5 October 2026
- US Department of the Treasury, Monthly Statement of the Public Debt, 31 August 2026
- TreasuryDirect, Treasury Notes
- TreasuryDirect, Treasury Inflation-Protected Securities (TIPS)
- European Central Bank, Euro area yield curves, AAA-rated government bonds (5 October 2026)
- European Central Bank, Long-term interest rate statistics for convergence purposes, August 2026
- European Central Bank, Key ECB interest rates (checked 6 October 2026)
- European Central Bank, Euro area bank interest rate statistics, August 2026 (released 1 October 2026)
- Fitch Ratings, Fitch Affirms Germany at 'AAA'; Outlook Stable, 15 May 2026
- AGI, Fitch confirms Italy's rating at BBB+ with a stable outlook, 11 September 2026
- Asharq Al-Awsat (Reuters), Fitch Keeps US at 'AA+', 14 August 2026
- Board of Governors of the Federal Reserve System, Review of the Federal Reserve's Supervision and Regulation of Silicon Valley Bank, 28 April 2023
- SVB Financial Group, Form 8-K, Exhibit 99.1, 8 March 2023
- Directive 2014/49/EU on deposit guarantee schemes, EUR-Lex
- Commission Delegated Regulation (EU) 2017/590 (RTS 22), EUR-Lex
- GLEIF, Introducing the Legal Entity Identifier
- GLEIF, The LEI in numbers Q2 2026, 23 July 2026
Binderr is not an investment provider or adviser. We connect businesses with regulated investment providers and help with the setup. Every investment is made under the provider's own terms, fees and risk disclosures, which you review and accept directly with them, and the decision to invest is yours. Binderr is not responsible for investment performance or for any loss. This article is general information, not investment, tax or legal advice, and figures can change after the time of writing. When investing, your capital is at risk. Yields may vary.