Good cash flow management tells you, weeks ahead, whether the business can pay its staff, suppliers and tax bills on time. It shows when to chase a customer, when to arrange a credit line and when there is spare cash to put to work, and it keeps a profitable business off an expensive overdraft.
The hard part is timing. Profit and cash arrive at different times, and customers rarely pay on the due date: Intrum's European Payment Report 2026 found that over 12% of revenue now arrives late. Cash the business does hold often sits in a current account, where euro area companies were paid 0.61% on average in August 2026.
We make the spare cash side easy. When your cash flow forecast shows money you will not need for a while, we connect your company with our regulated treasury partner to invest it in money market funds, Treasury bills or government bonds. We check eligibility, prepare the onboarding with you and stay your one contact.
Earn on Cash Your Cash Flow Plan Does Not Need
When your cash flow forecast shows cash above what the business needs, that cash can earn a market rate. We set up the investing side with you.
- Money market funds: From 2% p.a. in EUR, GBP or USD, for cash you may need soon.
- Treasury bills: From 2.5% p.a. for cash with a known date, such as a tax bill.
- Government bonds: From 3% p.a. for money you can leave for a year or more.
- No lock-in period: Sell when the business needs the cash back.
- Regulated investing: A CySEC-regulated investment firm handles every order.
- Fast setup: Digital onboarding in about a day, invested 2 to 3 business days later.
When investing, your capital is at risk. Yields may vary.
Sophic
Treasury management
Yield
2% to 3%+ p.a
Fees
0.3% a year + €10 per order
Eligibility
EU/EEA businesses with an LEI
What Is Cash Flow Management
Cash flow management is the work of tracking, forecasting and timing the money that moves in and out of a business, so it can always pay its bills. It covers collecting from customers, paying suppliers, planning for tax and borrowing, and deciding what to do with cash the business does not need yet.
Think of cash flow management as the day-to-day side of cash management: the bank balance today, the balance in 13 weeks and the decisions in between.
Cash Flow Is Not the Same as Profit
Profit is sales minus costs for a period. It counts a sale when the invoice goes out, not when the money arrives. Cash flow counts only money that actually moves through the bank. Stock bought in advance, invoices waiting to be paid and loan repayments all change cash without changing profit in the same month. Good cash flow management watches cash as closely as profit.
A Profitable Order Can Empty the Bank Account
Take an example company, a packaging wholesaler with €80,000 in the bank. It wins a €400,000 order from a retail chain on 60-day terms. The stock costs €280,000, payable to suppliers in 30 days, and extra wages and freight cost €40,000. The order makes a profit of €80,000. The figures are assumed for illustration.
Day | What happens | Bank balance |
|---|---|---|
Day 0 | Order won, nothing paid yet | €80,000 |
Days 1 to 30 | Extra wages and freight paid | €40,000 |
Day 30 | Suppliers paid for the stock | Minus €240,000 |
Day 60 | Invoice due, the customer has not paid | Minus €240,000 |
Day 80 | Customer pays €400,000, 20 days late | €160,000 |
The order is profitable, yet for 50 days the business needs €240,000 it does not have. The 20-day delay is typical: Intrum's 2026 report puts the gap between agreed terms and actual payment in B2B trade at 20 days, up from 16 days in 2023. With a credit line agreed in advance, the gap costs about €1,290 at the euro area average overdraft rate of 3.92%. Without one, staff or suppliers go unpaid. Managing cash flow well means seeing this gap before the order is signed, not on day 30.
Sophic
Treasury management
Yield
2% to 3%+ p.a
Fees
0.3% a year + €10 per order
Eligibility
EU/EEA businesses with an LEI
The Three Types of Cash Flow
Cash flow splits into three types: operating, investing and financing. IAS 7, the international standard for the statement of cash flows, uses these three headings. Reading them apart shows whether trading itself produces cash, or whether the bank balance is held up by loans, new equity or asset sales.
Operating Cash Flow Comes From Trading
Operating cash flow is money from the main business: customer receipts minus payments to suppliers, staff, landlords and the tax authority. IAS 7 describes operating activities as the principal revenue-producing activities of the business. A healthy business produces positive operating cash flow over time, even if some months are negative.
Investing Cash Flow Covers Long-Term Assets
Buying or selling equipment, vehicles, property, software or another company is investing cash flow. A van bought for €45,000 is a cash outflow on the day it is paid, while profit takes the cost a little each year through depreciation.
Financing Cash Flow Covers Loans and Owners
New loans, loan repayments, new share capital and dividends are financing cash flow. A loan can lift the bank balance while operating cash flow is negative, which is why lenders and buyers read the three types separately.
Read more: working capital and how to calculate it.
How to Build a 13-Week Cash Flow Forecast
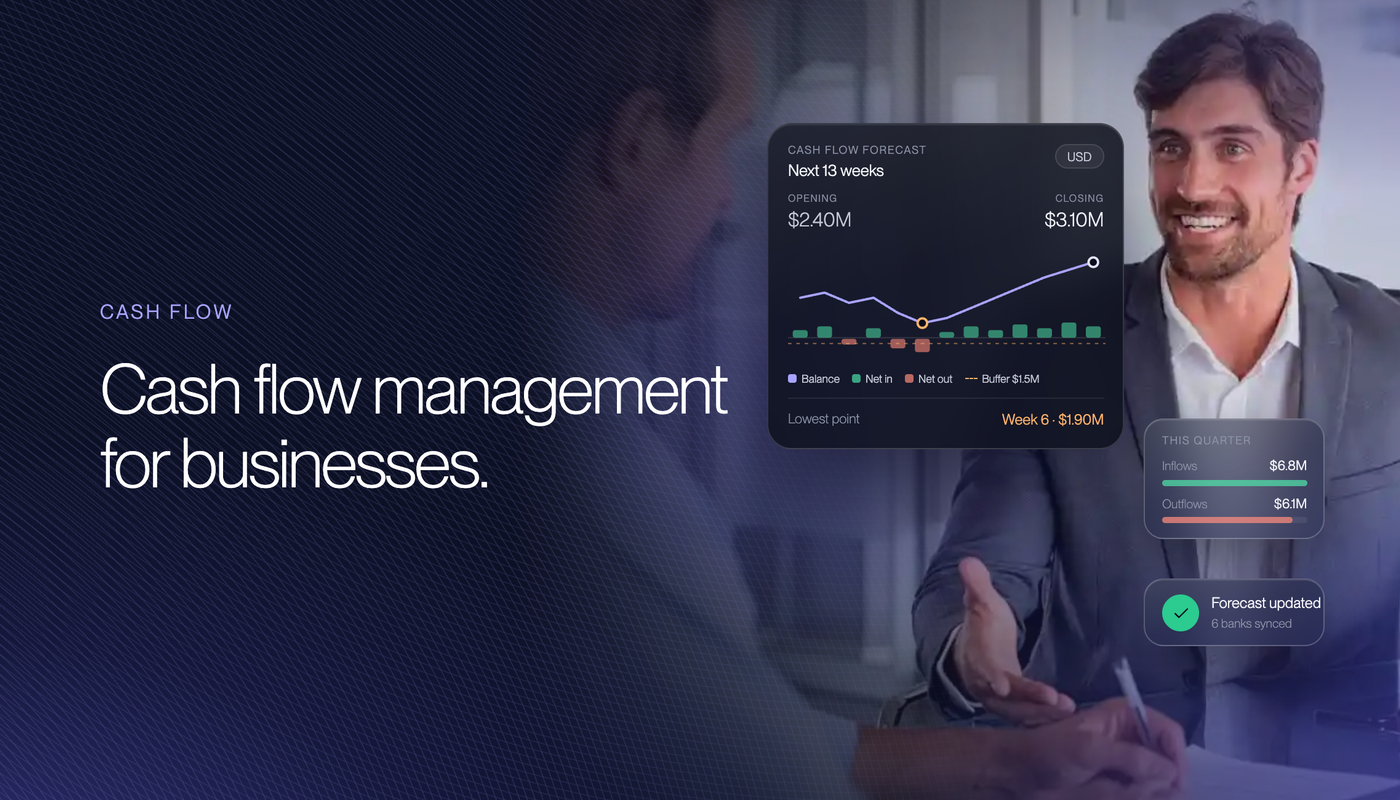
A 13-week cash flow forecast lists, week by week, the cash you expect to receive and pay over the next quarter, starting from today's bank balance. Thirteen weeks is long enough to see payroll, rent, VAT and loan dates coming, and short enough to forecast each line from real invoices and known bills.
Start From Today's Bank Balance
Use the actual balance across all business accounts on the day you start. Leave out money that is not yours to spend, such as customer deposits you may have to refund.
Enter Receipts in the Week They Will Really Arrive
Enter each open invoice and expected sale in the week the money is likely to land, based on each customer's real payment habit. If a customer usually pays 20 days late, move the receipt three weeks later.
List Every Payment, Including Tax and Annual Bills
Add payroll and payroll taxes, rent, suppliers, loan repayments, VAT, corporate tax instalments, insurance and annual licence fees. VAT you charge customers belongs to the tax authority, so plan for it from the day you invoice.
A Sample 13-Week Cash Flow Forecast
Take an example IT services firm with 18 staff, €95,000 in the bank, monthly payroll of €92,000 and an annual €118,000 contract renewal due in week 10. The figures are assumed for illustration.
Week | Cash in | Cash out | Closing cash | Main payments |
|---|---|---|---|---|
Week 1 | €34,000 | €15,000 | €114,000 | Rent, contractors |
Week 2 | €41,000 | €12,000 | €143,000 | Loan, contractors |
Week 3 | €30,000 | €8,000 | €165,000 | Contractors |
Week 4 | €38,000 | €100,000 | €103,000 | Payroll, contractors |
Week 5 | €29,000 | €15,000 | €117,000 | Rent, contractors |
Week 6 | €36,000 | €12,000 | €141,000 | Loan, contractors |
Week 7 | €33,000 | €44,000 | €130,000 | VAT, contractors |
Week 8 | €31,000 | €100,000 | €61,000 | Payroll, contractors |
Week 9 | €40,000 | €15,000 | €86,000 | Rent, contractors |
Week 10 | €118,000 | €12,000 | €192,000 | Annual renewal in, loan out |
Week 11 | €37,000 | €23,000 | €206,000 | Tax instalment, contractors |
Week 12 | €35,000 | €8,000 | €233,000 | Contractors |
Week 13 | €42,000 | €100,000 | €175,000 | Payroll, contractors |
The lowest point is week 8, at €61,000, right after VAT in week 7 and payroll in week 8. The firm keeps a €60,000 buffer, so week 8 is tight but covered, and it chases the annual renewal early. After the week 13 payroll, €175,000 remains, far above the buffer, and the firm can plan to use or invest it.
Roll the Forecast Forward Every Week
Each Monday, replace last week's figures with the actuals, add a new week 13 and note why any line was off by more than about 10%. Cash flow forecasting improves with practice, and after a few weeks the cash flow forecast is accurate enough to borrow, pay or invest on. Keep a monthly 12-month cash flow plan alongside it for bigger decisions.
Put the Surplus in Your Cash Flow Forecast to Work
Your forecast shows the low point and the buffer. Tell us how much sits above that line and when you will need it back.
- You set the amount: You decide what stays in the bank and what is invested.
- Client cash kept apart: Held in segregated accounts at J.P. Morgan.
- Independent safeguarding: Your investments are safeguarded by SIX Group.
- Built around your dates: Investments chosen around payroll, VAT and the dates in your forecast.
- Onboarding prepared: We prepare the onboarding documents with you.
- Single contact: One team from the first call to your first investment.
When investing, your capital is at risk. Yields may vary.
How to Improve Cash Flow
To improve cash flow, bring money in sooner, pay out no earlier than it is due and stop small leaks such as unused subscriptions. When managing cash flow, faster collection usually matters most, because late payment is common across Europe, and every day a customer waits is a day you fund their business.
A Quarter of B2B Invoices Are Paid Late
The Atradius Payment Practices Barometer for Western Europe, published on 20 May 2026, found that nearly four in five companies report customers paying late, and about a quarter of B2B invoices are paid after the due date. Credit losses average 1.6% of B2B invoiced turnover. In Intrum's 2026 survey of 8,385 businesses in 20 countries, 57% said late payments had made them miss growth targets, and 62% said late customers made them pay their own suppliers late.
EU Law Limits Payment Terms to 60 Days
Under the Late Payment Directive 2011/7/EU, terms between businesses should not exceed 60 calendar days unless both sides expressly agree and the term is not grossly unfair to the supplier. With no agreed term, interest runs from 30 days after the invoice is received. Public authorities must generally pay within 30 days. A late payer owes statutory interest of at least the reference rate plus 8 percentage points, and at least €40 for recovery costs. A 2023 proposal to cap terms at 30 days was still awaiting the Council's position in October 2026.
Invoice Faster and Make Paying Easy
Invoice on the day the work is delivered, ask for deposits or stage payments on large jobs and use direct debit for regular customers. Send a reminder before the due date, not after. Since 9 October 2025, banks in the euro area must let customers send euro instant transfers, which arrive within 10 seconds and cost no more than a standard transfer, under Regulation (EU) 2024/886.
Pay on the Due Date, Not Before
Paying early only makes sense when the supplier pays you for it. A 2% discount for paying 20 days early is worth about 37% a year, so take it when you can. Without a discount, pay on the due date. Shortening the gap between paying suppliers and collecting from customers is the core of working capital management.
Sophic
Treasury management
Yield
2% to 3%+ p.a
Fees
0.3% a year + €10 per order
Eligibility
EU/EEA businesses with an LEI
How to Manage Cash Flow in a Seasonal Business
To manage cash flow in a seasonal business, plan the full year, not the next month. Cash from the peak has to cover the quiet months and the cost of getting ready for the next peak. The table shows how different the timing can be, even for businesses of a similar size.
When Seasonal Businesses Get Paid and When They Pay
Business | When cash comes in | When it goes out | What to plan for |
|---|---|---|---|
Ski school or Alpine hotel | December to April, deposits from autumn | Staff, repairs and marketing from September | Six or seven quiet months paid from winter cash |
Beach hotel or tour operator | Deposits early in the year, balances before summer | Refurbishment in spring, suppliers after the season | Deposits are owed until the stay happens |
Toy shop or online store | November and December | Stock bought from August to October | Funding agreed before the stock orders |
Garden centre or plant nursery | March to June | Plants, compost and staff from winter | Winter costs paid from last spring's cash |
Wine estate | Sales one to three years after harvest | Harvest labour, barrels and bottling | A long gap between cost and sale |
Roofing or building contractor | Stage payments, retention held back to the end | Materials upfront, wages weekly | Slow winter months and retention paid late |
Fees each term or a year ahead | Salaries every month, including summer | Fee income spread across 12 months | |
Festival or event organiser | Ticket sales months before the event | Artist deposits, venue and staff close to the date | Refunds if the event is cancelled |
SaaS company on annual plans | Large renewals early in the year | Salaries and hosting every month | A year of costs from one cash peak |
Charity running a funded project | Grants upfront or in tranches | Project costs over many months | Grant money tied to the project |
Two patterns stand out. The toy shop, the nursery and the wine estate spend months before they earn, so they need funding in place before the season. The hotel, the school and the festival are paid in advance, so the balance looks strong while much of that cash is still owed in service or refunds.
Cash From the Peak Must Cover the Quiet Months
Agree a credit line before the peak, set aside cash for the quiet months during it, and let money that is not needed until the next pre-season work for the months in between.
Sophic
Treasury management
Yield
2% to 3%+ p.a
Fees
0.3% a year + €10 per order
Eligibility
EU/EEA businesses with an LEI
Small Business Cash Flow Management in Seven Steps
Small business cash flow management does not need a finance team. It needs a weekly routine of about an hour, a simple forecast and a few rules the owner sticks to. These seven steps suit a firm with fewer than 50 staff, in the order to set them up.
Check Every Bank Balance on Monday
Look at the balance in each account and compare it with last week's forecast.
Keep a Simple 13-Week Forecast
One spreadsheet, one row per type of payment, updated every week with actual figures.
Send Invoices the Same Day
Invoice when the work is done, with the due date and your bank details easy to find.
Chase Before the Due Date
A polite reminder a few days before the due date gets many invoices paid on time.
Set Tax Money Aside as It Comes In
Move VAT and an estimate of corporate tax into a separate account every week.
Agree a Credit Line While Results Are Good
Banks lend more readily on strong recent accounts than to a business that is already short.
Decide Where Spare Cash Goes
Set a buffer, then put money above it to work instead of leaving it in the current account. Law firms and other partnerships can add one rule: agree drawings against the forecast, not the profit figure.
Warning Signs of Cash Flow Problems
Cash flow problems rarely arrive without warning. The usual early signs are a bank balance that is lower at each month end while the business makes a profit, an overdraft used every month, customers paying later, and supplier or tax payments slipping past their due dates. Each one gives you weeks to act.
The Overdraft Never Gets Back to Zero
An overdraft is meant for short dips. If the account has not been in credit for three months, the business is funding itself on the bank's terms, and the bank can usually reduce the limit.
Customers Take Longer to Pay
Track days sales outstanding every month: unpaid invoices divided by yearly sales, times 365. A rise from 45 to 60 days on €1,800,000 of yearly sales ties up about €74,000 more.
Stock Grows Faster Than Sales
Rising stock turns cash into goods that may sell slowly or only at a discount. Paying VAT late, asking suppliers for more time and delaying a salary run are later, clearer signs.
Sophic
Treasury management
Yield
2% to 3%+ p.a
Fees
0.3% a year + €10 per order
Eligibility
EU/EEA businesses with an LEI
Business Cash Flow Management Tools and Bank Accounts
Business cash flow management needs three things: accounting software connected to your bank, a forecast that updates every week, and bank accounts that keep tax, payroll and the buffer apart from day-to-day money. You do not need a treasury system to start, and a spreadsheet is enough.
Connect Accounting Software to Your Bank Feed
Accounting software with a bank feed imports transactions daily and lists unpaid invoices by age. That gives you the receipts and payments for the cash flow forecast without typing them. Choose a setup that also sends payment reminders.
Use Separate Accounts for Tax, Payroll and the Buffer
Keep an operating account for daily payments, a tax account that receives VAT and tax set-asides each week, and the buffer in an easy access savings account. Business current accounts usually pay little, as our guide to business accounts that pay interest explains.
Hold Each Currency You Pay In
If you buy or sell in more than one currency, a multi-currency EMI account lets you hold each one and avoid converting twice. Larger firms add treasury management to handle currency and interest rate risk.
Read more: cash management services for companies.
Invest the Cash Above Your Buffer
Once the buffer is set, the cash above it can earn a return until the date you need it.
- Maturities you choose: Treasury bills timed to land before a VAT date or a stock order.
- Funds in three currencies: Money market funds in EUR, GBP or USD, matched to the costs ahead.
- Less in one bank: Hold less above the €100,000 deposit guarantee limit.
- Costs shown first: The yearly fee and the order charge are clear before you invest.
- In within days: Cash is invested 2 to 3 business days after onboarding.
- Sell any time: Cash comes back when the forecast needs it.
When investing, your capital is at risk. Yields may vary.
How to Set a Cash Buffer and Use Surplus Cash
Set a cash buffer that covers the lowest point in your cash flow forecast plus the dips you cannot predict, then treat cash above it as surplus. Surplus cash in a current account earns very little, so match it to the date you will need it and choose where it sits for that time.
Size the Buffer From Your Forecast
Start from the lowest point in the 13-week forecast and the yearly plan. Add room for what the forecast cannot see, such as a large customer paying a month late. A simple starting point is one month of fixed costs. Our guide on how much a business should keep in reserve covers the rules of thumb, and keeping cash available while it earns covers access.
Surplus Cash in a Current Account Loses Value
In August 2026, euro area companies were paid an average of 0.61% on overnight deposits and 2.24% on deposits fixed for up to one year, according to the ECB, while Eurostat estimates euro area inflation at 3.8% in September 2026. Cash that waits there is the idle cash on your balance sheet. At the time of writing, on 5 October 2026, Germany sold Treasury bills maturing in July 2027 at a yield of 2.872%. When investing, your capital is at risk. Yields may vary.
Match Surplus Cash to the Date You Need It
Factor | Business savings account | Money market fund | Treasury bills | Government bonds |
|---|---|---|---|---|
Typical return | 0.61% overnight, 2.24% fixed up to 1 year (ECB, August 2026) | From 2% p.a. with our partner, variable | From 2.5% p.a. with our partner, fixed to maturity | From 3% p.a. with our partner, fixed coupon |
Access to cash | Same day on demand accounts, notice or term on others | Sell on any dealing day | At maturity, or sold early at market price | At maturity, or sold early at market price |
Lock-in | None on demand accounts, fixed on term deposits | None with our partner | None with our partner | None with our partner |
Deposit guarantee cover | Up to €100,000 per bank | None, not a deposit | None, not a deposit | None, not a deposit |
Main risk | Bank failure above €100,000 and a low rate | Value can fall, returns move with rates | The issuing government's credit, price moves if sold early | Price falls when rates rise |
Read the table against your forecast. A money market fund suits cash you may need within days. Treasury bills suit a known date three to twelve months away, such as next year's corporate tax. Government bonds suit money you will not need for a year or more. A fixed deposit pays a set rate but holds the money to the end of the term. When investing, your capital is at risk. Yields may vary.
You Need an LEI Before You Can Invest
EU rules bar an investment firm from carrying out reportable trades, such as buying Treasury bills or bonds, for a company without an LEI (Article 13(2) of Delegated Regulation (EU) 2017/590). Our regulated treasury partner asks for an active LEI at onboarding. See what an LEI number is and how to get one.
Read more: short-term options for business cash and money market funds for companies.
Sophic
Treasury management
Yield
2% to 3%+ p.a
Fees
0.3% a year + €10 per order
Eligibility
EU/EEA businesses with an LEI
How to Fund a Cash Flow Gap
Fund a short cash flow gap with a facility agreed in advance, not with late payments to suppliers or the tax authority. An overdraft or revolving credit line suits gaps of days or weeks, invoice finance suits firms with large unpaid invoices, and a term loan suits a longer need.
Overdrafts Cost 3.92% on Average in the Euro Area
The ECB's bank interest rate statistics put the average rate on revolving loans and overdrafts to euro area companies at 3.92% in August 2026, up from 3.65% a year earlier. Loans of up to €1 million averaged 4.15%, above the 3.77% composite cost of borrowing for all loans to companies. Arrangement fees come on top.
Agree the Credit Line Before You Need It
Banks lend on recent accounts and a clear cash flow forecast. Ask when results are strong, size the line from the deepest dip in your yearly plan and check how quickly the bank can cancel it. An overdraft is usually repayable on demand.
Invoice Finance Turns Unpaid Invoices Into Cash
With invoice finance, a lender advances part of an invoice's value now and is repaid when the customer pays. It fits firms that sell on credit, which Atradius puts at about 52% of B2B sales in Western Europe. Compare its full cost with the overdraft rate before you sign.
Check If Your Company Can Invest Its Cash
Most EU and EEA companies with spare cash can get started quickly. We confirm the details on the first call.
- EU or EEA company: Our partner onboards businesses based in the EU and EEA.
- LEI checked upfront: We tell you at the start if you still need an LEI.
- Clear document list: One list of what to send, with no repeat requests.
- Industry check first: Excluded sectors are flagged before any paperwork.
- Registry proof: A recent registry extract shows the company is active.
When investing, your capital is at risk. Yields may vary.
Common Cash Flow Management Mistakes
Most cash flow management mistakes come from reading profit as cash, forgetting the large payments that come only a few times a year, and leaving funding or spare cash to chance. Each of the four below costs real money, and each has a simple fix that fits into the weekly routine.
Growing Faster Than the Cash Allows
Sales growth uses cash before it brings any in. If yearly sales rise from €2,400,000 to €3,000,000 and customers take 60 days to pay, unpaid invoices grow by about €99,000, and stock usually grows too. Before a big contract or a growth push, run it through the cash flow forecast and agree the funding first. Managing cash flow during growth is mostly about timing that funding.
Leaving Tax and Annual Bills Out of the Cash Flow Forecast
VAT, corporate tax instalments, insurance premiums and annual bonuses come a few times a year, so a monthly view built on last month's payments misses them. VAT collected belongs to the tax authority from the day you invoice. Move it to a tax account every week, and add each annual payment to the 12-month plan as soon as you know the date.
Using the Overdraft as Permanent Funding
An overdraft is short-term money, usually repayable on demand and reviewed every year. At the 3.92% euro area average, a €150,000 overdraft used all year costs about €5,900 in interest before fees. If the account is never in credit, the business needs a term loan or more equity, and the forecast shows how much. Keep the overdraft for real dips and fund the permanent part properly.
Keeping Every Euro in One Current Account
The EU Deposit Guarantee Schemes Directive 2014/49/EU covers €100,000 per depositor per bank, so most of a €1,500,000 balance in one bank has no cover, and it is paid the overnight rate. Some firms even borrow on an overdraft at one bank while surplus cash sits at another. Keep operating cash and the buffer within reach and invest the rest. See how deposit guarantee schemes cover business accounts and how to manage treasury risk.
Sophic
Treasury management
Yield
2% to 3%+ p.a
Fees
0.3% a year + €10 per order
Eligibility
EU/EEA businesses with an LEI
Bottom Line
Business cash flow management comes down to knowing when money will arrive and leave, and acting before the gaps appear. Keep a 13-week cash flow forecast, collect faster, pay on the due date rather than early and agree funding before you need it. Then set a buffer and put the cash above it to work.
What is cash flow management?
Why is cash flow management in business important?
What does cash flow management for small business owners involve?
What is the difference between cash flow and profit?
How do I create a cash flow forecast?
Why use a 13-week cash flow forecast?
How can a business improve cash flow quickly?
What are the warning signs of cash flow problems?
How do you manage cash flow in a seasonal business?
What payment terms are allowed under EU law?
How much cash buffer should a business keep?
What should a business do with surplus cash?
Is an overdraft a good way to cover a cash flow gap?
Sources
- Intrum, European Payment Report 2026 (published 21 April 2026)
- Atradius, Payment Practices Barometer, B2B payment practices trends in Western Europe 2026 (published 20 May 2026)
- Directive 2011/7/EU on combating late payment in commercial transactions, EUR-Lex
- European Parliament Legislative Observatory, procedure 2023/0323(COD), combating late payment in commercial transactions (checked 7 October 2026)
- IFRS Foundation, IAS 7 Statement of Cash Flows
- Regulation (EU) 2024/886 on instant credit transfers in euro, EUR-Lex
- European Central Bank, Euro area bank interest rate statistics, August 2026 (released 1 October 2026)
- European Central Bank Data Portal, bank interest rates on revolving loans and overdrafts to corporations, euro area
- Eurostat, Flash estimate, euro area annual inflation up to 3.8%, September 2026 (released 2 October 2026)
- Deutsche Bundesbank, Bubill auction results, 5 October 2026
- Directive 2014/49/EU on deposit guarantee schemes, EUR-Lex
- Commission Delegated Regulation (EU) 2017/590 (RTS 22), EUR-Lex
- GLEIF, Introducing the Legal Entity Identifier
Binderr is not an investment provider or adviser. We connect businesses with regulated investment providers and help with the setup. Every investment is made under the provider's own terms, fees and risk disclosures, which you review and accept directly with them, and the decision to invest is yours. Binderr is not responsible for investment performance or for any loss. This article is general information, not investment, tax or legal advice, and figures can change after the time of writing. When investing, your capital is at risk. Yields may vary.