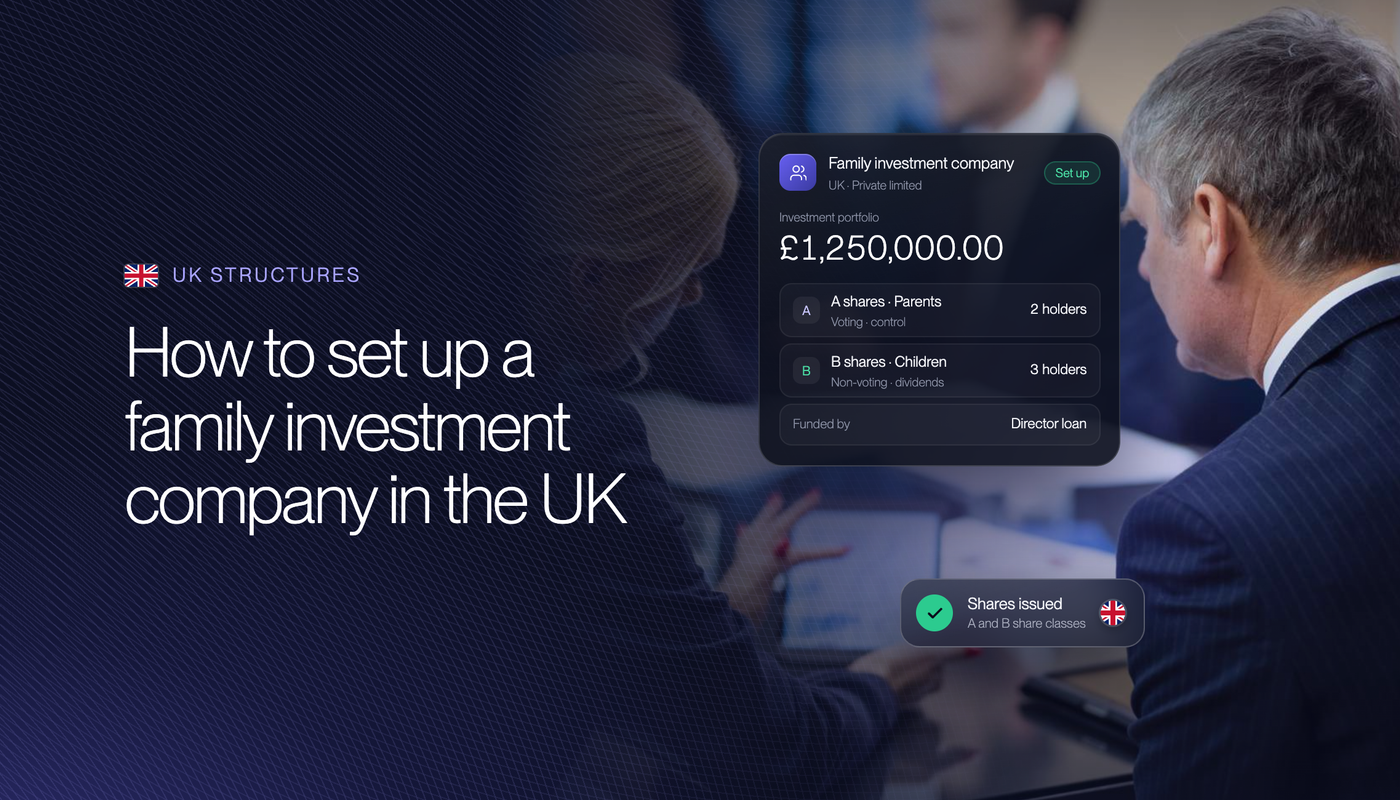
A family investment company is a UK private limited company that holds and invests a family's wealth. The founders usually keep the voting shares and run it as directors, while children or family trusts hold shares that carry the growth. Its income and gains are taxed under Corporation Tax, and most dividends it receives are exempt.
The hard part is the design. The articles, the share classes and the way money goes in decide how inheritance tax, dividend tax and stamp duty apply, and they are hard to change once family members own shares. Since 18 November 2025, every director must also verify their identity with Companies House.
This is where we come in. We form the company for you: the name check, the articles and share classes your family and its tax adviser agree, the identity checks, the filing and a bank-ready file. One team runs it from start to finish, from €350, and the company is ready in about a week.
UK Company Incorporation
Binderr
Corporate tax
19% (small profits) / 25% (main rate)
Time to Incorporate
1 Week
Cost
€350 (no pre-payment)
What Is a Family Investment Company
A family investment company, or FIC, is a private limited company set up to hold and invest family money. It is not a special legal form and needs no licence. It is an ordinary company with tailored articles and several classes of shares, so the founders keep control while other family members own the value that builds up over time.
How the Share Classes Work
The founders put money in as a loan, a share subscription or both. They hold the voting shares and sit on the board, so they decide what the company invests in and when it pays dividends. Children, grandchildren or family trusts hold non-voting or growth shares. The articles give each class its own rights to dividends and to capital. Like any UK holding company, the company is a separate legal person and owns its investments in its own name.
Why Families Use a Family Investment Company
Families choose this structure for three reasons. Control stays with the founders through the voting shares and the board. Future growth can sit in shares the next generation owns from the start. And profits are taxed inside the company under Corporation Tax, with tax on the shareholders only when money is paid out. The tax result depends on the family's own facts, so the design is settled with a tax adviser before any assets go in.
Set Up a Family Investment Company in the UK
This structure is an ordinary UK Ltd with tailored shares. Families choose it for these reasons.
- Founders keep control: Voting shares and board seats stay with the people who fund it.
- Growth for the next generation: Children or trusts hold the shares that carry future value.
- Corporation Tax on profits: 25% for most investment-only companies, 19% to 25% for letting companies.
- Dividend exemption: Most dividends from UK and foreign shares are exempt, subject to conditions.
- Formed with us from €350: About a week, with the £100 Companies House fee included.
Family Investment Company or Family Office
A family office is the team or service that manages a wealthy family's money. A FIC is often the vehicle that team works through. A smaller family can use the company itself as a simple family office. The same idea is sometimes known as a personal investment company. Larger families add staff, trusts and several companies, as our guide to setting up a family office explains.
Funding a Family Investment Company and Inheritance Tax
The company is funded by a loan from the founders, by gifts that let family members subscribe for shares, or by both. The choice decides what stays in the founders' estates for inheritance tax. UK inheritance tax is 40% above the £325,000 nil-rate band, and that band is frozen until 5 April 2031.
Funding the Company by Loan
A founder can lend some or all of the money. A loan is not a gift, and the right to be repaid stays in the lender's estate at its full value. The investment growth builds up in the company, in the value of the family's shares. A repayment returns the founders' own money rather than paying them income.
Funding the Company by Gift
Founders can also give cash to family members, who use it to subscribe for their own shares, or give them shares directly. HMRC's Inheritance Tax Manual (IHTM04057) defines a potentially exempt transfer as a gift by an individual to another individual or to a specified trust. A gift made to the company itself does not fit that definition, so the order of the gifts and share issues matters.
Inheritance Tax Rules That Apply
Gifts to people are only taxed if the donor gives away more than £325,000 and dies within 7 years, and taper relief can reduce the tax on some gifts. Budget 2025 also keeps the residence nil-rate band at £175,000 until 5 April 2031. Business Relief does not apply, because GOV.UK excludes businesses that mainly make or hold investments. Since 6 April 2025, long-term UK residents, who were UK resident for at least 10 of the previous 20 tax years, can also pay inheritance tax on their overseas assets.
Read more: inheritance tax planning.
UK Company Incorporation
Binderr
Corporate tax
19% (small profits) / 25% (main rate)
Time to Incorporate
1 Week
Cost
€350 (no pre-payment)
Family Investment Company Tax in the UK
The company pays Corporation Tax on its income and gains, and most dividends it receives are exempt. The rate is 19% on profits up to £50,000 and 25% above £250,000, but a company that only holds investments usually pays 25% on all its profits. Shareholders pay tax only on what is paid out to them.
Corporation Tax on Income and Gains
HMRC's Company Taxation Manual (CTM03951) says close investment-holding companies pay the 25% main rate and cannot use the small profits rate or marginal relief. A close company that simply holds investments, even a bank deposit account, falls into that group. A company that exists wholly or mainly to let land to unconnected people is not in that group, so it can use the 19% rate and marginal relief.
Dividends the Company Receives
Part 9A of the Corporation Tax Act 2009 exempts most dividends a company receives from UK and foreign companies. For larger companies, the dividend must fall into an exempt class, such as holdings of less than 10% of a class of shares. The tax benefits of a UK holding company rest on the same exemption.
Taking Money Out of the Company
Money comes out in three main ways. Dividends are taxed on each shareholder at 10.75%, 35.75% or 39.35% from 6 April 2026, after a £500 allowance. A salary is only possible for someone who works for the company, such as a director, and runs through PAYE. Loan repayments are not taxed as income, but interest on the loan is, and savings rates rise to 22%, 42% and 47% from 6 April 2027. Our guide on how to pay yourself from your business covers each route.
Family Investment Company Formation in the UK
This is what we handle once the structure is agreed.
- Your articles filed: The articles your family and its adviser settle go in with the application.
- Share classes created: Voting, non-voting and growth shares set out in the statement of capital.
- Identity checks guided: Each director and owner verified with Companies House, step by step.
- Tax registration started: The company is set up for Corporation Tax as it registers.
- One point of contact: One team runs the file, with no long email chains.
Can a Family Investment Company Buy Property
Yes. The company can buy residential and commercial property in the UK in its own name. The rules for companies differ from those for individuals: stamp duty is higher on residential purchases, an annual tax applies above £500,000, and mortgage interest is a company cost rather than a basic rate tax reduction.
Stamp Duty Land Tax for Companies
Stamp Duty Land Tax applies in England and Northern Ireland, at residential rates that run from 0% on the first £125,000 to 12% on the part above £1.5 million. GOV.UK's guidance for corporate bodies adds a 5% surcharge on residential property bought by companies. Since 31 October 2024, certain companies pay a flat 17% on residential property costing more than £500,000. Relief from the 17% rate may be available, subject to conditions, where the property is used in a property rental business or bought by a developer or trader, among other cases. Buyers who are not UK resident pay a further 2% surcharge.
Annual Tax on Enveloped Dwellings
The Annual Tax on Enveloped Dwellings (ATED) is a yearly charge on companies that own UK residential property worth more than £500,000. For 1 April 2026 to 31 March 2027, it starts at £4,600 for a property valued at £500,000 to £1 million and reaches £303,450 above £20 million. Property let commercially to people not connected with the owners can get relief, but it is not automatic and is claimed through the ATED online service.
Mortgage Interest in a Company
Since 6 April 2020, individual landlords get only a basic rate tax reduction for mortgage interest on homes they let, at 20% today. From 6 April 2027 that reduction moves to 22%, and property income is taxed at 22%, 42% and 47% in England, Wales and Northern Ireland. For a company, interest falls under the loan relationship rules (HMRC Property Income Manual PIM2052), so the restriction for individuals does not apply. Our guide to a limited company for property in the UK covers the purchase, and some families hold each property in its own subsidiary, as in SPV and holding company structures.
Read more: banking for real estate and property companies.
UK Company Incorporation
Binderr
Corporate tax
19% (small profits) / 25% (main rate)
Time to Incorporate
1 Week
Cost
€350 (no pre-payment)
Family Investment Company vs a Family Trust
Both hold assets for the next generation, but they work differently. A discretionary trust falls under the relevant property rules, with charges on entry, every 10 years and on exit. A family investment company has none of those charges, but its shares belong outright to the people who hold them, and each holding counts in that person's estate.
Factor | Family investment company | Discretionary family trust |
|---|---|---|
Putting assets in | Gifts to people can be potentially exempt transfers | 20% on lifetime transfers above the threshold, if the trustees pay |
Every 10 years | No charge on the company | A charge of up to 6% |
Taking assets out | Dividends, salary or loan repayments, taxed on the person | Exit charges of up to 6% |
Who controls it | Directors and holders of voting shares | The trustees |
Who owns the value | Each shareholder owns their shares | No beneficiary owns the assets outright |
Neither structure is right in every case. A trust lets trustees decide later who benefits and when, which a fixed shareholding cannot do. The two can also be combined, with a trust holding a class of shares, as in a holding company and trust structure.
Setting Up a Family Investment Company in the UK
Setting up a family investment company in the UK takes about a week with us once the family has agreed the structure. Companies House usually registers online applications within 24 hours. The design, settled with the family's tax adviser, takes longer.
Before You Start
Agree four points first: who holds which class of shares, what rights each class carries, who the directors are, and whether money goes in as a loan, a gift or both. Each director needs photo ID for Companies House identity verification. Anyone with more than 25% of the shares or votes is a person with significant control and must be named. A trust that will hold shares needs its trustees in place.
We Form the Company and File the Articles
We check the name, prepare the application and file it with the articles and share structure you have agreed. Model articles do not set out separate share classes, so the company uses its own articles to fix the voting, dividend and capital rights of each class. We add the statement of capital, the people with significant control and a UK registered office, as for any limited company in the UK.
Once the company exists, the shares go to the founders, family members or trustees as planned. HMRC posts the company's 10-digit Unique Taxpayer Reference, and we prepare the file for the bank.
Read more: UK company registration and UK company formation for non-residents.
Full-Service Setup With Bespoke Share Classes
You agree the structure. We do the rest, from the first check to the bank file.
- Name check done first: No rejected name or delay at Companies House.
- Family abroad welcome: Directors and shareholders do not have to live in the UK.
- Trustees as shareholders: Family trusts recorded as owners of their share class.
- Registered office arranged: A UK address for official post, quoted with your setup.
- Bank-ready file: The same KYC pack goes to our banking partners.
Family Investment Company Costs in 2026
A standard company costs from €350 with us. That includes set-up guidance, the name check, identity verification guidance, the KYC pack, the statement of capital, the people with significant control, the £100 Companies House fee, the filing and a bank-ready file. Bespoke articles and share classes are quoted with your setup. Trusts, foundations, funds and regulated structures are quoted separately.
Cost item | When it is paid | Typical amount | What it covers |
|---|---|---|---|
Company incorporation with Binderr, all of the above included | Once, before filing | From €350 | Formation, the £100 Companies House fee and the bank file |
Bespoke articles and share classes | Once, at formation | Quoted with your setup | The share rights the family and its adviser agree |
Registered office service | Each year, if you have no UK address | Quoted with your setup | A UK address that receives official post |
Confirmation statement | Once a year | £50 online | Confirms the company's details on the register |
Accounts and Company Tax Return | First accounts within 21 months, then yearly | About £1,000 to £2,500 a year (planning range) | Year-end accounts and the return to HMRC |
Account with our banking partners | Monthly, once open | About €30 to €100 a month on a published plan | A multi-currency account for the company |
Realistic first-year total | Over the first 12 months | About €2,000 to €5,000 for a simple company | Formation, filings, accounting and a year of banking |
Most of the cost comes in the running years: the accounts, the tax return and any ATED returns. Tax advice on the design is a separate cost.
First-Year Cost by Company Profile
Company profile | Realistic first year | What drives the cost |
|---|---|---|
Company holding cash and listed investments | About €2,000 to €4,000 | Light accounts and one tax return, no VAT or payroll |
Company run by directors abroad | About €2,200 to €5,000 | Registered office, mail forwarding and a multi-currency account |
Company owning let residential property | About €3,000 to €5,500 (planning range) | Rental bookkeeping and ATED returns on property over £500,000 |
Bespoke share classes with trust shareholders | Quoted with your setup | The articles, trustee documents and identity checks for each owner |
A company with only cash and listed shares sits at the low end. Property and trustees add work every year, not only at formation.
What Companies House Makes Public
Every FIC sits on the public register, even though the details of its investments are not listed. Anyone can see its directors, its people with significant control, the shareholders given in its confirmation statement, its articles and its yearly accounts. Small companies can leave the profit and loss account out of the accounts they file. Late accounts cost £150 to £1,500, doubled if late two years in a row.
Read more: cost of setting up a UK company.
UK Company Incorporation
Binderr
Corporate tax
19% (small profits) / 25% (main rate)
Time to Incorporate
1 Week
Cost
€350 (no pre-payment)
Business Banking for a Family Investment Company
The company needs a business account in its own name before it can receive the founders' money or invest. UK banks open accounts for investment companies, but they set strict rules on residence and purpose. Our banking partners open multi-currency accounts remotely, and we prepare their file from the same KYC pack.
At the time of writing, NatWest asks for at least one person on the application to be UK resident and the business to be registered for UK tax. Santander's Business Current Account Classic asks that everyone linked to the account lives in the UK, and costs £9.99 a month after a free first year for start-ups. Starling does not open accounts for holding companies. Banks also check where the family's money came from, so a clear source of funds file shortens the review. See our guides to banking for family offices and, where a trust holds shares, banking for trusts.
Opening the Account Through Our Banking Partners
We work with regulated payment partners that open multi-currency accounts for UK companies in days, fully remotely, with owners and directors anywhere. They are payment institutions and electronic money institutions, not banks. We build one file with the company documents, the owners' identity and the source of the funds, and make the introduction.
Factor | UK high street banks | Our banking partners |
|---|---|---|
Residence rules | At least one UK resident, and often everyone | Owners and directors can live abroad |
Monthly cost | £0 to £9.99 at the banks above, after any free period | About €30 to €100 on a published plan |
Currencies | Mostly sterling | Several currencies in one account |
How it opens | Each bank's own review, with few reasons given | A file we prepare and submit with you |
The business account holds cash and pays costs. The investments sit in a separate investment or brokerage account in the company's name. Our guides to business investment accounts and money market funds explain the options for company cash.
Equals Money
Business Bank Account
Time to onboard
2 Days
Account opening fee
Free
Monthly fee
€30
3S Money
Cross-border payments
Time to onboard
4 Days
Account opening fee
Free
Monthly fee
Starting from € 100
UK Family Investment Company vs Offshore Companies
For a UK-resident family, UK tax rules can reach a company formed abroad. A company abroad that is run from the UK is UK resident, and anti-avoidance rules can tax UK residents on income held offshore. Jersey, Guernsey and the Isle of Man are used more by families who live outside the UK or hold assets in several countries.
HMRC's International Manual (INTM120060) says a company incorporated abroad is resident where its central management and control is. The transfer of assets abroad rules (sections 714 to 751 of the Income Tax Act 2007) can tax UK-resident individuals on income that arises to a company abroad. Where a UK company owns the island company, the controlled foreign company rules in Part 9A of TIOPA 2010 target profits diverted from the UK.
Factor | UK | Jersey | Guernsey | Isle of Man |
|---|---|---|---|---|
Company tax | 19% to 25% | 0%, 10% on financial services | 0%, 10% on regulated activities | 0% on most activities |
Known for | Low-cost family companies | Trusts and holding structures | Trusts, funds and cell companies | Holding companies in the UK VAT area |
Our price | From €350 | From €1,499 | From €1,899 | From €1,499 (LLC) |
Time with us | About 1 week | About 1 week | About 1 week | About 1 week |
The island rates are lower, but for a UK-resident family the UK residence and anti-avoidance rules usually decide the tax, not the island rate. The islands are used more by families who live abroad, by companies owned by a trust run from the island, or where assets and heirs are spread across several countries.
UK vs Jersey
Jersey companies pay 0% on most income and 10% on financial services business. Jersey is a long-standing centre for family trusts, and an island holding company often sits under one, as our guide on setting up a trust in Jersey explains. A UK company costs less to form and suits a family whose directors live in the UK.
Jersey Company Incorporation
Binderr
Corporate tax
0% standard / 10% financial services
Time to incorporate
1 Week
Cost
Starting from €1,499
UK vs Guernsey
Guernsey taxes most companies at 0% and regulated activities at 10%. It is used for trusts, funds and private trust companies, and families outside the UK often hold investments through a Guernsey holding company. For a family living in the UK, the UK residence and anti-avoidance rules still apply to an island company it controls.
Guernsey Company Incorporation
Binderr
Corporate tax
0% standard / 10% regulated activities
Capital gains and inheritance tax
0%
Time to incorporate
1 Week
Cost
Starting from €1,899
UK vs Isle of Man
The Isle of Man charges 0% on most company income and shares a VAT area with the UK. Its companies and LLCs are used for holding structures, as our Isle of Man holding company guide shows. A UK company is simpler for families who live and invest in the UK.
Isle of Man Company Incorporation
Binderr
Corporate tax
0% for most activities
Time to incorporate
1 Week
Cost
Starting from €1,499
Who a Family Investment Company Is Wrong For
The structure is used mainly by UK-resident families with a large sum to invest for the long term, where the founders want to keep control. It is a poor fit for money the founders may need back soon, for small sums where the yearly costs are large next to the assets, and for families who want nothing on a public register.
It also does not fit a family that wants trustees to decide later who benefits. A trading business is often kept in its own company, which can sit under a family holding company separate from the investments. Families leaving the UK can check how UK inheritance tax applies to non-residents.
Family Investment Company Formation From €350
A standard company starts from €350 with us and is ready in about a week.
- Companies House fee inside: The £100 filing fee is part of the price, never extra.
- Bespoke articles quoted: Tailored share rights priced with your setup.
- Ready in about a week: Once the structure and the documents are agreed.
- Filing dates set out: First accounts and confirmation statement dates noted at formation.
- No rounds of questions: One complete file, checked before it goes in.
Common Mistakes With a Family Investment Company
Most problems come from the order of the steps and from share rights that do not match the plan. Each of these three is avoided by settling the design before money moves.
Gifting Money to the Company Itself
Some founders give cash straight to the company. A potentially exempt transfer must be a gift to another individual or to a specified trust, so a gift to the company does not get the 7-year treatment that a gift to a family member can get. With inheritance tax at 40% above the nil-rate band, that difference matters. Agree with the adviser whether money goes in as a loan, a share subscription or gifts to family members.
Giving Children Shares With the Wrong Rights
Articles copied from another company often give every share the same vote and the same share of the capital. The children's shares may then carry votes, or the founders' shares may keep the growth. Changing the articles later needs a special resolution of the shareholders, and the new articles go on the public register. Set out the rights of each class before the company is formed.
Putting the Family Home Into the Company
Buying the family's own home through the company brings the 5% surcharge and, on a home worth over £500,000, the 17% rate and ATED from £4,600 a year. The ATED rental relief does not apply where someone connected with the owners lives in the property. Check each property against the relief conditions before the company buys it.
Setting Up a Family Investment Company With Us
Tell us about the family, the shares and the assets. We send a written quote for the formation.
- Your structure, as agreed: Share classes and articles filed exactly as your adviser settles them.
- Trusts and property planned in: Trustee owners and property purchases built into the setup.
- Every owner verified: Identity checks done before filing, not after.
- Clear written quote: The company and any bespoke articles priced up front.
- Banking alongside: The account file prepared with the company documents.
Bottom Line
A family investment company is a UK private limited company with tailored articles and share classes. The founders keep control, and the next generation can hold the growth. Income and gains are taxed under Corporation Tax, usually at 25% for a company that only holds investments, and most dividends it receives are exempt. Property brings the 5% surcharge, the 17% rate and ATED. Inheritance tax depends on how the money goes in, with the 40% rate and the £325,000 band frozen until 5 April 2031. A trust gives trustees more discretion but carries entry, 10-year and exit charges. For a UK-resident family, an island company does not step outside the UK residence and anti-avoidance rules. The result depends on the family's circumstances, so confirm it with a tax adviser first. Our UK company formation service forms the company and files the structure you agree, from €350, in about a week.
What is a family investment company?
How does a family investment company work in the UK?
Can a family investment company buy property?
How much does it cost to set up a family investment company?
How long does setting up a family investment company take?
How is a family investment company taxed?
What is the difference between a family investment company and a trust?
How does a family investment company affect inheritance tax?
Can children own shares in a family investment company?
Is a family investment company private?
Can non-residents set up a family investment company in the UK?
Which bank account does a family investment company need?
What happens to a family investment company when a founder dies?
Sources
- GOV.UK, How Inheritance Tax works: thresholds, rules and allowances (updated 8 November 2024)
- HM Treasury, Budget 2025 Overview of tax legislation and rates (November 2025)
- HMRC, Inheritance Tax Manual IHTM04057, Potentially exempt transfers
- HMRC, Inheritance Tax Manual IHTM42081, Ten year anniversary charge
- GOV.UK, Trusts and Inheritance Tax (updated 6 April 2025)
- GOV.UK, Inheritance Tax if you're a long-term UK resident (6 April 2025)
- GOV.UK, What qualifies for Business Relief (2026)
- GOV.UK, Corporation Tax rates and reliefs
- HMRC, Company Taxation Manual CTM03951, Close investment-holding companies
- HMRC, International Manual INTM653080, Distribution exemption for portfolio holdings
- GOV.UK, Tax on dividends
- GOV.UK, Company Tax Returns
- GOV.UK, Stamp Duty Land Tax: corporate bodies (updated 2 May 2025)
- GOV.UK, Stamp Duty Land Tax residential property rates
- GOV.UK, Annual Tax on Enveloped Dwellings: the basics (updated 4 March 2026)
- GOV.UK, Annual Tax on Enveloped Dwellings reliefs and exemptions (updated 2 May 2025)
- HMRC, Changes to tax relief for residential landlords (6 April 2017)
- HMRC, Property Income Manual PIM2052, Finance costs
- HM Treasury, Changes to tax rates for property, savings and dividend income (November 2025)
- legislation.gov.uk, Corporation Tax Act 2009, section 14
- HMRC, International Manual INTM120060, Central management and control
- HMRC, International Manual INTM600120, Transfer of assets abroad
- HMRC, International Manual INTM191100, Controlled foreign companies overview
- HMRC, Trusts, Settlements and Estates Manual TSEM4300, Settlements on minor children
- Companies House, Update to accounts filing from April 2028 (23 October 2026)
- GOV.UK, Companies House fees (updated 25 September 2026)
- GOV.UK, Verify your identity for Companies House (updated 30 April 2026)
- GOV.UK, People with significant control (updated 30 July 2026)
- GOV.UK, Penalties for late filing of annual accounts
- NatWest, Business current account
- Santander, Business current accounts
- Starling Bank, Business account eligibility
This article is general information, not tax or legal advice. Tax rules and rates change, and the tax result of a family investment company depends on the family's own circumstances. Confirm the structure with a qualified tax adviser before any assets go in. Binderr forms the company and files the documents the family and its adviser agree; it does not give tax advice.