Not every customer can be verified the same way. Checking an individual's identity differs from verifying a company with multiple shareholders and beneficial owners. Understanding the different types of KYC helps businesses prevent identity fraud, meet compliance requirements, and onboard customers securely.
The risks are significant. According to the Federal Trade Commission (FTC), US consumers reported losing $12.5 billion to fraud in 2024, a 25% increase from 2023. From individual and business verification to eKYC and biometric checks, various KYC types help businesses verify identities, assess risks, and strengthen financial crime prevention.
Choosing the right approach starts with understanding the types of KYC and their applications. Modern KYC software simplifies verification through automated identity checks, business verification, AML screening, and ongoing monitoring. This guide explains the main KYC methods, their requirements, key differences, and when businesses should use each.
Binderr KYC Verification Software
Manage individual and business verification through one unified compliance platform. Binderr helps businesses streamline onboarding, strengthen risk controls, and reduce manual verification work.
- Verify individual identities worldwide
- Automate business KYB verification checks
- Screen sanctions, PEPs, and watchlists
- Detect identity fraud and deepfakes
- Apply automated customer risk scoring
- Maintain centralised compliance audit trails
What Are the Different Types of KYC?
Know Your Customer (KYC) involves verifying customer identities, understanding their activities, and assessing financial crime risks. The different types of KYC include individual KYC, business KYC, eKYC, biometric KYC, and risk-based due diligence. Each of these KYC types serves a specific purpose, helping businesses meet compliance requirements, prevent fraud, and simplify onboarding.
Main Types of KYC at a Glance
The different types of KYC vary based on customer identity, verification methods, and risk levels. Each of these KYC types helps businesses address specific compliance requirements.
Here's a quick comparison of the main types of KYC, their purposes, and common use cases.
KYC Type | Primary Purpose | Common Use Cases |
Individual KYC | Verify a natural person's identity | Banking, fintech, crypto services |
Business KYC / KYB | Verify legal entities and ownership | Corporate banking, B2B onboarding |
Traditional KYC | Verify identities using manual or in-person procedures | Branch-based onboarding |
Electronic KYC (eKYC) | Verify identities through digital processes | Online banking, digital platforms |
Biometric KYC | Confirm identity using biometric characteristics | Remote identity verification |
Video KYC | Verify identity through live or recorded video procedures | Remote customer onboarding |
Simplified Due Diligence | Apply proportionate measures for lower-risk relationships where permitted | Qualifying lower-risk customers |
Standard CDD | Establish and verify customer identity and assess risk | Routine regulated onboarding |
Enhanced Due Diligence | Investigate higher-risk customers more deeply | High-risk PEPs, complex ownership |
Start KYC Verification for Free
Types of KYC Based on Customer Identity
The different types of KYC depend on whether a business is verifying an individual or a legal entity. Individual KYC focuses on personal identity, while business KYC examines company legitimacy, ownership, and control.
Both KYC types help businesses identify customers, assess financial crime risks, and meet regulatory requirements. However, their verification processes and documentation requirements differ.
Individual KYC (Personal KYC)
Individual KYC verifies a person's identity before onboarding or maintaining a business relationship. It involves collecting personal information, such as full name, date of birth, residential address, and government-issued identification. Businesses may also use biometric verification and document authentication to detect impersonation and identity fraud.
Among the types of KYC, personal KYC is commonly used by banks, fintech platforms, and financial service providers. It also includes sanctions and PEP screening and customer risk assessments. For example, someone opening an online bank account may upload a passport and complete a selfie-based liveness check before the bank approves onboarding.
Business KYC (Know Your Business / KYB)
Business KYC, also known as Know Your Business (KYB), verifies a company's legal existence, ownership, and legitimacy. The process involves checking company registration numbers, incorporation documents, registered addresses, directors, authorised representatives, and ultimate beneficial owners (UBOs). Unlike individual KYC, it examines corporate structures to identify who ultimately owns or controls the business.
Among the different types of KYC, KYB is particularly important for corporate banking, payment processors, and B2B financial services. For example, a payment provider onboarding an international company may verify its registry records, identify beneficial owners, and screen relevant parties against sanctions and PEP lists. Under the U.S. FinCEN CDD framework, covered legal entity customer checks generally include individuals owning 25% or more and one control person, subject to applicable exceptions. Other jurisdictions may apply different thresholds.
Unravel Complex Company Structures
Types of KYC Based on Verification Methods
The different types of KYC verification methods range from traditional document checks to automated digital identity verification. Each method helps businesses confirm customer identities, detect fraud, and meet compliance requirements.
While traditional KYC relies on physical documents and manual reviews, modern KYC types such as eKYC, biometric KYC, and video KYC enable faster remote verification. Choosing the right method depends on customer risk, regulatory requirements, and onboarding needs.
Traditional KYC (Offline KYC)
Traditional KYC, also called offline KYC, involves verifying customer identities through physical documents, face-to-face interactions, and manual procedures. Customers typically visit a bank or financial institution to submit identity documents, complete application forms, and have their information reviewed by compliance personnel.
Among the different types of KYC, traditional verification offers direct customer interaction but can involve lengthy processing times, paperwork, and administrative costs. For example, a bank employee may inspect a customer's passport, verify personal details, and manually record the information before approving account opening.
Electronic KYC (eKYC)
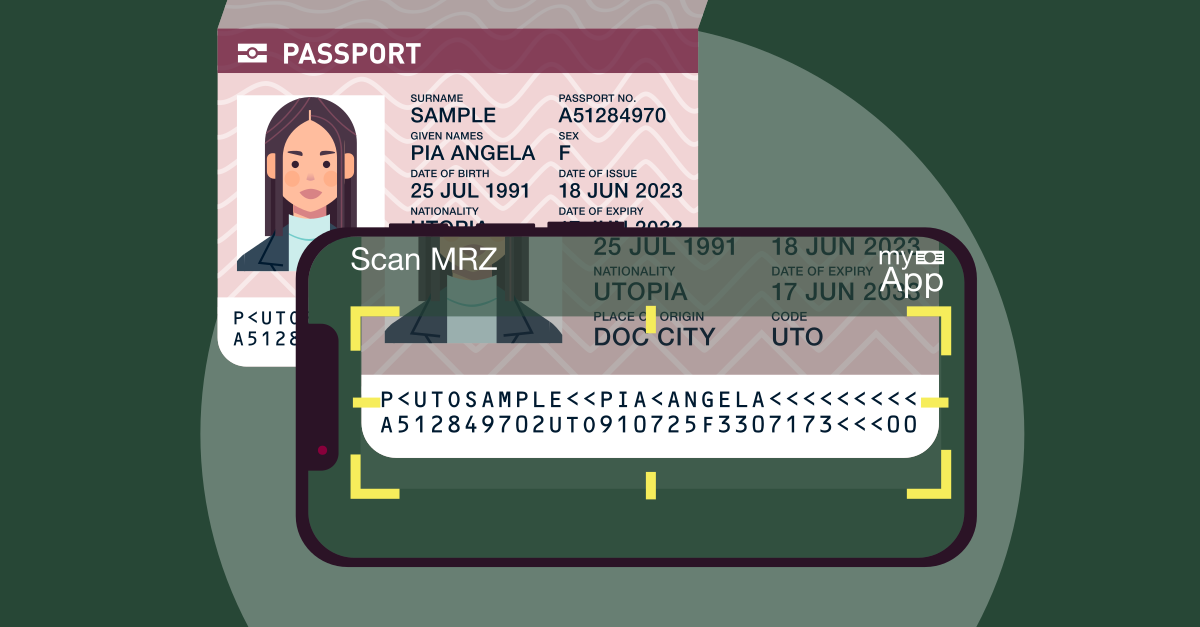
Electronic KYC (eKYC) uses digital technologies to verify customer identities electronically without requiring physical visits. It combines digital document capture, Optical Character Recognition (OCR), automated document authentication, identity data validation, and biometric matching where appropriate to streamline verification.
Unlike traditional KYC verification methods, eKYC supports faster onboarding and reduces manual paperwork. For example, a fintech customer can upload an identity document through a mobile app, complete a digital identity check, and receive verification results remotely. Reliable digital identity systems can also support customer due diligence when their security and assurance levels are appropriately assessed.
Biometric KYC
Biometric KYC verifies customer identities using unique physical characteristics, such as facial features or fingerprints. Facial recognition, selfie matching, and active or passive liveness detection help businesses determine whether the person presenting an identity document is its legitimate holder and detect potential spoofing attempts.
Among modern KYC types, biometric verification adds an identity assurance layer to digital onboarding, particularly where impersonation and deepfake fraud are concerns. For example, a customer takes a live selfie that is compared with their passport photograph. Businesses must also protect sensitive biometric information and comply with applicable privacy regulations.
Video KYC
Video KYC enables businesses to verify customer identities remotely through live video interactions or recorded verification sessions, where permitted. The process may involve an authorised agent inspecting identity documents, comparing facial features, assessing liveness, and recording verification evidence according to applicable legal requirements.
Among the types of KYC used for remote onboarding, video verification combines digital convenience with additional identity checks. For example, a customer opening a bank account may complete a live video session with a verification agent instead of visiting a branch. Financial institutions must follow jurisdiction-specific rules governing video verification, data protection, and fraud prevention.
Automate Your KYC Verification Process with Binderr
Move beyond manual checks with Binderr's integrated identity verification and compliance workflows.
- Verify IDs across 230+ countries
- Support 11,000+ identity document types
- Perform biometric facial matching checks
- Detect deepfakes and suspicious identities
- Streamline customer onboarding and reviews
- Manage verification records in one workspace
Types of KYC Based on Customer Risk Levels
The different types of KYC also depend on the level of financial crime risk associated with a customer.
Businesses apply simplified, standard, or enhanced due diligence based on factors such as customer profiles, geographic exposure, transaction activities, and potential money laundering risks.
Simplified KYC (Simplified Due Diligence)
Simplified KYC, also known as Simplified Due Diligence (SDD), applies reduced verification measures to customers assessed as lower risk, where regulations permit. Among the risk-based KYC types, SDD can involve fewer information requirements, streamlined verification, and proportionate monitoring. However, businesses must still meet applicable identification requirements and reassess customers if their risk levels change.
Standard KYC (Customer Due Diligence)
Standard KYC, or Customer Due Diligence (CDD), involves verifying customer identities, understanding the purpose of business relationships, and assessing potential financial crime risks. It typically includes identity verification, beneficial ownership checks where applicable, sanctions and PEP screening, and ongoing monitoring. Among the different types of KYC, standard CDD provides the baseline framework for identifying customers and managing routine compliance risks.
Enhanced KYC (Enhanced Due Diligence)
Enhanced KYC, commonly called Enhanced Due Diligence (EDD), involves additional verification and investigation for higher-risk customers or business relationships. It may include deeper beneficial ownership checks, source of funds and wealth verification, adverse media screening, senior management approval where required, and increased monitoring. Among the types of KYC due diligence, EDD provides greater scrutiny of complex corporate structures, higher-risk jurisdictions, and other significant financial crime risk indicators.
Access KYC Tools Today
How Do Different Types of KYC Work? Step-by-Step Process
The different types of KYC follow a structured verification process to confirm customer identities, assess financial crime risks, and meet compliance requirements.
Here's a step-by-step breakdown of how these KYC types work, from customer identification and verification to risk assessment and ongoing monitoring.
Step 1: Identify the Customer Type
The first step is determining whether the customer is an individual, a business, or another legal arrangement. This helps businesses select the appropriate types of KYC and establish the identification requirements based on customer profiles, legal structures, and regulatory obligations. A clear customer classification also ensures the right verification procedures are applied from the beginning.
For example, individual KYC focuses on personal identity verification, while business KYC requires checking company registration, ownership structures, and beneficial owners. Identifying the customer category early helps prevent unnecessary checks and onboarding delays.
Step 2: Collect Required Customer Information
Once the customer type is established, businesses collect essential information and supporting documents. Individual customers typically provide their full name, date of birth, address, and identity documents, while corporate customers may need to submit registration certificates, company details, and beneficial ownership information.
Digital onboarding platforms can simplify data collection through online forms, secure document uploads, and automated information extraction. Across different types of KYC, collecting accurate information from the beginning reduces verification errors and repeated document requests. Standardised data collection also helps compliance teams maintain consistent and complete customer records.
Step 3: Verify Identity or Business Legitimacy
The next step involves confirming customer information against reliable, independent sources. Businesses may use government-issued document authentication, biometric identity matching, official corporate registries, and electronic identity verification to establish whether the submitted details are genuine. These checks help detect forged documents, inaccurate information, and potential identity fraud before onboarding.
Verification methods vary across KYC types. For example, an individual may complete facial recognition and liveness checks, while a company undergoes registry verification and ownership analysis. Automated verification tools can accelerate these checks while flagging inconsistencies for further investigation.
Step 4: Conduct AML and Watchlist Screening
After establishing customer identities, businesses screen relevant individuals and entities against applicable sanctions lists, Politically Exposed Person (PEP) data, and adverse media sources. These checks help identify potential connections to financial crime, regulatory restrictions, or higher-risk activities.
For business customers, screening may extend to directors, authorised representatives, and beneficial owners. Across the different types of KYC, screening results require careful review because a potential name match does not automatically indicate wrongdoing or justify rejecting a customer. Proper alert investigation helps distinguish genuine compliance risks from false positives.
Step 5: Assess Customer Risk
Businesses evaluate the customer's financial crime risk based on factors such as geographic location, business activities, expected transactions, ownership complexity, and screening results. This assessment helps determine whether the customer presents lower, standard, or higher risks. The resulting risk classification guides the level of due diligence and monitoring required throughout the relationship.
Risk-scoring systems can simplify this process by combining relevant indicators into a documented customer risk profile. Regardless of the types of KYC performed, risk assessments help compliance teams identify unusual patterns and determine whether additional verification is necessary.
Step 6: Apply the Appropriate Due Diligence Level
Based on the risk assessment and applicable regulations, businesses apply the required level of customer due diligence. Standard CDD establishes baseline checks, Simplified Due Diligence (SDD) permits reduced measures for eligible lower-risk relationships, and Enhanced Due Diligence (EDD) involves additional investigation into higher-risk customers.
For example, a complex corporate structure may require deeper beneficial ownership analysis, source of funds verification, and additional monitoring. These risk-based KYC types help businesses apply proportionate checks without compromising regulatory obligations. Applying the appropriate due diligence level also prevents unnecessary verification while ensuring higher-risk relationships receive greater scrutiny.
Step 7: Approve, Escalate, or Reject the Customer
Once verification, screening, and risk assessments are completed, compliance teams decide whether to approve onboarding, request additional information, escalate the case, or reject the relationship. Decisions should reflect verified evidence, applicable regulations, and the organisation's risk policies. High-risk or unresolved cases may require additional investigation and senior compliance approval before a final decision.
For example, an unresolved identity discrepancy or potential sanctions match may require further investigation before onboarding proceeds. Across the different types of KYC, maintaining documented decisions and approval records supports accountability and regulatory audits.
Step 8: Monitor and Update Customer Information
KYC continues after onboarding through ongoing monitoring, customer information updates, and risk-based reviews. Businesses track relevant changes in sanctions exposure, PEP status, transaction behaviour, corporate ownership, and customer activities to identify emerging compliance risks.
Automated monitoring tools can flag material changes and trigger additional verification or due diligence when necessary. Across all types of KYC, maintaining updated customer records helps businesses detect new risks, support regulatory compliance, and manage customer relationships securely. Regular reviews also ensure that customer risk profiles remain aligned with changing activities and regulatory expectations.
Streamline Every Step of KYC With Binderr
From initial customer verification to enhanced due diligence and ongoing monitoring, Binderr brings essential compliance checks into one workspace.
- Combine KYC, KYB, and AML checks
- Automatically assign customer risk scores
- Trigger enhanced due diligence workflows
- Collect and verify supporting documents
- Receive continuous risk monitoring alerts
- Maintain comprehensive records and audit trails
Which Type of KYC Should Your Business Use?
Understanding the different types of KYC helps businesses select appropriate identity checks, corporate verification methods, and due diligence levels. Here's how KYC requirements vary across major industries.
KYC for Banks and Financial Institutions
Banks and financial institutions typically use individual KYC, business KYC, and risk-based due diligence to verify account holders and corporate customers. These KYC types involve identity document verification, beneficial ownership checks, sanctions and PEP screening, customer risk assessments, and ongoing transaction monitoring.
For example, a retail bank may use biometric eKYC for remote account opening, while corporate banking teams conduct KYB verification and enhanced due diligence for higher-risk businesses. Combining digital identity verification with continuous monitoring helps financial institutions manage compliance risks throughout customer relationships.
KYC for Fintech and Payment Companies
Fintech platforms and payment providers often rely on eKYC, biometric verification, and automated AML screening to onboard customers quickly and securely. Among the different types of KYC, digital verification is particularly valuable for businesses managing high onboarding volumes, remote users, and cross-border payment activities.
For example, a payment app may verify users through document scanning and selfie-based liveness checks, while a payment processor conducts KYB checks on merchants and beneficial owners. Automated identity verification and risk scoring help fintech companies reduce manual reviews, detect suspicious activity, and improve onboarding efficiency.
KYC for Cryptocurrency and Virtual Asset Services
Cryptocurrency exchanges and regulated Virtual Asset Service Providers (VASPs) use identity verification, digital KYC, AML screening, and risk-based due diligence to identify customers and manage financial crime exposure. Depending on applicable regulations, these types of KYC may include verifying personal identities, identifying beneficial owners, screening sanctions and PEPs, and assessing risks linked to virtual asset transactions.
For example, a cryptocurrency exchange may use eKYC to verify a new customer before enabling regulated services, then monitor relevant transactions for unusual activity. Higher-risk relationships may require enhanced due diligence, including additional source of funds information and closer monitoring of transaction patterns.
KYC for Corporate and B2B Platforms
Corporate and B2B platforms primarily use business KYC, also known as Know Your Business (KYB), to verify company legitimacy, ownership structures, and authorised representatives. These KYC types involve checking company registration records, incorporation documents, directors, shareholders, and ultimate beneficial owners, alongside risk-based AML screening where appropriate.
For example, a B2B financial platform onboarding an international company may verify its legal registration, map ownership relationships, and screen relevant individuals against sanctions and PEP lists. Integrating KYB verification with automated risk assessments helps businesses identify hidden ownership risks, streamline corporate onboarding, and meet applicable compliance obligations.
KYC for Marketplaces and Digital Platforms
Online marketplaces and digital platforms may use individual KYC, business verification, and biometric identity checks to verify sellers, merchants, and other platform participants. The appropriate types of KYC depend on the platform's activities and legal obligations, with verification helping reduce impersonation, fraudulent accounts, and unauthorised transactions.
For example, an e-commerce marketplace may verify an individual seller's identity through digital document checks while reviewing business registration details for corporate merchants. Combining these different types of KYC with ongoing risk reviews helps platforms maintain trusted user relationships, prevent fraudulent activity, and support secure digital transactions.
Start Using Binderr for FREE
How KYC Software Automates Different Types of Verification
Modern KYC software simplifies the different types of KYC by combining identity verification, business checks, AML screening, and risk management into one platform.
Automated workflows reduce manual effort, accelerate onboarding, and help businesses maintain consistent compliance processes.
Automated Identity and Document Verification
Automated KYC verification uses Optical Character Recognition (OCR), document authentication, biometric matching, and liveness detection to verify customer identities digitally. Advanced fraud detection tools can identify forged documents, suspicious identities, and potential deepfake attempts. Across various KYC types, these technologies help businesses speed up onboarding, reduce verification errors, and strengthen identity security.
Integrated Business Verification and UBO Identification
KYC compliance software streamlines business verification by checking corporate registry records, validating company details, and identifying ultimate beneficial owners (UBOs). Automated ownership mapping helps uncover complex shareholder structures, while integrated screening checks directors, shareholders, and beneficial owners for potential compliance risks. Among the different types of KYC, these capabilities are particularly valuable for corporate onboarding and KYB verification.
Automated AML Screening and Risk Scoring
Modern KYC platforms integrate sanctions screening, Politically Exposed Person (PEP) checks, and adverse media monitoring to identify potential financial crime risks. Configurable risk rules automatically assess customer profiles, assign risk scores, and flag suspicious matches for compliance review. Across the types of KYC, automated AML screening reduces repetitive checks, supports consistent risk assessments, and helps compliance teams prioritise higher-risk cases.
Enhanced Due Diligence and Ongoing Monitoring
KYC software supports Enhanced Due Diligence (EDD) by triggering additional document requests, escalating higher-risk customers, and maintaining detailed compliance records. Ongoing monitoring tools detect changes in sanctions exposure, PEP status, ownership structures, and customer risk profiles, generating alerts for investigation. These capabilities help businesses manage different KYC types throughout the customer lifecycle while maintaining audit-ready documentation.
Binderr: One Platform for Every KYC and KYB Workflow
Simplify individual onboarding, business verification, and ongoing due diligence with Binderr's integrated compliance tools.
- Verify customers and business entities
- Identify ultimate beneficial owners faster
- Screen global sanctions and PEP lists
- Automate enhanced due diligence processes
- Monitor customer risk changes continuously
- Start free without credit card details
Bottom Line
The different types of KYC play distinct but connected roles in verifying customers and preventing financial crime. Individual KYC confirms personal identities, business KYC verifies company legitimacy and ownership, while eKYC and biometric verification simplify digital onboarding. Risk-based KYC types, including SDD, standard CDD, and EDD, help businesses apply the appropriate level of scrutiny based on customer risk and regulatory requirements.
Choosing the right types of KYC helps businesses strengthen compliance, prevent fraud, and build customer trust without slowing down onboarding. Binderr Services simplifies this process by bringing identity verification, KYB checks, AML screening, automated risk scoring, and ongoing monitoring into one unified platform, helping businesses manage compliance more efficiently.