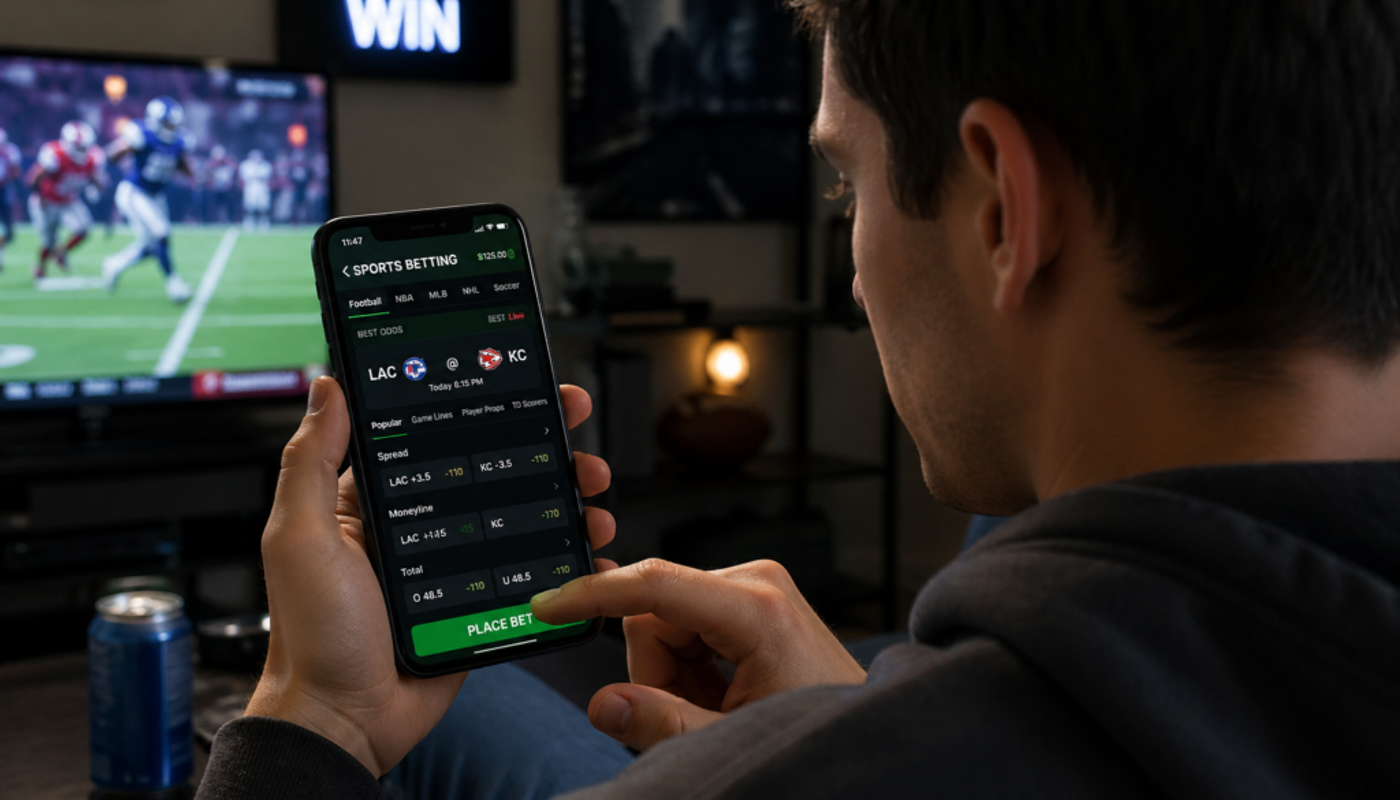
A betting payment gateway lets your sportsbook take deposits by card, bank transfer and local payment methods, credit them to the bettor's balance in seconds and pay winnings back out. Fast deposits decide whether a bet goes on before kick-off or during a live match, and fast payouts bring winners back the following weekend.
Approval takes more work than for an ordinary online store. Visa puts online gambling in its highest risk tier, so only acquirers that Visa has separately approved for betting can take you on. Most mainstream processors refuse sportsbooks outright. Every regulator also sets its own payment rules, and underwriters check your licence, age checks and geolocation before the first deposit.
We make that part simple. Binderr Chooses is a short intake form: you describe the sportsbook, and we place it with a regulated partner that takes betting. We build the file the underwriter reads, from licence to cashier, and run the application with you. Most operators accept deposits within 5 to 7 business days.
High Risk Payment Gateway and Merchant Account
Binderr Chooses
Time to onboard
5 to 7 days
Currencies
USD, EUR, GBP and more
Industries
Gambling, Adult, CBD, Crypto, Travel, Forex and more
What Is a Betting Payment Gateway?
A betting payment gateway is the link between your sportsbook's cashier and an acquirer that has chosen to process gambling payments. A bettor presses deposit, the gateway passes the request to the card issuer or the bank, and within a second or two your platform hears back and credits the balance so the bet can go on. The money then settles into your merchant account and on to the company's bank account. The basics match how a payment gateway works in any sector. Betting differs in two ways: the acquirer has to be approved for gambling, and money goes back out to winners every single day.
Why Card Schemes Treat Sports Betting as High Risk
A deposit into a betting account is not a purchase. The bettor is paying for the chance to win money, and a bettor who loses has a reason to tell the bank the payment was never theirs. The law changes at every border, and in the US at every state line. Stolen cards are used to fund accounts and pull winnings out somewhere else, and under-age players try to get in. Under Visa's rules, every online gambling transaction carries MCC 7995 (Betting), even for a merchant whose main business is something else. In the Asia Pacific, Canada, CEMEA, Latin America and US regions, each deposit also carries a quasi-cash and online gambling flag. Issuers see both, and some decline the deposit or price it as a cash advance.
The US has its own codes on top. Visa reserves MCC 7801 for online gambling licensed by a US government body and registered with Visa, and MCC 7802 for licensed horse and dog racing. A US merchant whose transactions qualify must use those codes, so issuers can see that the operator holds a US licence. Our guide to gambling payment gateways covers casino and lottery products next to betting.
Sportsbook Payment Gateway vs Mainstream Processors
Stripe lists sports forecasting or odds-making with a monetary or material prize among its prohibited businesses, next to internet gambling and lotteries. PayPal treats sports betting as an activity that needs its approval in advance, and it gives that approval only where both the operator and its customers are in places where betting is legal. An account opened without that approval is at risk at the first review, often with the balance frozen while bettors wait for their withdrawals.
A sportsbook payment gateway starts from the other end. The acquirer reviews your licence, cashier and website, registers you with the card schemes, and only then processes the first deposit. The high risk payment processing model explains why that order protects you once volume arrives.
What a Sportsbook Needs From Its Payment Gateway
A betting operator asks much more of a gateway than an online shop does. The core list is short:
- Deposit confirmation in seconds: the balance is credited before the odds move or the market closes
- 3D Secure on card deposits: authentication that reduces fraud claims on deposits
- Name matching: money accepted only from cards and accounts in the bettor's own name
- Payouts to winners: card payouts, bank transfers and the local methods each market allows
- Withdrawal rules: money sent back to the methods that funded the account
- Cashier controls: credit card blocking, deposit limits and self-exclusion checks
- Peak capacity: no slowdown when a big match kicks off
Most gateways can do this on paper. The question for a sportsbook is whether the acquirer behind the gateway holds Visa's gambling approval and wants to underwrite betting at your volumes.
Set Up a Betting Payment Gateway for Your Sportsbook
Card and bank deposits through a regulated partner that already approves betting, with your file prepared first.
- Partners cleared for betting: acquirers with Visa approval for gambling payments.
- Deposits credited in seconds: balances topped up before kick-off, not after it.
- Winnings out fast: card payouts and bank transfers ready at launch.
- Methods per market: debit cards plus the local methods your licence allows.
- Pre-match and in-play: one setup for both, sized for match-day peaks.
- Taking bets in days: a complete file usually goes live in 5 to 7 business days.
Card Scheme Rules for a Betting Payment Gateway
Two permissions sit behind every approved sportsbook. The acquirer needs the card schemes' approval to handle gambling at all, and it then has to register your business with each scheme before your first deposit. Neither step can be skipped, and both depend on the file you give the acquirer. The same steps for other sectors are set out in registering high risk merchants with Visa and Mastercard.
Visa Tier 1 and MCC 7995
Under Visa's Integrity Risk Program, card-absent gambling (MCC 7995) is a Tier 1 business, the top tier, which it shares with adult content, dating and escort services, and pharmacies. No acquirer can sign a merchant in any tier until Visa has granted it high integrity risk registration. For Tier 1, the acquirer also needs a separate Visa approval for each category, given after an initial control assessment, and it must complete a control self-assessment every year. An acquirer approved for adult content is not approved for betting until Visa says so.
Then, sportsbook by sportsbook, the acquirer reviews your control environment in depth, confirms to Visa that you passed, registers you before your first transaction and keeps the record current, URLs included. After that, it certifies every year that you still operate lawfully and can block illegal transactions. Every new domain, app or brand changes the registration, so declare it before launch, not after.
Visa Rules on Licences and Gambling Codes
Visa's Core Rules, in the April 2026 edition, set three duties for any online gambling merchant. The website or app needs a valid licence or other appropriate authority behind it. Every gambling transaction must be coded as MCC 7995, or with the US codes where they apply. And if you cannot separate betting from your other sales, every transaction must be treated as gambling and your customers told it may appear that way on their statements.
One more rule hits US operators hard. For domestic US online payments, 3D Secure does not protect a merchant coded MCC 7801, 7802 or 7995 from card-absent fraud disputes, although it still does for ordinary online sales. A US sportsbook therefore wins fraud disputes on evidence, not on authentication, which the chargeback section below covers.
Mastercard Registration and 2026 Fees
Mastercard counts non-face-to-face gambling as a specialty merchant category, so your acquirer registers you under its Specialty Merchant Registration Program before processing anything. Bulletin 12568.1, dated 28 October 2025, raised the price of that programme in four regions: the United States, the Middle East and Africa, Asia Pacific except Japan and Indonesia, and Latin America and the Caribbean except Brazil, Mexico and Colombia. Since 1 May 2026, an acquirer there pays USD 1,000 each year for every specialty merchant it registers, and USD 50,000 each year for the new high-risk acquirer licence. Since 3 June 2026, every specialty merchant transaction in those regions also carries 10 basis points of its value plus USD 0.02.
Say your sportsbook processes 3,000 Mastercard deposits a month in one of those regions, at USD 50 on average. That is USD 150 in volume fees and USD 60 in transaction fees, so USD 210 a month before the acquirer adds anything. The bulletin also required any acquirer declining the licence to unregister and terminate its specialty merchants, so expect a shorter list of acquirers for betting in those regions. Check whether your quote includes these fees or lists them separately.
How Registration Affects Your Sportsbook Launch
Visa and Mastercard never hear from you directly. The acquirer registers you from your file: the licence, every domain and app that takes deposits, each brand or white-label skin on your platform, and the countries or states you accept bettors from. An operator running three skins on one platform has three sets of URLs to declare. Put every one of them in the first file. A skin added after approval goes back through registration, and it cannot take card deposits until the acquirer has updated Visa.
High Risk Payment Gateway and Merchant Account
Binderr Chooses
Time to onboard
5 to 7 days
Currencies
USD, EUR, GBP and more
Industries
Gambling, Adult, CBD, Crypto, Travel, Forex and more
How to Get a Payment Gateway for Betting
To get a payment gateway for betting approved, you need a licence for every market you take bets from, KYC and age checks that run before the first bet, geolocation where the law requires it, a website and app that meet the card scheme rules, safer gambling tools at the cashier and a complete company file. Underwriters check all of it before they register you. A gap in any one of them is what turns a week into a month.
A Sportsbook Licence for Each Market
The licence comes first, and acquirers read it market by market. In Great Britain, you need a remote betting operating licence from the Gambling Commission under the Gambling Act 2005, and since 1 November 2014 that applies to any operator taking bets from British customers, wherever it is based. In Malta, the Malta Gaming Authority licenses fixed-odds betting, live betting included, as a Type 2 game. Betting exchanges fall under Type 3 and virtual sports under Type 1, so a sportsbook that adds an exchange or virtual sports needs those covered too. How to get a sports betting licence goes through the main options.
The licence must also match your traffic. A Malta licence does not let you take bets from Ontario, and a New Jersey licence covers bettors in New Jersey only. Underwriters compare your licences with your traffic and payment data, and bettors from a market you are not licensed for are a reason to decline. Our guides to the UK Gambling Commission licence, starting a sports betting company in Malta, the Isle of Man gambling licence and the Gibraltar gaming licence cover the routes acquirers know best.
KYC, Age Checks and Geolocation
Underwriters expect every bettor to be identified before any money moves. In Great Britain, operators have had to verify a customer's name, address and date of birth before letting them gamble since 7 May 2019. In the US, the minimum age is 21 in most states, and Massachusetts writes it into its sports wagering law. US operators must also confirm by geolocation that the bettor is physically inside a licensed state when each bet is placed, and acquirers ask how that check connects to your deposits.
Screen bettors against sanctions and PEP lists, ask for source of funds once deposits pass your risk limits, and refuse cards or bank accounts in another person's name at the cashier. Most sportsbooks automate these steps with the ID verification and fraud detection tools used across regulated sectors.
Website and Betting App Requirements
Visa lists what an online gambling merchant must show on its homepage or payment page. That includes a statement that internet gambling may be illegal where the bettor is located and that, if so, they are not authorised to use their card for the payment. It also requires a statement that the bettor must know the gambling law in their own country, a ban on under-age play, a full description of the rules of play, cancellation and payout policies, and advice to keep copies of transaction records. In Europe, your privacy policy is added to the list. Underwriters check these before they look at anything else.
Apps add a second gatekeeper. Apple requires real-money gaming apps, sports betting included, to hold the licences needed where the app is used, to be geo-restricted to those places and to be free to download, and it bars in-app purchase of credit for real-money gaming. Google Play requires an approved application, a valid licence for each country or state the app serves, and no use of Google Play billing. So the payment gateway for a betting app always runs through your own cashier inside the app, never through the app store's billing.
Safer Gambling Tools at the Cashier
Underwriters read your cashier as a safer gambling control, not only as a payment page. They look for deposit limits, time-outs, self-exclusion that stops deposits at once, and links to national schemes such as GAMSTOP in Great Britain. Since 31 October 2025, British operators must prompt customers to set a financial limit before their first deposit. These tools are licence conditions in most regulated markets, and an acquirer that finds them missing assumes your licence is at risk as well.
Documents Needed for a Sportsbook Payment Gateway
You apply as a company. Expect the underwriter to ask for:
- Company documents: certificate of incorporation, the director and shareholder registers, and an ownership chart that reaches every ultimate beneficial owner
- Passports or ID cards and proof of address for each director and every owner with 25% or more
- Your gambling licences, with the products and markets each one covers
- AML, KYC and safer gambling policies
- A list of every domain, app and brand that will take deposits
- Recent card processing statements, ideally three to six months, if you already take payments
- Expected monthly volume, average deposit size and your peak days in the sports calendar
Underwriters apply the KYB standards used across fintech and payments, so a gap anywhere in the ownership chain stops the file early. You also need a settlement account, and many banks turn betting companies away on sight, a problem our guide to a bank account for a gambling company deals with. Having no processing history does not rule you out. New sportsbooks are approved regularly, usually starting on a larger reserve and a lower monthly cap until a track record builds.
A Sportsbook Payment Gateway Without the Rejections
Most betting applications stall on the same few gaps, and we close them before an underwriter opens the file.
- Every market licensed: each country and state you serve is covered.
- Visa notices in place: gambling statements and payout rules on site and in app.
- Skins and apps declared: every URL listed before registration starts.
- Cashier rules tested: credit card blocks, limits and name checks working.
- Ownership file complete: company, owners and directors documented once.
- First answer next day: preliminary approval usually lands within one business day.
- Underwriter questions handled: we answer them while you run the book.
Deposits and Withdrawals on a Betting Payment Gateway
Betting money moves fast in both directions. Deposits bunch up before kick-off and during live matches, and withdrawals follow within hours of the final whistle. The gateway has to handle both without delay, because a slow deposit loses a bet and a slow withdrawal starts a dispute.
Instant Deposits for Pre-Match and In-Play Bets
Pre-match betting gives a bettor time to deposit. In-play betting does not. Odds move with every attack and many markets are suspended for a few seconds after a goal or a red card, so a deposit that takes thirty seconds to confirm can cost the bet altogether. Ask for the gateway's response time at peak load, not its average, and have deposits confirmed to your platform by a server message rather than by the bettor returning to the page.
Volume follows the fixture list. Saturday afternoons, Champions League nights and major tournaments such as the World Cup can multiply an ordinary day's deposits. Agree your monthly cap and daily limits against those peaks, not against a quiet month, and keep a second acquirer ready for overflow and outages.
Cards, Bank Payments and Local Methods
Debit cards carry most first deposits, but the mix changes by market. Credit cards are banned for betting in Great Britain and Brazil. In the US, the CFPB reported in December 2024 that several large card issuers treat online gambling as a cash advance, most often charging the greater of USD 10 or 5% plus a higher interest rate, and that cardholders tend to switch method after the first fee. Online banking and ACH transfers are standard in the US, open banking in Great Britain and much of Europe, Pix in Brazil and Interac in Canada.
Bank-based methods sit outside card chargeback rules, cost less per deposit and suit larger amounts, although US ACH debits can still be returned as unauthorised. Crypto deposits run under separate rules, set out in our guide on taking crypto payments for gambling and gaming.
Paying Winnings Back to Bettors
Visa is strict here. A gambling merchant may pay winnings to a Visa card only through an Original Credit Transaction. Cash, cheques and refund-type credits are not allowed, and the winning bet must have been lawful, correctly coded and processed under Visa's rules. Inside Europe there is one more condition: the payout goes to the same card that was used for the winning bet.
Payout speed is set on the bettor's side. The card issuer has 2 business days to post a payout, or the same business day when the payout stays inside Europe. Banks that take part in Visa's fast funds service have to release the money within 30 minutes, cut to 60 seconds for domestic US payouts. Not every card, bank or country supports card payouts, so check which of your markets do before you promise instant withdrawals.
Closed-Loop Withdrawals and Bank Payouts
Most licensed sportsbooks run a closed loop. Money goes back to the methods that funded the account: the card first, up to what the card paid in, and the rest to a bank account in the bettor's own name. A bettor who deposits EUR 150 by card and EUR 350 by bank transfer, then withdraws EUR 900, gets EUR 150 back on the card and EUR 750 by bank transfer. Write the rule into your terms and repeat it on the withdrawal screen.
The loop does two jobs. It stops a stolen card being used to fund an account while the winnings are cashed out somewhere else, and it gives you a clear answer when a bank asks where its customer's money went. Withdrawals also need to be quick. A bettor kept waiting for a payout often calls the bank about the deposit instead, and in Great Britain the Gambling Commission has made clear that operators cannot confiscate deposits or winnings because ID arrived late. The full deposit and payout flow is set out in how casino payment gateways work.
Multi-Currency Settlement for Sportsbooks
Bettors deposit in pounds, euros, Canadian dollars or reais, and you pay winnings in the same currency. Every conversion the gateway makes costs roughly 1% to 2%. A sportsbook that converts on the way in and again on the way out pays that margin twice on the same money, so settle and hold balances in the currencies you pay winners in. Brazil is a special case, because betting money there must be held with institutions authorised by the Central Bank of Brazil. For settlement across several markets, see international payment gateways. Where the balances themselves should sit is covered in our review of banks that work with casino and iGaming companies.
High Risk Payment Gateway and Merchant Account
Binderr Chooses
Time to onboard
5 to 7 days
Currencies
USD, EUR, GBP and more
Industries
Gambling, Adult, CBD, Crypto, Travel, Forex and more
What a Betting Payment Gateway Costs
Sportsbook pricing reflects the scheme rules above and the dispute risk the acquirer carries. The ranges below are typical for a licensed operator with a complete file, taken from the lower side of the market.
Cost item | Typical range |
|---|---|
Setup fee | USD 0 to USD 500 |
Monthly account fee | USD 10 to USD 50 |
Processing rate | 2.5% to 5% of each deposit |
Fee per transaction | USD 0.10 to USD 0.35 |
Gateway fee | USD 10 to USD 30 a month plus USD 0.05 to USD 0.15 per transaction |
Chargeback fee | USD 15 to USD 35 per dispute |
Rolling reserve | 5% to 10% of deposits, held for 90 to 180 days |
Currency conversion | Around 1% to 2% when a conversion is needed |
Picture a sportsbook taking USD 400,000 a month by card across 8,000 deposits, so USD 50 on average. At 4% plus USD 0.20, processing costs USD 16,000 plus USD 1,600. A gateway fee of USD 20 a month plus USD 0.08 per deposit adds USD 660, and the account fee another USD 40. The month comes to USD 18,300, or about 4.6% of deposits. On a USD 50 deposit the fixed fees alone are USD 0.28, or 0.56%, which is why small, frequent betting deposits cost more than the headline rate suggests. Each line is broken down in our guide to high risk merchant account pricing.
Payout fees are the line operators forget. Each card payout or bank transfer to a winner is a separate transaction with its own price, and a busy sportsbook sends thousands a month. Get that price in writing next to the deposit rate.
Rolling Reserves and Payout Cash Flow
A rolling reserve holds back part of each month's deposits to cover future disputes. At 7% held for 120 days on USD 400,000 a month, USD 28,000 is held each month, and after four months the acquirer holds about USD 112,000. For a sportsbook the reserve competes with the cash you need to pay winners, and a weekend where the favourites all win can drain the payout balance fast. Plan payout funds separately from the reserve, and ask for a review after six months of clean processing.
Setup Timeline for a Sportsbook
Partner onboarding follows the stages in the table. With a complete file, a sportsbook is usually live inside 5 to 7 business days, and setting up a high risk payment gateway explains what happens at each stage.
Stage | Typical time |
|---|---|
Quick assessment | 5 minutes |
Preliminary approval | 1 day |
Complete onboarding requirements | 15 minutes |
Provision of services | 3 days |
Total | 5 to 7 business days |
Licence questions, undeclared skins and missing ownership documents are what push the timeline out. Settle them before you apply and your first test deposit can follow soon after approval. For the merchant account underneath, read about opening a high risk merchant account.
Scale Your Sportsbook on an Online Betting Payment Gateway
Terms that suit small, frequent deposits and an operator that keeps adding markets, agreed in writing before launch.
- Fixed fees in focus: priced for small, frequent betting deposits.
- Reserve fixed before launch: rate and holding period agreed in writing.
- Mastercard costs explained: 2026 specialty fees shown, not buried in the rate.
- Caps for match days: limits sized for your busiest fixtures.
- Markets added as you grow: extra countries and states declared for you.
- Payout fees in writing: what each transfer to a winner costs, up front.
Sports Betting Payment Gateway Rules by Market
Each regulator sets its own payment rules for betting, and several now enforce their licensing through payment providers. The acquirer checks that your cashier follows the rules of every market you serve. This is what the main markets change for payments.
Market | What it changes for payments |
|---|---|
Great Britain | No credit cards since 14 April 2020, financial checks above GBP 150 net deposits in 30 days, deposit limits at the cashier |
United States | A state licence and a geolocation check for every bet, MCC 7801 or 7995, credit cards banned in some states |
Brazil | Pix, TED, debit and prepaid cards only, from the bettor's own account, with credit cards and crypto banned |
Ontario | AGCO registration and an iGaming Ontario operating agreement before the first deposit |
European Union | A licence in each country, and Visa winnings paid back to the card that placed the bet |
Great Britain
Gambling with a credit card has been banned since 14 April 2020, and the ban reaches e-wallets topped up by credit card, so your cashier needs card BIN checks and checks on how a wallet was funded. Since 28 February 2025, operators must run light-touch financial vulnerability checks once a customer's deposits minus withdrawals pass GBP 150 in a rolling 30 days, down from GBP 500 when the checks began on 30 August 2024. Since 31 October 2025, customers must be prompted to set a financial limit before their first deposit. From 30 September 2026, operators must offer deposit limits based only on money paid in, a deadline the Commission moved from 30 June 2026. All of this runs through the cashier, so your platform needs deposit and withdrawal data per customer in real time, not at month end.
United States
The Supreme Court struck down the federal ban on state-authorised sports betting in Murphy v NCAA on 14 May 2018. By October 2026, 39 states and Washington DC allowed sports betting in some form, and 32 states plus DC allowed it online. Each state licenses separately, and every online bet needs a geolocation check that the bettor is inside the state. Under the Unlawful Internet Gambling Enforcement Act of 2006 and Regulation GG, card systems must have policies to identify and block unlawful internet gambling payments, and the vast majority do it through merchant and transaction codes.
That coding is one reason approval rates on US sportsbook deposits vary so much from issuer to issuer. Massachusetts bans credit cards for sports wagering by law, several other states have done the same, and the largest US sportsbooks stopped taking credit card deposits during 2025 and 2026. Plan for debit cards, online banking and ACH as your main methods.
Brazil
Law 14,790 of 29 December 2023 set the rules for fixed-odds betting, and the fully regulated market started on 1 January 2025, with operators authorised by the Ministry of Finance. Ordinance SPA/MF 615, dated 16 April 2024, then fixed how money moves. A bettor can fund an account or withdraw only through Pix, TED, a debit or prepaid card, or a transfer inside the same bank, and the money must move between an account registered in the bettor's name and the operator's account at a bank the Central Bank has authorised. Credit cards, cash, boletos, cheques and crypto are all ruled out. The law also forbids payment institutions from processing bets for operators without authorisation, so no sports betting payment gateway can rescue an unlicensed brand in Brazil.
Ontario and Canada
Canada made single-event sports betting legal from 27 August 2021, and Ontario opened its regulated market to private operators on 4 April 2022. An operator must register with the Alcohol and Gaming Commission of Ontario and sign an operating agreement with iGaming Ontario before it can take a bet, and acquirers ask to see both. Interac is widely used by Canadian bettors next to cards, so plan for it from launch.
European Union
There is no EU-wide betting licence. Each member state licenses betting itself, and some act through payments. Germany's Joint Gambling Authority can order payment providers to stop serving unlicensed operators, and in October 2024 the Administrative Court of Halle upheld such an order against a Swiss payment provider. Visa's European rule that winnings go back to the card that placed the winning bet applies across the region. Setting up an online sports betting company in Europe and starting an iGaming business in Malta cover the licensing side.
High Risk Payment Gateway and Merchant Account
Binderr Chooses
Time to onboard
5 to 7 days
Currencies
USD, EUR, GBP and more
Industries
Gambling, Adult, CBD, Crypto, Travel, Forex and more
Chargebacks on a Sportsbook Payment Gateway
Disputes decide how long a sportsbook keeps its card processing. The schemes measure them every month, and acquirers watch betting merchants more closely than almost any other sector.
Why Bettors Dispute Deposits
Most betting disputes do not involve stolen cards. A bettor loses a weekend's stakes and tells the bank the deposits were not theirs. A partner or a child used a saved card. A bettor who self-excluded elsewhere claims you should have stopped them. Or a withdrawal stalled, and the bettor disputes the deposit to get the money back faster. Each one is fought with different evidence, and that evidence has to be collected before any dispute lands.
Bonus Abuse, Multi-Accounting and Account Takeover
Welcome offers attract organised abuse. Groups open many accounts with different cards and addresses to claim the same free bet, then move the winnings out together. Account takeover works the other way round: a fraudster logs in with stolen details and tries to withdraw to a new card. Device fingerprinting, one verified payment method per person and withdrawals only to methods already used for deposits stop most of it.
Evidence That Wins a Betting Dispute
For every deposit, keep:
- KYC record: documents proving the cardholder and the account holder are the same person
- Authentication result: the 3D Secure outcome for the deposit
- Device and login data: device ID or fingerprint, IP address and login ID for the session
- Bet history: each bet placed with the deposit, with time, odds, stake and result
- Payout history: winnings already paid to the same card or bank account
- Limits and contacts: deposit limits set and any safer gambling contact with the bettor
Visa's Compelling Evidence 3.0 rules turn that data into a defence against card-absent fraud claims. The acquirer can challenge the claim when the same card was used for two earlier transactions not reported as fraud, made more than 120 days and no more than 365 days before the dispute, and the device ID or fingerprint, or the IP address, matches along with one more detail such as the login ID. The 120-day minimum does not apply when those earlier transactions were Original Credit Transactions, so a bettor who was paid winnings to the card leaves you strong evidence. In the US this matters even more, because 3D Secure gives gambling merchants no protection against those claims.
Visa and Mastercard Dispute Limits for Sportsbooks
On 1 April 2026, Visa cut the merchant threshold in its acquirer monitoring programme from 2.2% to 1.5% for the US, Canada, Europe and Asia Pacific. A merchant is flagged when fraud reports plus disputes reach 1.5% of its settled card-absent transactions and number at least 1,500 in the month. Cases resolved through pre-dispute tools, and fraud that qualifies for Compelling Evidence 3.0, are kept out of that ratio, which is a strong reason to use both. On the Mastercard side, the excessive chargeback programme begins at 100 chargebacks in a month with a ratio of 1.5%. In practice acquirers step in sooner, often around 1%. An acquirer that closes a sportsbook for excessive disputes can add it to Mastercard's MATCH list, where it stays for 5 years. The tools that keep ratios down are covered in chargeback management for high risk merchants.
Keep Disputes Low on Your Betting Payment Gateway
A low dispute ratio brings a smaller reserve and a longer life for the account, so the controls go in before the first deposit.
- Login and device data kept: the records Visa asks for in a fraud dispute.
- Bettor name matching: only cards issued to the person who holds the account.
- Pre-dispute refunds: cases closed early stay out of the Visa ratio.
- Withdrawals to known methods: winnings sent only where deposits came from.
- Bonus abuse checks: one account per person, verified at deposit.
- Ratios watched monthly: disputes kept well under the 1.5% scheme lines.
Best Payment Gateways for Sports Betting Platforms
Nobody can rank the best payment gateways for sports betting platforms for you in the abstract. The right choice turns on where you hold licences, which markets you serve and how much you process. What the strong ones have in common is clearer: a proper approval, deposits confirmed in seconds, winners paid on time and an account still open twelve months later. Those are the points we check before placing a sportsbook with a partner. It is also why we do not hand over a list of payment gateway providers for sports betting for you to call one at a time.
Approved for Gambling by Both Card Schemes
Payment gateways for a sports betting platform all sit on an acquirer, and that acquirer needs Visa's Tier 1 approval for gambling and the ability to register you with Mastercard. In the 2026 fee regions it also needs Mastercard's high-risk acquirer licence. Without them, the gateway cannot process your deposits at all, whatever the rate.
Speed When Bets Go On
Look for deposit confirmation in a second or two, uptime commitments in writing and proof that the gateway held up during a major tournament. Ask how it handles a surge of first deposits from new accounts in the hour before a big match, because that is when fraud rules and capacity are tested together.
Payouts to Winners on Time
Card payouts, bank transfers and local payout methods should all run from the same cashier, linked to your platform so withdrawals need no manual work. Ask which of your markets support instant card payouts and what happens when a payout fails.
Local Methods in Each Licensed Market
A sportsbook licensed in Brazil needs Pix, one licensed in a US state needs online banking and ACH, and one licensed in Great Britain needs open banking next to debit cards. Many betting sites' payment gateway setups still lean on cards alone, which leaves deposits behind wherever bank payments lead. The right setup covers the methods your bettors already use in each market you hold a licence for, settled in currencies you can hold.
Controls Built Into the Cashier
The gateway should block credit cards where the law requires it, reject cards in another person's name, respect deposit limits and self-exclusion, and pass the data your geolocation and KYC checks need. Controls that sit in the gateway apply to every deposit, not only when someone remembers to check.
A Second Route and Terms That Improve
If all card deposits run through one acquirer, a single account review stops them all, and reviews tend to land in busy periods. Keep a second route live. Get a written commitment to review the rate and reserve once you have six to twelve months of clean history. Points that apply in every sector are covered in what to look for in a gateway.
One Form for Your Sports Betting Payment Gateway
You send us one form. We pick the partner, assemble the file and stay on the acquirer's questions until your first deposit has cleared.
- Partner chosen for you: picked for your licences, markets and volumes.
- No list of processors: one application instead of ten cold approaches.
- Licences and file checked: KYC pack, policies, site and app reviewed.
- Changes declared later: new skins, apps and markets added for you.
- Settlement banking too: help with the business account behind payouts.
- First deposits within days: for most sportsbooks with a complete file.
Bottom Line
A betting payment gateway is approved on your licences, your controls and your payouts, not on your volume. The sportsbooks that keep one hold a licence for every market they take bets from, show the notices Visa requires, block credit cards where the law says so, check age and location before the first bet, and pay winners quickly back to the methods that funded the account. They declare every skin and app before launch and plan payout cash with the reserve in mind.
Our part is the approval: one intake form, one regulated partner that takes betting, and for most operators a live cashier within 5 to 7 business days. If you also run lottery or poker products, see payment gateways for lottery and poker operators. For operators running casino and betting together, iGaming payment gateways covers the combined setup.
High Risk Payment Gateway and Merchant Account
Binderr Chooses
Time to onboard
5 to 7 days
Currencies
USD, EUR, GBP and more
Industries
Gambling, Adult, CBD, Crypto, Travel, Forex and more
What is a betting payment gateway?
Can a sportsbook use Stripe or PayPal?
Is a gambling licence required for a payment gateway for betting?
Why is sports betting a Tier 1 high risk category?
How much does a sportsbook payment gateway cost?
How are winnings paid back to bettors?
Can bettors deposit with a credit card?
How does a payment gateway for a betting app work?
Why do sportsbook deposits get declined?
What are the best payment gateways for sports betting platforms?
How do sportsbooks keep chargebacks low?
How long does approval take for a sports betting payment gateway?
How does Binderr set up a betting payment gateway?
Sources
- Visa Core Rules and Visa Product and Service Rules, April 2026, Visa
- Visa Integrity Risk Program guide, Visa
- Visa Acquirer Monitoring Program fact sheet, Visa
- Preventing credit card use, Gambling Commission
- Our position on light-touch financial vulnerability checks, Gambling Commission
- Murphy v. National Collegiate Athletic Association, Supreme Court of the United States
- Regulation GG, Unlawful Internet Gambling Enforcement Act, Federal Reserve
- Credit card cash advance fees after the legalization of sports gambling, CFPB
- Law 14,790 of 29 December 2023, Presidency of the Republic of Brazil
- Ontario's new iGaming market launch, iGaming Ontario