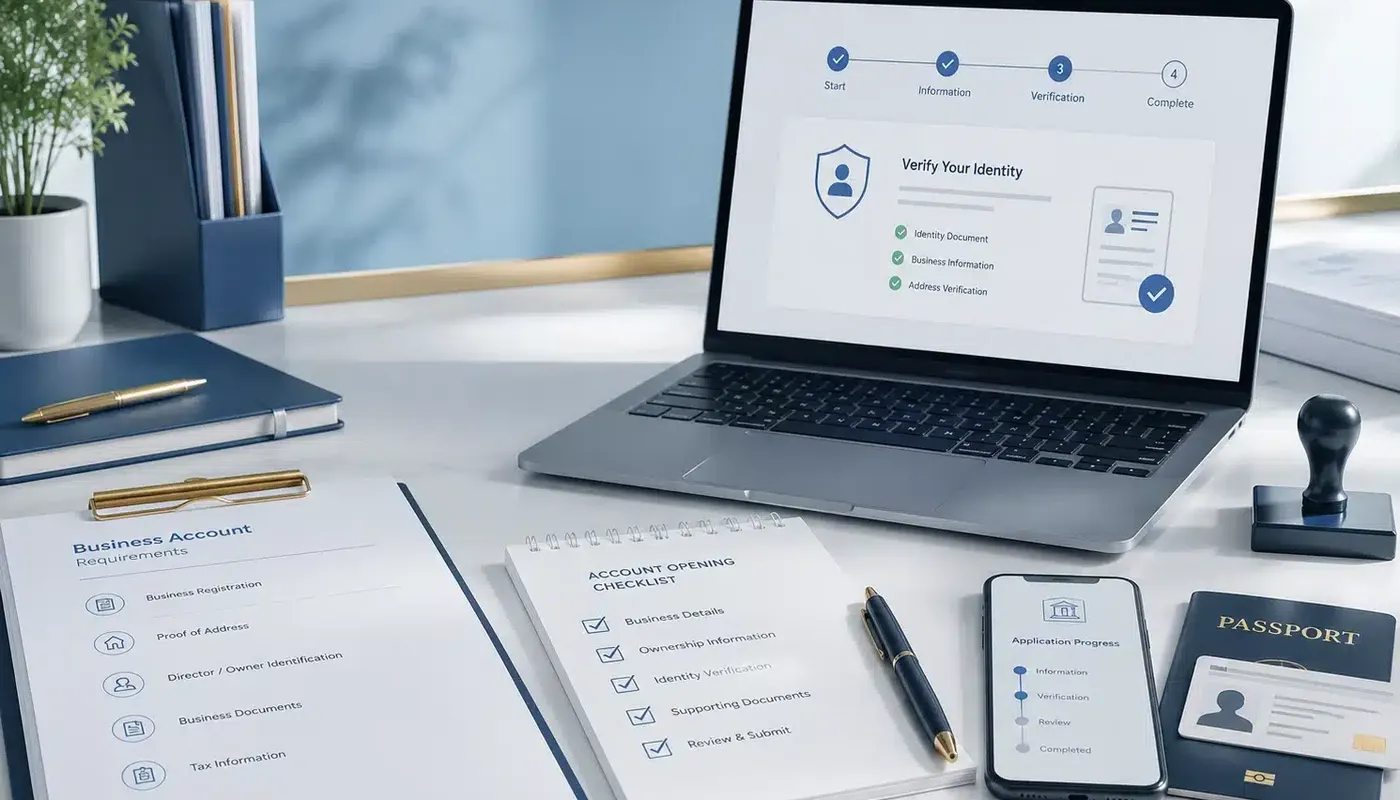
Verifying a company is only part of onboarding. Source of funds business checks help compliance teams understand where money comes from and whether it matches the customer’s profile.
A corporate source of funds review looks beyond the sending account to the underlying origin of the money, such as revenue, loans, investment, shareholder funding or asset sales.
Effective business SoF verification helps detect inconsistencies and support risk-based due diligence. FATF cites a UN estimate that around 2.7% of global GDP, or $1.6 trillion, was laundered in 2009, highlighting the scale of financial crime risks businesses may face.
In this guide, we cover how to verify Source of Funds, which documents to request, key red flags and practical compliance steps.
Binderr Corporate Compliance Software
Source of Funds verification works best when business identity, ownership, AML risk, and due diligence are assessed together. Binderr combines these checks within one compliance platform.
- Global KYB verification across 200+ countries
- Company registry data from 30,000+ sources
- UBO identification and ownership structure mapping
- AML screening for companies, directors, and UBOs
- Dynamic risk scoring based on customer data
- CDD and EDD workflows for deeper investigation
What Is Source of Funds?
Source of Funds (SoF) is the origin of money used in a transaction or business relationship. A source of funds business review checks where the money came from, who provided it, how it was generated, and whether it matches the company’s profile. Strong corporate source of funds and business SoF verification checks focus on the real economic origin of the funds, not just the sending account.
Run Your First KYB Check
Why Verify Source of Funds During Corporate Onboarding?
A strong corporate source of funds review helps compliance teams understand whether incoming money fits the customer’s business profile and stated activities.
Effective business SoF verification can uncover hidden risks, support due diligence, and strengthen source of funds business checks before onboarding is approved.
Detect potential money laundering - Unexpected or unexplained payments can point to layering, criminal proceeds, or attempts to hide the true origin of money. Strong source of funds business checks help teams identify suspicious funding before onboarding is completed.
Support risk-based due diligence - Not every customer carries the same level of risk. Business SoF verification helps compliance teams apply deeper checks where funding sources, jurisdictions, ownership structures, or transaction patterns require closer review.
Establish expected customer behaviour - Understanding how a company earns, receives, and moves money creates a baseline for future monitoring. A clear corporate source of funds profile makes unusual transactions easier to spot later.
Support EDD decisions - Complex ownership, PEP involvement, high-risk jurisdictions, or unexplained funding can justify enhanced due diligence. Business SoF verification gives teams the evidence needed to decide when deeper investigation is appropriate.
Identify inconsistencies early - A source of funds business review can reveal mismatches between declared activities, financial records, ownership, and actual funding patterns. Finding these gaps early helps prevent weak or incomplete onboarding decisions.
When Should Businesses Verify Source of Funds?
Businesses should verify Source of Funds when the level of financial crime risk justifies a closer look at where money originated. The exact source of funds business requirements vary by jurisdiction, sector, customer risk, transaction profile, regulatory rules, and the firm’s own AML policies.
A corporate source of funds review becomes especially important for high-risk customers, PEP-linked beneficial owners, unusually large transactions, high-risk jurisdictions, third-party funding, complex ownership structures, or activity that does not match the company’s stated business model.
Business SoF verification may also be needed when funding sources change unexpectedly, onboarding information is inconsistent, or adverse media raises concerns. In these situations, firms may need deeper evidence, additional due diligence, and stronger ongoing monitoring before accepting or continuing the relationship.
Source of Funds Documents for Corporate Customers
Source of Funds documents help compliance teams confirm whether a customer’s explanation matches the financial evidence. For effective source of funds business checks, the documents requested should reflect how the money was generated, who supplied it, and how it reached the company.
A strong corporate source of funds review should look beyond simply collecting paperwork. Teams should compare names, amounts, dates, counterparties, and transaction flows to confirm that the evidence supports the stated origin of funds.
Source of Funds | Possible Supporting Evidence |
Business revenue | Bank statements, customer invoices, sales contracts, audited or management accounts |
Shareholder investment | Share subscription agreement, cap table, shareholder records, transfer confirmation |
Bank loan | Signed loan agreement, lender confirmation, disbursement record, bank statement |
Private investment | Investment agreement, investor details, funding records, transfer evidence |
Asset sale | Sale agreement, proof of ownership, completion statement, payment record |
Dividends | Dividend voucher, board resolution, company accounts, bank statement |
Intercompany funding | Group structure, intercompany agreement, related-company accounts, transfer evidence |
Capital injection | Board or shareholder resolutions, share issue records, corporate filings, bank statement |
Grant or funding award | Grant approval letter, funding agreement, award notice, payment record |
Effective business SoF verification also checks whether these documents are genuine, current, internally consistent, and commercially reasonable. One document may not be enough where the transaction is unusually large, involves third parties, or does not match the company’s expected financial profile.
Verify Businesses Without the Manual Work
How to Verify Source of Funds for a Business
Effective business SoF verification starts with understanding the company, its ownership, and the real economic origin of the money.
A structured source of funds business process helps teams validate evidence, assess corporate source of funds risk, and document clear onboarding decisions.
Step 1: Verify the business entity
Start by confirming the company’s legal name, registration number, status, registered address, and jurisdiction using reliable corporate records. This creates the foundation for accurate source of funds business checks. It also confirms that the entity being reviewed is legitimate and active.
Cross-check the information against incorporation documents, registry data, and other independent sources. Any mismatch should be resolved before moving deeper into business SoF verification. Consistent records reduce the risk of relying on false or outdated company information.
Step 2: Identify ownership and control
Identify the company’s directors, shareholders, and beneficial owners to understand who ultimately owns or controls the business. This is especially important where funding may come from shareholders or related entities. Ownership details can also reveal links to higher-risk individuals or jurisdictions.
A clear ownership map helps teams connect the corporate source of funds to the people or entities behind the company. Complex ownership structures may require additional tracing and verification. Corporate shareholders should be followed through relevant ownership layers where necessary.
Step 3: Understand the business model
Review how the company operates, what it sells, where it does business, who its customers are, and how it normally earns revenue. This creates a benchmark for expected financial activity. It also helps determine whether the stated funding source is commercially plausible.
Effective source of funds business checks depend on context. A funding amount that looks reasonable for one company may be unusual for another based on size, revenue, sector, or transaction history. Compliance teams should compare the transaction with the company’s normal operating profile.
Step 4: Obtain a Source of Funds declaration
Ask the customer to clearly explain where the specific funds came from, who provided them, and why they are being used. Avoid vague answers such as “business income” or “investment funds.” The explanation should be specific enough to verify independently.
A useful corporate source of funds declaration should identify the underlying economic activity behind the money. This gives compliance teams a clear claim to test against supporting evidence. It can also help determine which documents should be requested next.
Step 5: Collect supporting documents
Request documents that match the declared funding source, such as bank statements, invoices, financial accounts, loan agreements, investment records, or sale contracts. The type of evidence should reflect how the money was supposedly generated.
Strong business SoF verification focuses on relevance, not volume. The evidence should directly support how the funds were generated and how they reached the customer. Multiple documents may be required when the funding route is complex or higher risk.
Step 6: Trace the flow of funds
Follow the money from its original source through relevant accounts, companies, or intermediaries to the final transaction. This helps uncover unnecessary complexity or unexplained third-party involvement. The transaction path should be clear enough to connect the funds to their stated origin.
For source of funds business reviews, the payment path should make commercial sense. Multiple unexplained transfers or unrelated entities may require deeper investigation. Compliance teams should also check whether the parties involved have a legitimate relationship with the customer.
Step 7: Cross-check evidence against the customer profile
Compare amounts, dates, counterparties, and transaction activity with the company’s stated business model, expected revenue, and onboarding information. The evidence should align with what is already known about the customer.
A strong corporate source of funds review should identify whether the funding fits the company’s financial profile. Significant inconsistencies should be clarified and supported with additional evidence. Unexplained gaps may justify escalation or enhanced due diligence.
Step 8: Assess risk and document the decision
Review sanctions, PEP, adverse media, jurisdictional, and transaction risks alongside the Source of Funds evidence. Apply enhanced due diligence where the overall risk is elevated. The final risk assessment should consider both the customer and the funding source.
Complete business SoF verification by recording the evidence reviewed, discrepancies identified, actions taken, and final decision. A clear audit trail helps explain why the funds were accepted, escalated, or rejected. It also supports future reviews and ongoing monitoring.
Streamline Business SoF Verification With Binderr
Source of Funds checks often require multiple business, ownership, and risk assessments. Binderr helps compliance teams bring these steps into one structured workflow instead of switching between disconnected systems.
- Verify company details using global registry data
- Identify directors, shareholders, and UBOs
- Map complex ownership structures across entities
- Screen relevant parties for sanctions, PEPs, and adverse media
- Apply automated risk scores to collected information
- Trigger EDD workflows when higher risk is identified
How Much Evidence Is Enough?
The right level of evidence depends on risk, not a fixed document count. For lower-risk source of funds business cases, a clear explanation supported by consistent financial records may be enough. Strong business SoF verification should focus on whether the evidence is credible, relevant, and proportionate to the customer’s risk profile.
Higher-risk corporate source of funds cases may require multiple documents, independent checks, transaction history, ownership analysis, beneficial-owner SoF or SoW evidence, external data, and senior approval. AUSTRAC supports this risk-based approach, so firms should avoid rigid rules such as assuming one bank statement is always sufficient.
Best Practices for Corporate Source of Funds Verification
Strong corporate source of funds checks combine clear customer context, reliable evidence, and consistent risk assessment.
Following practical business SoF verification practices helps compliance teams improve source of funds business reviews and make better-supported onboarding decisions.
Understand the customer's business before reviewing SoF - Review how the company operates, earns revenue, serves customers, and moves money before assessing its funding. This gives the corporate source of funds review the commercial context needed to judge whether the stated source is reasonable.
Use independent sources where appropriate - Support customer-provided information with reliable external data such as corporate registries, financial records, or other authoritative sources. Independent checks can strengthen business SoF verification and reduce reliance on self-declared information.
Reconcile documents, amounts and counterparties - Compare bank statements, invoices, contracts, transaction dates, and counterparties to confirm they tell the same financial story. Effective source of funds business checks should connect the evidence to the actual movement and origin of money.
Investigate inconsistencies rather than ignoring them - Differences in names, amounts, dates, ownership details, or payment routes should be explained before approval. Even small discrepancies can point to incomplete information, third-party funding, or a more complex transaction trail.
Link SoF conclusions to customer risk scoring - Source of Funds findings should feed into the wider customer risk assessment. Clear, well-supported funding may reduce uncertainty, while unexplained or high-risk funding can justify stronger controls or enhanced due diligence.
Reassess SoF when material changes occur - Source of Funds should not always be treated as a one-time onboarding check. New investors, ownership changes, unusual transaction growth, new jurisdictions, or unexpected funding sources may justify fresh business SoF verification.
Trace Ownership and Screen the People Behind the Funds Using Binderr
When corporate funding comes from shareholders, investors, parent companies, or beneficial owners, understanding who sits behind the business becomes critical. Binderr helps uncover ownership structures and assess associated AML risk.
- Identify Ultimate Beneficial Owners
- Unravel multi-layered ownership chains
- Visualise complex corporate relationships
- Verify directors and shareholders
- Screen UBOs against sanctions and PEP databases
- Detect adverse media and hidden risk exposure
What If the Funds Come From a Shareholder or Beneficial Owner?
Corporate customers do not always fund transactions from trading revenue. A corporate source of funds review may show that the money actually comes from a founder, shareholder, parent company, investor, or beneficial owner.
Where a shareholder or UBO is the real economic source, business SoF verification may need to go beyond the company itself. Compliance teams may need to establish how that person or entity obtained the funds, whether the amount is plausible, and whether supporting evidence matches the stated source.
For higher-risk source of funds business cases, Source of Funds and Source of Wealth checks may therefore extend to the beneficial owner.
Find the People Behind the Business
Common Source of Funds Verification Mistakes to Avoid
Even strong compliance processes can fail when source of funds compliance focuses on collecting evidence without testing whether it tells a credible financial story.
Following practical source of funds best practices helps teams strengthen business SoF verification, spot inconsistencies early, and avoid weak onboarding decisions.
Mistake 1: Treating a bank account as the Source of Funds
Problem: A bank statement only shows where money was held or sent from. It does not always explain how the customer originally obtained the funds.
Solution: Trace the underlying economic source, such as revenue, a loan, investment, or asset sale. Strong source of funds compliance looks beyond the sending account.
Mistake 2: Accepting vague explanations
Problem: Statements such as “business income” or “investment funds” provide little evidence about how the money was actually generated.
Solution: Ask for specific details and supporting records, including invoices, contracts, accounts, or investment documents. This strengthens business SoF verification.
Mistake 3: Ignoring beneficial owners
Problem: Corporate funds may ultimately come from a shareholder, founder, or beneficial owner rather than from the company’s operating activity.
Solution: Extend the corporate source of funds review to the relevant individual or entity where necessary, especially in higher-risk cases.
Mistake 4: Collecting documents without analysing them
Problem: Gathering bank statements, invoices, or agreements does not prove that the stated Source of Funds is credible.
Solution: Compare names, dates, amounts, counterparties, and transaction flows. Good source of funds best practices focus on verification, not document volume.
Mistake 5: Checking amounts but not commercial logic
Problem: A transaction can be fully documented and still make little sense for the customer’s size, sector, or business model.
Solution: Assess whether the funding fits the company’s expected activity, revenue, and commercial purpose. Unusual patterns should trigger further review.
Mistake 6: Performing SoF only once
Problem: A Source of Funds profile can become outdated when ownership, investors, transaction volumes, or funding routes change.
Solution: Reassess source of funds business information after material changes and during ongoing monitoring where the customer’s risk profile justifies it.
Manage Corporate Due Diligence End to End With Binderr
Source of Funds verification is only one part of a wider corporate compliance process. Binderr brings KYB, AML screening, ownership checks, risk assessment, CDD, EDD, and ongoing monitoring together in a single workspace.
- Verify companies with global KYB checks
- Identify and map directors, shareholders, and UBOs
- Screen sanctions, PEPs, watchlists, and adverse media
- Automatically assess and score customer risk
- Trigger enhanced due diligence for higher-risk cases
- Monitor customers continuously and maintain audit trails
Bottom Line
Strong source of funds business checks help compliance teams understand where money comes from, whether it fits the customer’s profile, and when deeper due diligence is needed. A reliable corporate source of funds process should connect customer explanations with supporting evidence, ownership data, transaction patterns, and risk indicators.
Effective business SoF verification is not about collecting more documents than necessary. It is about gathering the right evidence, testing whether the financial story makes sense, and keeping the assessment current when material changes occur.
Binderr Services helps streamline corporate onboarding with KYB, AML screening, ownership checks, risk scoring, and ongoing monitoring in one compliance workspace.