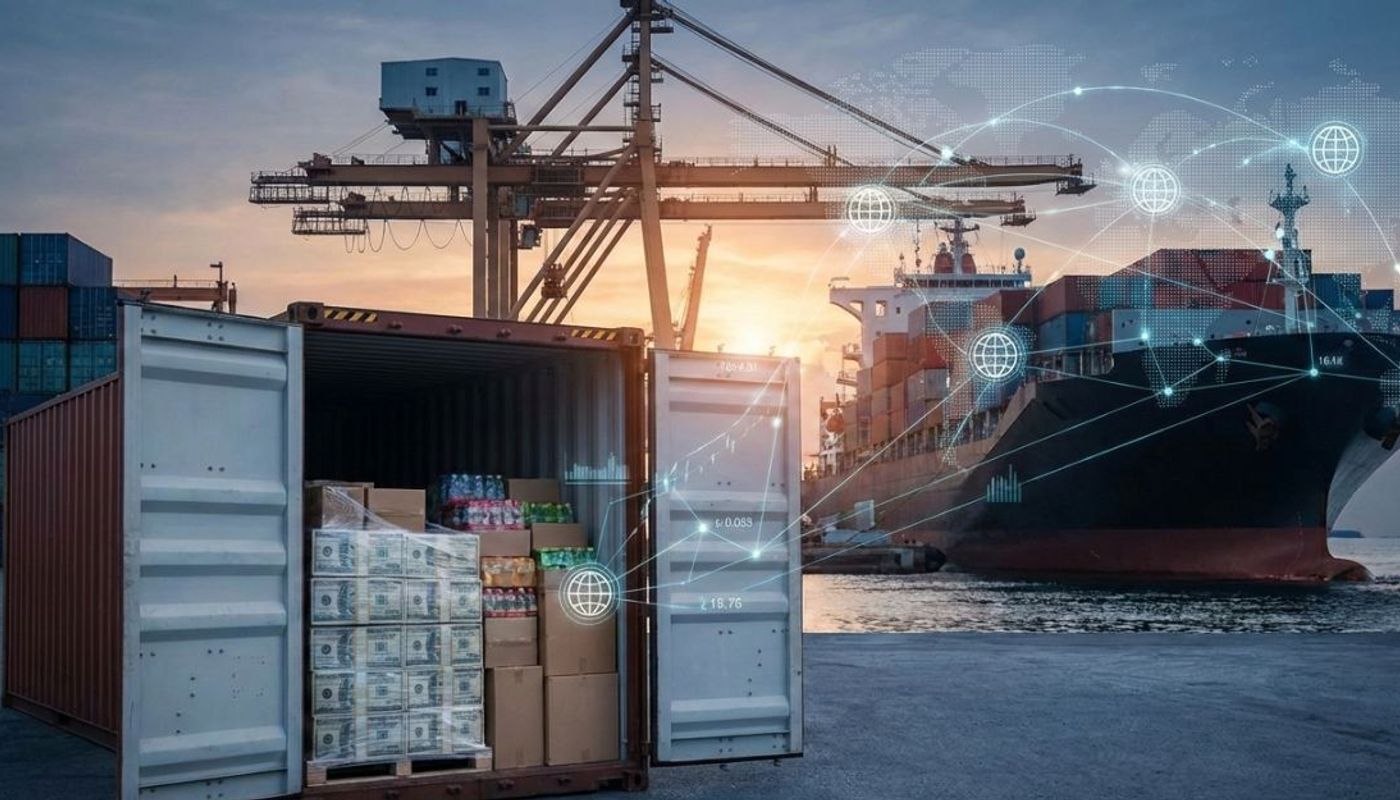
Global trade moves goods and money across borders every day, but not every transaction is what it appears to be. Criminals exploit legitimate trade channels through inflated invoices, falsified shipments, and suspicious payments to conceal illicit funds. This practice is known as trade based money laundering (TBML).
According to UN Trade and Development (UNCTAD), global trade reached a record $33 trillion in 2024. With such enormous transaction volumes, distinguishing genuine commercial activity from TBML schemes presents a major challenge for financial institutions and compliance teams.
Effective trade finance AML controls help businesses identify suspicious trading patterns, verify counterparties, and investigate unusual transactions. This guide explains how trade based money laundering works, its common methods, real-world examples, key red flags, and practical detection strategies.
Simplify Trade Finance AML With Binderr Compliance Software
Detecting trade-based money laundering starts with knowing who you're doing business with. Binderr brings business verification, AML screening, and risk assessment into one platform to help identify financial crime risks.
- Global KYB Verification: Verify trading businesses across 200+ countries.
- Beneficial Ownership Checks: Identify UBOs and hidden corporate relationships.
- AML Screening: Screen businesses and individuals against sanctions, PEPs, and watchlists.
- Adverse Media Screening: Identify negative news and financial crime exposure.
- Dynamic Risk Scoring: Assess customer and counterparty risk automatically.
- Ongoing Monitoring: Receive alerts when relevant risk profiles change.
What Is Trade-Based Money Laundering (TBML)?
Trade-based money laundering (TBML) involves disguising criminal proceeds through international trade. According to FATF, criminals manipulate the price, quantity, or quality of goods to transfer illicit value across borders.
For example, invoicing goods worth $50,000 at $100,000 can conceal an additional $50,000 transfer. Trade based money laundering can involve legitimate businesses, intermediaries, and payments outside traditional trade finance. Effective trade finance AML controls help detect suspicious transactions and pricing discrepancies.
Start AML Screening for Free
How Does Trade-Based Money Laundering Work?
Trade-based money laundering (TBML) involves disguising illicit financial transfers as legitimate international trade transactions. Criminals exploit businesses, manipulate trade documents, and move funds across borders to conceal their origins.
Understanding the TBML process helps compliance teams identify suspicious activity and strengthen trade finance AML controls.
Step 1: Establish or Exploit a Trading Business
Criminals may establish shell companies, acquire existing businesses, or use connected entities to create seemingly legitimate trading relationships. These businesses act as importers, exporters, or intermediaries in international transactions.
Complex ownership structures and multiple trading partners can make identifying the individuals controlling these businesses difficult. This allows criminals to conceal their involvement behind apparently genuine commercial operations.
Step 2: Manipulate Trade Documents or Transactions
In trade based money laundering, criminals may falsify invoices, purchase orders, shipping records, or product descriptions to misrepresent the value or quantity of goods being traded.
For example, an exporter might invoice goods worth $20,000 at $80,000, creating a $60,000 discrepancy. Such manipulation can justify unusually large payments while making the transaction appear commercially legitimate.
Step 3: Transfer Money Through Trade Payments
Once manipulated documents are prepared, funds move between importers, exporters, or third-party intermediaries as payments for goods or services. These transfers may pass through legitimate financial institutions.
In TBML schemes, payments can exceed actual trade values or involve unrelated third parties. Without effective trade finance AML checks, suspicious transfers may resemble ordinary commercial settlements.
Step 4: Conceal the Origin or Beneficiary of Funds
Criminals may route payments through multiple companies, jurisdictions, or intermediary accounts to obscure the original source of funds and the individuals benefiting from the transactions.
Layered ownership structures, unexplained third-party payments, and repeated transfers make tracing financial activity difficult. These arrangements can conceal connections between criminal proceeds and seemingly legitimate businesses.
Step 5: Integrate the Funds Into Commercial Activity
After moving through trade transactions, illicit funds may appear as legitimate business revenue, export earnings, settlement payments, or trading profits.
Businesses may then use these funds for investments, supplier payments, or further commercial transactions. This final stage makes trade-based money laundering harder to distinguish from genuine economic activity and reinforces the importance of ongoing transaction monitoring.
Common Trade-Based Money Laundering Methods
Trade-based money laundering (TBML) schemes exploit international trade by manipulating invoices, shipment details, product values, and payment arrangements to conceal illicit financial transfers.
Here are seven common TBML methods that businesses and compliance teams should recognize to strengthen trade finance AML controls.
Over-Invoicing
Over-invoicing occurs when exporters deliberately charge more than the actual value of goods to justify inflated payments. For example, goods worth $40,000 may be invoiced at $90,000, allowing an additional $50,000 to move between trading parties. This TBML method disguises excess fund transfers as legitimate trade payments, making unusual pricing patterns an important warning sign for compliance teams.
Under-Invoicing
Under-invoicing involves declaring goods at prices significantly below their actual commercial value. For instance, an exporter might sell goods worth $100,000 for just $30,000, allowing the importer to receive an additional $70,000 in economic value. The importer may later resell the goods at market prices, converting the hidden value into apparent legitimate business revenue. This form of trade misinvoicing can facilitate cross-border value transfers.
Multiple Invoicing
Multiple invoicing occurs when criminals issue duplicate invoices for the same shipment to justify repeated payments. For example, a single shipment worth $50,000 may be invoiced three times, resulting in payments totaling $150,000. By presenting each payment as a separate commercial obligation, this trade based money laundering technique can disguise illicit transfers within routine business transactions.
Over-Shipment and Under-Shipment
Over-shipment and under-shipment involve deliberately shipping more or fewer goods than stated in trade documents. For example, an exporter may invoice 500 electronic devices but deliver only 200, allowing payment for goods that were never shipped. Alternatively, delivering more goods than declared can transfer additional economic value to the importer. These discrepancies are important TBML red flags when reviewing international trade activity.
Phantom Shipments
Phantom shipments involve creating fictitious trade transactions where invoices, shipping records, and payment instructions exist, but no goods are actually transported. Criminals may use fabricated documentation to justify large international transfers between businesses. Because payments appear linked to commercial purchases, these schemes can be difficult to identify without shipment verification and effective trade finance AML checks.
Misrepresentation of Goods
Misrepresentation of goods occurs when criminals deliberately falsify product descriptions, quality, grade, or commercial value in trade documents. For example, inexpensive industrial materials may be declared as high-value electronic components to justify inflated payments. Such discrepancies can conceal the actual value being transferred, making accurate product documentation and transaction reviews essential for detecting trade-based money laundering.
Third-Party Payments and Complex Trade Networks
Criminals may route trade payments through unrelated companies, intermediaries, or businesses operating across multiple jurisdictions to conceal the true source and destination of funds.
For example, an importer might receive goods from one supplier while sending payments to an unrelated company in another country. These arrangements can obscure beneficial ownership and financial relationships, making KYB verification, counterparty screening, and transaction monitoring important TBML detection measures.
Why Is Trade-Based Money Laundering Difficult to Detect?
Trade-based money laundering (TBML) is difficult to detect because criminals exploit complex trade networks, fragmented financial records, and legitimate commercial transactions to conceal illicit funds.
Here are five major TBML detection challenges that make identifying suspicious activity difficult for financial institutions and trade finance AML teams.
High Volumes of International Trade
Global trade involves millions of transactions, invoices, and cross-border payments, making individual reviews time-consuming and resource-intensive. Criminals exploit these high volumes to hide suspicious payments among legitimate business transactions. Without automated monitoring and risk-based trade finance AML controls, unusual transaction patterns may go unnoticed.
Complex Supply Chains and Corporate Structures
International trade often involves manufacturers, exporters, importers, shipping companies, and intermediaries operating across different jurisdictions. Criminals may exploit layered ownership structures, shell companies, and connected businesses to disguise their involvement. These complicated relationships make identifying beneficial owners and tracing trade based money laundering activities particularly challenging.
Fragmented Financial and Trade Data
Banks, customs authorities, shipping companies, and trading businesses often maintain separate records of the same transaction. Financial institutions may see payment details but lack access to customs declarations, shipment records, or complete trade documentation. These information gaps make it harder to identify inconsistencies and connect suspicious activities across the TBML process.
Limited Visibility Into Goods and Shipments
Financial institutions often rely on invoices, shipping documents, and customer-provided information without physically inspecting traded goods. This makes verifying actual shipment quantities, product quality, and fair commercial pricing difficult. Criminals can exploit these limitations through phantom shipments, misrepresented goods, or inflated invoices, creating significant TBML detection challenges.
Difficulty Distinguishing Legitimate Trade Variations
Trade prices naturally fluctuate due to product quality, transportation costs, market conditions, and negotiated commercial terms. These legitimate differences can resemble suspicious pricing patterns associated with trade-based money laundering. For example, unusually expensive goods may reflect genuine shipping costs rather than invoice manipulation, requiring compliance teams to investigate the commercial context before identifying potential TBML risks.
How to Detect and Prevent Trade-Based Money Laundering
Effective trade-based money laundering (TBML) detection requires verifying trading partners, monitoring cross-border transactions, and identifying suspicious financial activities through risk-based compliance controls.
Here are seven essential steps to strengthen trade finance AML processes, reduce TBML risks, and prevent illicit funds from entering legitimate trade channels.
Step 1: Conduct KYC and KYB Verification
Start by verifying the identities of customers, importers, exporters, and trading partners through Know Your Customer (KYC) and Know Your Business (KYB) checks. Confirm business registration details, operating addresses, industry classifications, and the legitimacy of declared commercial activities.
Compare each company's trading profile with its transaction history, expected trade volumes, and business operations. Unusual activity, such as a newly registered company conducting high-value international transactions without a credible business explanation, may indicate potential TBML risks.
Step 2: Identify Ultimate Beneficial Owners
Identify the ultimate beneficial owners (UBOs) of businesses involved in trade transactions to understand who ultimately owns or controls them. Examine shareholder records, corporate structures, and ownership relationships across different jurisdictions.
Look for common ownership between importers and exporters, hidden controllers, or companies sharing directors and addresses. These connections may reveal coordinated trade based money laundering schemes designed to conceal the true beneficiaries of financial transfers.
Step 3: Screen Parties Against Sanctions, PEPs and Adverse Media
Screen importers, exporters, beneficial owners, directors, and relevant intermediaries against sanctions lists, politically exposed person (PEP) databases, and adverse media sources. These checks help identify potential financial crime exposure and higher-risk business relationships.
Integrate screening results into trade finance AML risk assessments and investigate relevant matches before proceeding. However, screening alone cannot verify the legitimacy of invoice prices, shipment quantities, or trade payments, making additional transaction reviews essential.
Check Sanctions and PEPs
Step 4: Assess Trade Documents and Transaction Patterns
Review invoices, purchase orders, bills of lading, customs declarations, and payment records to identify inconsistencies in product descriptions, prices, quantities, or shipment details. Compare available documentation to determine whether transactions reflect genuine commercial activity.
Investigate duplicate invoices, unusual pricing differences, unexplained third-party payments, and mismatched shipment records. These discrepancies may indicate over-invoicing, under-invoicing, or phantom shipments associated with trade-based money laundering.
Step 5: Apply Risk-Based Transaction Monitoring
Monitor cross-border payments, transaction frequency, trade volumes, and counterparty relationships against established customer risk profiles. Automated monitoring systems can flag unusual payment patterns, sudden increases in trading activity, and transactions involving higher-risk jurisdictions.
Adjust monitoring intensity based on customer behavior, geographic exposure, and transaction complexity. Risk-based TBML detection helps compliance teams prioritize suspicious activity while reducing unnecessary reviews of legitimate trade transactions.
Step 6: Investigate Unusual Activity and Conduct Enhanced Due Diligence
When suspicious transactions arise, conduct enhanced due diligence (EDD) by requesting supporting invoices, shipping records, contracts, and explanations of the commercial purpose. Verify the source of funds, business relationships, and economic rationale behind unusual payments.
Escalate unresolved discrepancies to compliance teams for further investigation. Strong TBML prevention procedures require evaluating multiple risk indicators together rather than treating an isolated red flag as conclusive evidence of money laundering.
Step 7: Maintain Audit Trails and Report Suspicious Activity
Maintain detailed records of customer verification, trade document reviews, screening results, transaction alerts, and investigation decisions. Complete audit trails help demonstrate compliance with applicable trade finance AML obligations and support regulatory examinations.
Establish clear escalation procedures for suspected trade based money laundering and submit suspicious activity reports to relevant authorities when legally required. Periodically reassess customer risks and update monitoring controls to identify emerging TBML patterns.
Streamline TBML Risk Checks With Binderr
Manual verification and fragmented compliance checks can slow trade finance AML investigations. Binderr simplifies customer verification, business ownership checks, and risk-based due diligence through a unified compliance workflow.
- Automated KYC Checks: Verify individuals using AI-powered identity verification.
- Instant KYB Checks: Retrieve company registration and director information.
- UBO Identification: Uncover ultimate owners and complex ownership chains.
- Integrated AML Screening: Check sanctions, PEPs, watchlists, and adverse media.
- Risk-Based Due Diligence: Support CDD and EDD with automated risk scoring.
- Compliance Audit Trails: Maintain verification records and investigation histories.
What Are the Red Flags of Trade-Based Money Laundering?
Trade-based money laundering (TBML) red flags include unusual trade transactions, inconsistent documents, suspicious payments, and hidden business relationships that may indicate illicit financial activity.
Here are four key categories of TBML risk indicators that compliance teams should assess together to strengthen trade finance AML controls.
Business and Ownership Red Flags - Unclear beneficial ownership, complex corporate structures, and unexplained trading relationships can indicate TBML risks. Other warning signs include newly registered companies handling large transactions, businesses trading unrelated goods, and importers or exporters sharing undisclosed owners.
Uncover Hidden Business Connections
Trade Document and Shipment Red Flags - Inconsistent invoices, altered shipping records, and unexplained pricing or quantity differences are common TBML warning signs. Duplicate documents, vague product descriptions, and unusual shipping routes may indicate manipulated transactions requiring further investigation.
Payment and Transaction Red Flags - Payments from unrelated third parties, rapid fund transfers, and unusual settlement arrangements may indicate trade based money laundering. Transactions inconsistent with normal business activity or involving unexplained cross-border payments require closer trade finance AML scrutiny.
Geographic and Counterparty Red Flags - Trading with higher-risk jurisdictions, using unnecessary intermediaries, or routing payments through unrelated countries can raise TBML concerns. Counterparties with sanctions exposure, adverse media, or unclear ownership may require enhanced due diligence.
Uncover Hidden Business Risks With Binderr KYB Software
Opaque ownership structures and suspicious trading relationships can increase TBML risks. Binderr's KYB software helps compliance teams verify counterparties, investigate corporate ownership, and identify potential financial crime exposure.
- Global Registry Access: Access company information from 30,000+ sources.
- Business Verification: Confirm registration details and operational status.
- Ownership Mapping: Visualize complex corporate ownership structures.
- UBO Verification: Identify individuals who ultimately own or control businesses.
- Director Screening: Assess directors and shareholders for AML risk exposure.
- Connected Entity Checks: Uncover hidden corporate relationships and affiliations.
Best Practices to Strengthen TBML Compliance Controls
Effective trade-based money laundering (TBML) prevention requires consistent risk assessments, transparent business relationships, and continuous monitoring.
Strong trade finance AML controls help businesses identify suspicious trade activities and reduce financial crime exposure.
Adopt Risk-Based Due Diligence - Apply due diligence measures based on customer profiles, trading partners, geographic exposure, and transaction risks. High-risk businesses or unusual cross-border transactions may require enhanced verification, additional documentation, and closer monitoring to strengthen TBML prevention.
Verify Corporate Ownership - Identify ultimate beneficial owners (UBOs), shareholders, and connected entities to uncover hidden business relationships. Examine complex ownership structures and shared directors between trading partners, as these connections may indicate potential trade based money laundering risks requiring further investigation.
Assess Trade Activity Against Business Profiles - Compare transaction values, shipment volumes, trading partners, and product categories against a company's declared business activities. Sudden increases in trade volumes, unusual goods, or transactions inconsistent with expected operations may indicate suspicious activity and require additional trade finance AML reviews.
Combine Screening With Trade-Data Reviews - Integrate sanctions, PEP, and adverse media screening with available invoices, shipping records, payment details, and ownership information. Reviewing these data sources together helps compliance teams identify inconsistencies, assess TBML risk indicators, and investigate suspicious transactions more effectively.
Monitor Changes in Counterparty Risk - Regularly review trading partners for changes in sanctions exposure, beneficial ownership, adverse media, and business activities. Continuous monitoring helps identify emerging TBML risks, allowing compliance teams to reassess relationships and apply enhanced due diligence when necessary.
Document Investigations and Decisions - Maintain detailed records of risk assessments, screening results, trade document reviews, and investigation outcomes. Establish consistent escalation procedures, evidence retention practices, and suspicious activity reporting processes to support trade-based AML compliance and regulatory accountability.
Regulatory Framework and Guidance for TBML Prevention
Global regulatory frameworks and AML guidelines help financial institutions identify trade-based money laundering (TBML) risks through due diligence, transaction monitoring, and suspicious activity reporting.
Here are the key regulatory frameworks and international guidelines that support TBML prevention and strengthen trade finance AML compliance.
Framework or authority | What to cover |
FATF | Risk-based AML controls, due diligence, beneficial ownership and international cooperation |
FATF–Egmont Group | TBML typologies, risk indicators, detection challenges and information sharing |
FinCEN | US financial institution guidance on identifying and reporting suspicious activity linked to trade |
Wolfsberg Group / ICC / BAFT | Good-practice financial crime controls for trade finance |
HMRC / UK AML framework | Practical TBML investigations and the application of UK money laundering laws |
Strengthen Trade Finance AML Compliance With Binderr
Managing trade-based money laundering risks requires more than one-time customer checks. Binderr combines verification, AML screening, due diligence, and continuous monitoring to help businesses manage financial crime exposure throughout the customer lifecycle.
- End-to-End KYC & KYB: Verify individuals, businesses, and trading counterparties.
- Complete AML Screening: Identify sanctions, PEP, watchlist, and adverse media risks.
- UBO & Ownership Mapping: Reveal complex corporate structures and controlling individuals.
- Automated Risk Assessment: Apply dynamic risk scoring to customer and business profiles.
- CDD & EDD Workflows: Streamline standard and enhanced due diligence processes.
- Continuous Risk Monitoring: Track risk changes with alerts and compliance records.
Bottom Line
Trade-based money laundering (TBML) exploits international trade through manipulated invoices, false product descriptions, suspicious payments, and complex business relationships. Detecting trade based money laundering requires business verification, ownership checks, transaction analysis, and ongoing risk assessments to identify suspicious activity.
Strong trade finance AML controls help businesses identify TBML risks and protect legitimate transactions. Binderr Services supports this process with automated KYC, KYB, UBO verification, AML screening, risk scoring, and ongoing monitoring, helping compliance teams strengthen due diligence and financial crime prevention.